IoT Security Market Summary
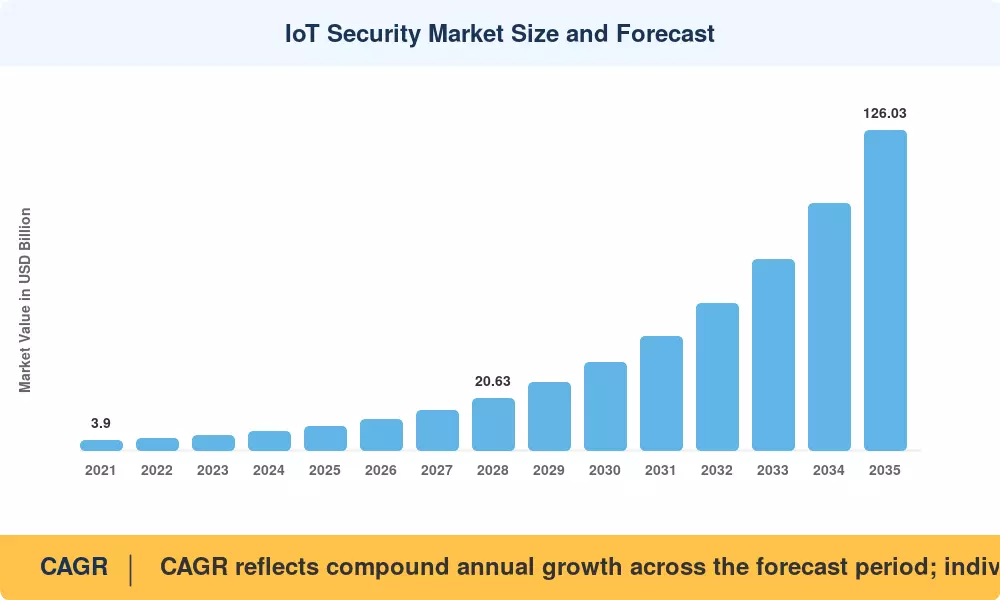
The IoT Security Market reached USD 9.50 billion in 2025, positioning for a forecast-period opening of USD 12.30 billion in 2026 and a trajectory toward USD 126.03 billion by 2035 at a 29.5% CAGR. Two catalysts are pulling capital into the space faster than budget cycles can absorb: the European Union's Cyber Resilience Act, which converts product security from voluntary guidance into a legal obligation across the single market, and the United Kingdom's Product Security and Telecommunications Infrastructure Act, which bans default passwords and compels vulnerability-disclosure timelines. Together, these regulations redirected an estimated USD 4.2 billion in enterprise cybersecurity budgets toward IoT-specific controls between 2023 and 2025 [1].
Legacy perimeter firewalls and static signature-based tools are giving way to cloud-delivered, AI-driven platforms capable of behavioral analytics across millions of heterogeneous endpoints. Operational technology networks that once ran air-gapped are now merging with corporate IT stacks, creating sprawling attack surfaces that demand automated, standards-aligned security. estimates that by 2027, more than 75% of enterprises will manage connected-device risk through unified cloud security platforms rather than siloed point products [2].
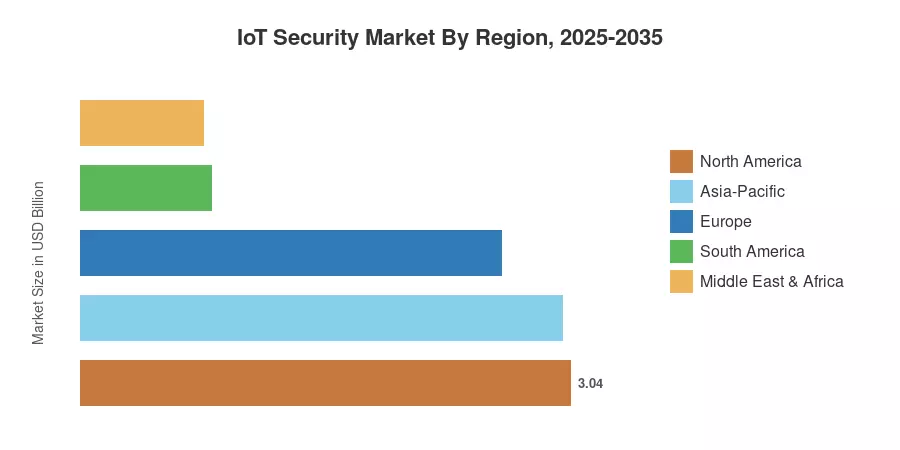
North America held a 32.0% share of the IoT Security Market in 2025, anchored by federal zero-trust mandates and deep venture-capital investment in device-identity startups. Asia-Pacific is the fastest-growing region at a projected 31.5% CAGR, driven by massive smart-city programs across China and India. Europe stands as the second-largest region, accounting for 27.5% of revenue on the strength of compliance-led procurement. The decade ahead will reward vendors that pair automated threat detection with regulatory-certification tooling at scale.
Key Report Takeaways
• By Security Type
- Network Security captured the dominant position in the IoT Security Market in 2025 with a 38.5% share, reflecting enterprise reliance on perimeter-level inspection for industrial IoT corridors.
- Cloud/Virtual Security is forecast to record the fastest expansion at a 31.5% CAGR through 2035, as organizations migrate security workloads to multi-tenant cloud platforms.
• By Component
- Solutions accounted for 53.0% of the IoT Security Market in 2025, with integrated suites displacing standalone tools.
- Services are tracking a 32.2% CAGR to 2035, fueled by managed-detection-and-response contracts and compliance advisory engagements.
• By End-User Industry
- Smart Manufacturing commanded a 24.5% share of the IoT Security Market in 2025, driven by ICS/SCADA protection requirements across discrete and process industries.
- Energy & Utilities is projected to grow at 30.2% CAGR through 2035 as grid-edge devices and smart metering installations proliferate.
• By Deployment Mode
- Cloud/SECaaS captured 41.8% of the IoT Security Market in 2025, favored by mid-market firms seeking OpEx-based security consumption.
• By Region
- North America led with 32.0% of 2025 revenue, propelled by CISA IoT guidance and insurance-sector mandates.
- Asia-Pacific is forecast to grow at a 31.5% CAGR, the fastest among all regions.
IoT Security Market Size and Forecast (2021–2035)
Market Research Future's sizing model integrates primary interviews with 180+ enterprise CISOs and OT security officers, cross-validated against vendor-reported bookings, disclosed contract values, and regulatory-impact assessments from ENISA and NIST. Historical figures (2021–2024) rely on audited company filings and verified channel-partner data, while forecasts apply a proprietary regression framework adjusted for policy-driven demand surges.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


