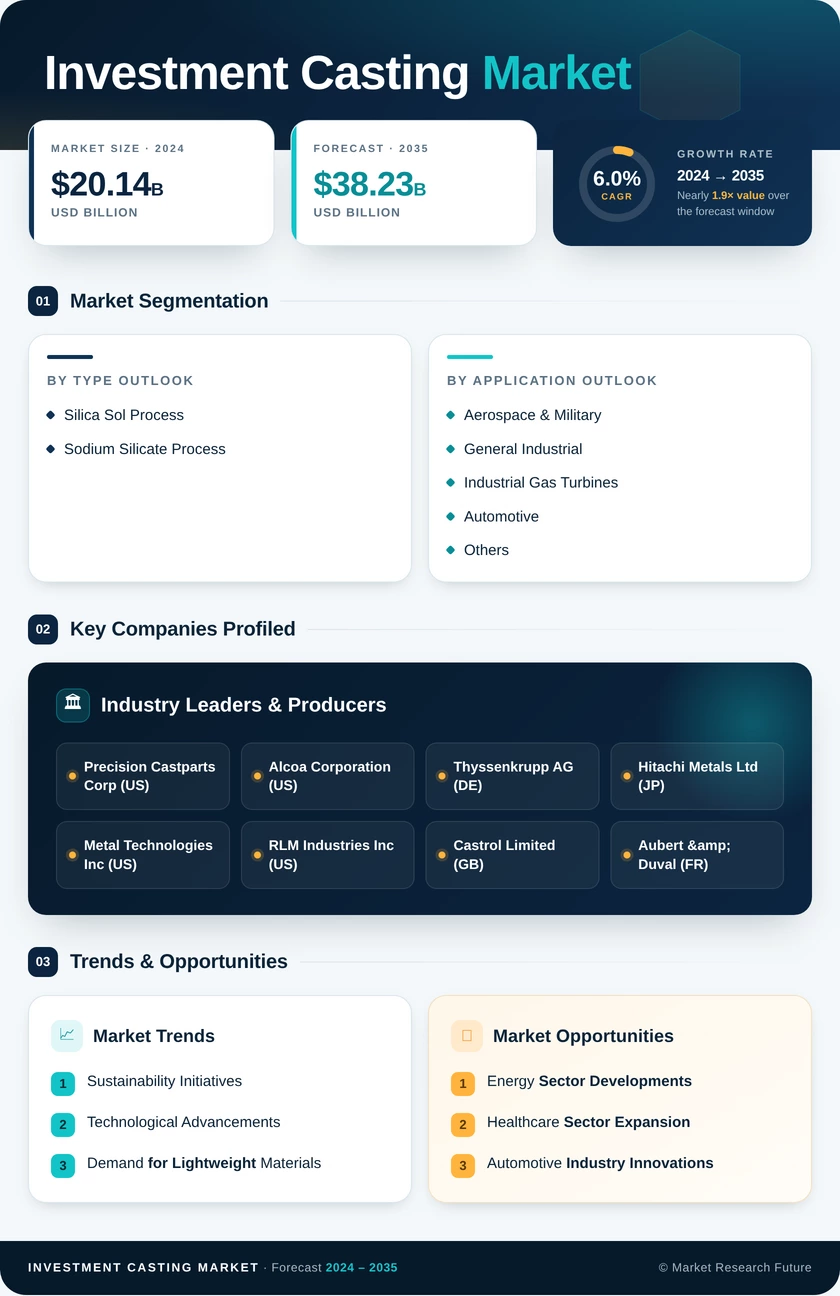
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Process Type | Silica-Sol; Water-Glass; Hybrid and Other Processes | Silica-Sol | Hybrid and Other Processes |
| By Material | Stainless Steel; Superalloys; Aluminium Alloys; Titanium Alloys; Carbon and Low-Alloy Steel; Others | Stainless Steel | Superalloys |
| By End-User | Aerospace and Defense; Energy and Power; Automotive; Industrial Machinery; Medical; Others | Aerospace and Defense | Energy and Power |
| By Pattern Technology | Conventional Wax Patterns; 3D-Printed and Rapid Prototype Patterns | Conventional Wax Patterns | 3D-Printed and Rapid Prototype Patterns |
| By Component Weight | Up to 1 kg; 1–10 kg; Above 10 kg | 1–10 kg | Up to 1 kg |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific | North America |
Market Segmentation Overview
By Process Type
| Sub-Segment | Key Trend |
| Silica-Sol | Expanding into medical and semiconductor equipment work as tolerance demands tighten |
| Water-Glass | Holding volume in pumps and valves while ceding share on finish-critical parts |
| Hybrid and Other Processes | Gaining ground through silica-sol primary coats over lower-cost backup layers |
Process choice is fundamentally a cost-versus-finish decision, and buyers increasingly specify shell chemistry explicitly rather than leaving it to the foundry. Hybrid systems are the pragmatic compromise, delivering acceptable surface quality at meaningfully lower shell cost than full silica-sol builds.
By Material
| Sub-Segment | Key Trend |
| Stainless Steel | Broadest application base spanning industrial, medical and consumer segments |
| Superalloys | Capacity-constrained growth tied to gas turbine and aero-engine build rates |
| Aluminium Alloys | Weight-reduction demand in aerostructures and thermal management housings |
| Titanium Alloys | Western vacuum-melt capacity remains the binding constraint on growth |
| Carbon and Low-Alloy Steel | Stable demand in heavy equipment and general engineering |
| Others | Cobalt-chrome implants and refractory alloys for extreme-temperature service |
Material mix determines margin far more than volume does. Suppliers moving up the alloy ladder from carbon steel toward superalloys and titanium typically double gross margin per kilogram, which explains the concentration of recent capital spending in vacuum melting and hot isostatic pressing.
By End-User
| Sub-Segment | Key Trend |
| Aerospace and Defense | Multi-year firm commitments replacing annual purchase orders |
| Energy and Power | Turbine retrofit and nuclear component demand accelerating |
| Automotive | Mix shifting toward hybrid and premium powertrain applications |
| Industrial Machinery | Steady replacement demand for pumps, valves and compressor parts |
| Medical | Implant volumes rising with ageing demographics and cleared backlogs |
| Others | Firearms, marine propulsion and food processing equipment |
End-use concentration in aerospace creates cyclical exposure that suppliers actively hedge by cultivating energy and medical accounts. The strongest performers through 2035 will be those balancing certification-heavy aerospace work with less volatile industrial and medical revenue streams.
By Pattern Technology
| Sub-Segment | Key Trend |
| Conventional Wax Patterns | Remains lowest cost per unit above a few hundred annual pieces |
| 3D-Printed and Rapid Prototype Patterns | Crossover volume threshold rising each year as resin chemistry improves |
Pattern shops are becoming dual-technology operations rather than choosing sides. The commercial advantage sits with foundries that can quote either route and select correctly at the estimating stage, since misjudging the crossover point costs either tooling capital or per-unit margin.
By Component Weight
| Sub-Segment | Key Trend |
| Up to 1 kg | Fastest growth in medical, instrumentation and small valve demand |
| 1–10 kg | Core commercial band covering most engine and machinery components |
| Above 10 kg | Limited supplier pool supports pricing on large structural work |
Weight class effectively defines which suppliers can bid at all, since furnace size, shell handling, and inspection infrastructure differ sharply across bands. Heavy-section capability remains a genuine moat, while sub-kilogram work has the lowest barriers and the most competitive pricing.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA