Investment Casting Market (2026 - 2035)

Investment Casting Market Research Report Information By Process Type (Silica-Sol, Water-Glass, and Hybrid and Other Processes), By Material (Stainless Steel, Superalloys, Aluminium Alloys, Titanium Alloys, Carbon and Low-Alloy Steel, and Others), By End-User (Aerospace and Defense, Energy and Power, Automotive, Industrial Machinery, Medical, and Others), By Pattern Technology (Conventional Wax Patterns and 3D-Printed and Rapid Prototype Patterns), and By Component Weight (Up to 1 kg, 1–10 kg, and Above 10 kg) – Forecast Till 2035.
ID: MRFR/CnM/7048-CR 157 Pages Chitranshi Jaiswal Last Updated: September 04, 2026
Investment Casting Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.60%
2025 Market SizeUSD 18.71 Billion
2035 Market SizeUSD 32.27 Billion
Key Players
Precision Castparts Corp.
Howmet Aerospace
Consolidated Precision Products
Doncasters Group
Impro Precision Industries
Signicast
Opportunities
  • Titanium and Vacuum-Melt Capacity Expansion
  • Digital Pattern and Tooling Workflows
  • Emerging-Market Qualification and Nearshoring

Investment Casting Market 概要

市場調査の未来の分析によると、投資鋳造市場の規模は2024年に201.4億米ドルと推定されました。投資鋳造業界は、2025年に213.5億米ドルから2035年までに382.3億米ドルに成長すると予測されており、2025年から2035年の予測期間中に年平均成長率(CAGR)は6.0%です。

主要な市場動向とハイライト

投資鋳造市場は、技術の進歩と持続可能性の取り組みによって成長する準備が整っています。

  • 北米は、堅調な航空宇宙および軍事用途によって、投資鋳造の最大市場であり続けています。
  • アジア太平洋地域は、自動車の革新と軽量材料の需要の増加により、最も成長が早い地域として浮上しています。
  • シリカソルプロセスが市場を支配しており、ナトリウムシリケートプロセスはコスト効率と効率性から注目を集めています。
  • 航空宇宙分野での需要の高まりと材料科学の進展が市場拡大を促進する主要な要因です。

市場規模と予測

2024年の市場規模 20.14(米ドル十億)
2035年の市場規模 38.23(米ドル十億)
CAGR(2025 - 2035) 6.0%

主要なプレーヤー

プレシジョン・キャストパーツ社(米国)、アルコア社(米国)、ティッセンクルップAG(ドイツ)、日立金属株式会社(日本)、メタルテクノロジーズ社(米国)、RLMインダストリーズ社(米国)、カストロール社(英国)、オーベール&デュバル社(フランス)、KSMキャスティングスグループ(ドイツ)

Investment Casting Market 運転手

Energy Sector Developments

The energy sector, particularly renewable energy, is driving growth in the investment casting market. As the world shifts towards sustainable energy sources, there is an increasing demand for components used in wind turbines and solar energy systems. Investment casting allows for the production of complex parts that are essential for the efficiency and reliability of these systems. In 2025, the energy sector is expected to represent a growing segment of the investment casting market, with projections indicating a rise in demand for high-performance materials. This trend is likely to be fueled by government initiatives aimed at promoting renewable energy, thereby creating opportunities for investment casting manufacturers to expand their offerings.

Healthcare Sector Expansion

Automotive Industry Innovations

Advancements in Material Science

Rising Demand in Aerospace Sector

地域の洞察

North America : Market Leader in Innovation

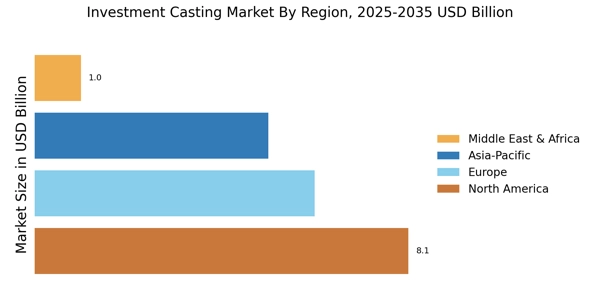
North America is the largest market for investment casting, holding approximately 40% of the global share. The region benefits from advanced manufacturing technologies, a strong aerospace and automotive sector, and increasing demand for precision components. Regulatory support for innovation and sustainability further drives growth, with initiatives aimed at enhancing production efficiency and reducing environmental impact. The United States is the primary contributor, with key players like Precision Castparts Corp and Alcoa Corporation leading the market. The competitive landscape is characterized by a focus on technological advancements and strategic partnerships. The presence of established companies fosters a robust ecosystem, ensuring continuous growth and innovation in investment casting processes.

Europe : Emerging Market with Potential

Europe is witnessing significant growth in the investment casting market, accounting for around 30% of the global share. The region's demand is driven by the automotive and aerospace industries, which are increasingly adopting lightweight materials and complex geometries. Regulatory frameworks promoting sustainability and energy efficiency are also pivotal in shaping market dynamics, encouraging investments in advanced casting technologies. Germany and France are the leading countries in this sector, with companies like Thyssenkrupp AG and Aubert & Duval playing crucial roles. The competitive landscape is marked by innovation and collaboration among manufacturers, focusing on high-quality products and customized solutions. The presence of major players enhances the region's capability to meet diverse industrial needs.

Asia-Pacific : Rapid Growth and Expansion

Asia-Pacific is rapidly emerging as a significant player in the investment casting market, holding approximately 25% of the global share. The region's growth is fueled by increasing industrialization, urbanization, and a rising demand for consumer goods. Countries like China and India are investing heavily in manufacturing capabilities, supported by government initiatives aimed at enhancing production efficiency and technological advancements. China is the largest market in the region, with a strong presence of key players such as Hitachi Metals Ltd. The competitive landscape is characterized by a mix of local and international companies, focusing on cost-effective solutions and innovation. The region's investment in infrastructure and technology is expected to further bolster its position in the global market.

Middle East and Africa : Emerging Opportunities Ahead

The Middle East and Africa region is gradually developing its investment casting market, currently holding about 5% of the global share. The growth is driven by increasing investments in infrastructure and manufacturing sectors, particularly in countries like the UAE and South Africa. Regulatory support for industrial development and foreign investments is fostering a conducive environment for market expansion. The competitive landscape is still evolving, with local players beginning to establish their presence. Companies are focusing on enhancing their capabilities to meet the growing demand for high-quality casting products. As the region continues to diversify its economy, the investment casting market is expected to gain momentum, attracting more players and investments.

Investment Casting Market Regional Image

主要企業と競争の洞察

The Investment Casting Market is currently characterized by a dynamic competitive landscape, driven by technological advancements and increasing demand across various sectors, including aerospace, automotive, and healthcare. Key players such as Precision Castparts Corp (US), Alcoa Corporation (US), and Thyssenkrupp AG (DE) are strategically positioning themselves through innovation and regional expansion. For instance, Precision Castparts Corp (US) has focused on enhancing its manufacturing capabilities to meet the growing demand for lightweight components, while Alcoa Corporation (US) emphasizes sustainability in its operations, aiming to reduce carbon emissions through advanced casting technologies. These strategies collectively shape a competitive environment that is increasingly focused on efficiency and environmental responsibility.
In terms of business tactics, companies are localizing manufacturing to reduce lead times and optimize supply chains. The Investment Casting Market appears moderately fragmented, with a mix of large corporations and smaller specialized firms. The collective influence of key players is significant, as they leverage their technological expertise and market reach to establish competitive advantages. This structure allows for a diverse range of offerings, catering to various customer needs while fostering innovation.
In August 2025, Thyssenkrupp AG (DE) announced a strategic partnership with a leading aerospace manufacturer to develop next-generation investment cast components. This collaboration is poised to enhance Thyssenkrupp's position in the aerospace sector, enabling the company to leverage advanced materials and manufacturing techniques. The strategic importance of this partnership lies in its potential to drive innovation and improve product performance, aligning with the industry's shift towards lightweight and high-strength materials.
In September 2025, Hitachi Metals Ltd (JP) unveiled a new investment casting facility in Japan, aimed at increasing production capacity for automotive components. This facility is expected to utilize cutting-edge technology to enhance efficiency and reduce production costs. The establishment of this facility underscores Hitachi Metals' commitment to meeting the rising demand in the automotive sector, particularly for electric vehicles, where lightweight components are crucial for performance and efficiency.
In October 2025, Alcoa Corporation (US) launched a new line of sustainable investment cast products, utilizing recycled materials in their production process. This initiative not only aligns with global sustainability trends but also positions Alcoa as a leader in environmentally friendly manufacturing practices. The strategic importance of this launch is multifaceted; it addresses consumer demand for sustainable products while potentially reducing production costs associated with raw material sourcing.
As of October 2025, current competitive trends in the Investment Casting Market are heavily influenced by digitalization, sustainability, and the integration of artificial intelligence. Companies are increasingly forming strategic alliances to enhance their technological capabilities and market reach. This shift indicates a movement away from traditional price-based competition towards a focus on innovation, technology, and supply chain reliability. Looking ahead, competitive differentiation is likely to evolve, with firms that prioritize sustainable practices and advanced technologies gaining a significant edge in the market.

Investment Casting Market市場の主要企業には以下が含まれます

Recent Industry Developments

プレスリリースによると、2022年10月、重要な金属部品の先進的な製造業者であるウィンセルトが、投資鋳造および機械加工会社であるアロイキャストプロダクツ社を買収しました。この動きは、両社がライフサイクルにおける新しい製品開発の分野にアクセスできるようになるため、利益をもたらすでしょう。

2022年8月、アメリティ製造は、デトロイト市場でチタン部品を立ち上げるためにトライテック・チタン・パーツを設立しました。トライテック・チタン・パーツは、金属射出成形、3Dバインダージェット印刷、投資鋳造などの先進的な方法を用いて高品質の製品を生産しています。これらのチタン部品は、さまざまな産業、航空宇宙、自動車、医療用途向けに設計されています。

2021年10月、アルコア社は、2050年までに全世界の事業でネットゼロ温室効果ガス(GHG)排出量を達成するというコミットメントを公表しました。これは、持続可能に成長するという会社のビジョンに沿ったものであり、2025年までにアルミニウム精錬およびボーキサイト精製業務から直接および間接のGHG排出量をそれぞれ30%および50%削減するという現在の目標に加えられます。

目標は、2050年までに、会社の戦略による直接(スコープ1)および間接(スコープ2)排出量を通じて、ネットGHG排出量をゼロに達成することです。

今後の見通し

Investment Casting Market 今後の見通し

投資鋳造市場は、2024年から2035年までの間に6.0%の年平均成長率で成長することが予測されており、技術の進歩、航空宇宙および自動車分野での需要の増加が推進要因です。

2035年までに、投資鋳造市場は堅調な成長を遂げ、主要な製造業セクターとしての地位を確立すると予想されています。

市場セグメンテーション

投資鋳造市場のタイプの見通し

  • シリカソルプロセス
  • 水ガラスプロセス

投資鋳造市場の用途の見通し

  • 航空宇宙および軍事
  • 一般産業
  • 産業用ガスタービン
  • 自動車
  • その他

レポートの範囲

Parameter Detail
Market Scope Global Investment Casting Market by process type, material, end-user, pattern technology, component weight and region
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.60% (2026–2035)
Market Size Checkpoints USD 18.71 Billion (2025); USD 19.76 Billion (2026); USD 25.95 Billion (2031); USD 32.27 Billion (2035)
Fastest Growing Segments Superalloys (material); Energy and Power (end-user); 3D-Printed and Rapid Prototype Patterns (pattern technology); North America (region)
Companies Profiled 10 major suppliers including Precision Castparts Corp., Howmet Aerospace, Consolidated Precision Products, Doncasters Group, Impro Precision Industries, Signicast, MetalTek International, Zollern, PTC Industries, Barron Industries
Valuation Currency USD Billion, constant 2025 prices

Frequently Asked Questions

2024年の投資鋳造市場の現在の評価額はどのくらいですか?

投資鋳造市場は2024年に201.4億米ドルと評価されました。

2035年の投資鋳造市場の予測評価額はどのくらいですか?

市場は2035年までに382.3億米ドルに達すると予測されています。

2025年から2035年の予測期間中の投資鋳造市場の期待CAGRはどのくらいですか?

2025年から2035年の予測期間中の投資鋳造市場の期待CAGRは6.0%です。

投資鋳造市場にはどのようなタイプのセグメントが含まれていますか?

投資鋳造市場には、シリカソルプロセスや水ガラスプロセスなどのセグメントが含まれています。

2035年までのシリカソルプロセスと水ガラスプロセスの予測評価額はどのくらいですか?

シリカソルプロセスは191.2億米ドルに達すると予測されており、水ガラスプロセスは2035年までに191.1億米ドルに達すると期待されています。

投資鋳造市場の成長を促進しているアプリケーションは何ですか?

主要なアプリケーションには、航空宇宙および軍事、一般産業、産業用ガスタービン、自動車が含まれます。

2035年までの自動車アプリケーションセグメントの予測評価額はどのくらいですか?

自動車アプリケーションセグメントは2035年までに150.0億米ドルに達すると予測されています。

投資鋳造市場の主要なプレーヤーは誰ですか?

主要なプレーヤーには、プレシジョンキャストパーツ社、アルコア社、ティッセンクルップ社、日立金属株式会社が含まれます。

2035年までの一般産業アプリケーションセグメントの予測成長はどのくらいですか?

一般産業アプリケーションセグメントは2035年までに70.0億米ドルに成長すると予測されています。

投資鋳造市場の成長は異なるアプリケーション間でどのように比較されますか?

自動車セグメントは最も高い成長の可能性を示しており、航空宇宙および軍事は2035年までに55.0億米ドルと予測されています。

著者
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry standards repositories, peer-reviewed metallurgical journals, technical publications, and authoritative manufacturing organizations. Key sources included the U.S. Department of Commerce (DOC), Bureau of Industry and Security (BIS), International Trade Administration (ITA), U.S. Geological Survey (USGS), Federal Aviation Administration (FAA), European Aviation Safety Agency (EASA), U.S. Department of Defense (DoD) procurement databases, NATO Support and Procurement Agency (NSPA), American Foundry Society (AFS), European Foundry Association (CAEF), China Foundry Association (CFA), Investment Casting Institute (ICI), Metal Casting Design & Purchasing, ASM International (Materials Information Society), The Minerals, Metals & Materials Society (TMS), SAE International, Association des Industries de Fonderie (AIFF), Japan Foundry Engineering Society (JFS), Bureau of Labor Statistics (BLS), Eurostat Industrial Production Database, OECD Steel and Non-Ferrous Metals Indicators, and national manufacturing statistics from key markets including NBS China and Make in India initiative reports. These sources were utilized to collect foundry production statistics, aerospace & defense procurement data, material pricing trends (titanium, nickel superalloys, aluminum), regulatory compliance data (AS9100, NADCAP), capacity utilization rates, and technological landscape analysis for silica sol processing, sodium silicate processing, and emerging additive manufacturing hybrid techniques.


Primary Research

As part of the initial research process, stakeholders from both the supply and demand sides were interviewed to get both qualitative and quantitative information. CEOs, Presidents, VPs of Manufacturing, plant managers, top metallurgists, R&D heads, and sales directors from investment casting foundries, precision casting OEMs, and raw material suppliers (specialty alloy producers) were some of the people who were on the supply side. Demand-side sources included purchasing managers from aerospace OEMs (airframers and engine manufacturers), military and defense contractors, powertrain engineers for cars, makers of industrial gas turbines, and supply chain managers from tier-1 aviation suppliers. Primary research confirmed process-specific market segmentation (silica sol vs. sodium silicate), confirmed facility expansion and capacity addition timelines, and gathered information on how complex superalloy castings are adopted, how prices for raw materials and finished parts change over time, and the rules for qualifying new casting facilities.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Value Chain Position: Investment Casting Foundries (45%), End-Use OEMs (30%), Raw Material/Equipment Suppliers (15%), Industry Consultants/Associations (10%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)

By Process Type: Silica Sol Process Specialists (55%), Sodium Silicate Process Specialists (35%), Both/Mixed Process Operators (10%)

By End-Use Segment: Aerospace & Military (40%), Automotive (25%), Industrial Gas Turbines (20%), General Industrial/Medical/Others (15%)
 

Market Size Estimation

Global market valuation was derived through production volume mapping and revenue analysis across casting processes. The methodology included:

Identification of 60+ key foundry groups and precision casting manufacturers across North America, Europe, Asia-Pacific, and Latin America

Process mapping across silica sol (lost-wax precision) casting, sodium silicate (water glass) casting, and specialized vacuum-assisted/centrifugal investment casting technologies

Material segmentation analysis covering nickel-based superalloys, titanium alloys, aluminum alloys, and stainless/carbon steels

Analysis of reported and modeled annual revenues specific to investment casting divisions/facilities, derived from primary interviews, company financial reports, and foundry capacity databases

Coverage of foundries representing 75-80% of global market share in terms of production tonnage and revenue in 2024

Extrapolation using bottom-up (casting volume × average selling price by alloy type × geographical cost factors) and top-down (foundry revenue validation against end-use industry procurement data) approaches to derive segment-specific valuations by process type, application vertical, and regional markets

Capacity utilization analysis incorporating data from regional foundry associations and industrial energy consumption metrics to validate production volume estimates

Cross-verification with aerospace & defense procurement databases to confirm high-value superalloy casting volumes in aviation and military applications

This methodology ensured comprehensive coverage of the investment casting value chain, from wax pattern production and ceramic shell manufacturing to final casting finishing and non-destructive testing (NDT) qualification, providing validated market sizing across all identified process technologies and end-use sectors.

無料サンプルをダウンロード

このレポートの無料サンプルを受け取るには、以下のフォームにご記入ください

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.