Investment Casting Market (2026 - 2035)

Investment Casting Market Research Report Information By Process Type (Silica-Sol, Water-Glass, and Hybrid and Other Processes), By Material (Stainless Steel, Superalloys, Aluminium Alloys, Titanium Alloys, Carbon and Low-Alloy Steel, and Others), By End-User (Aerospace and Defense, Energy and Power, Automotive, Industrial Machinery, Medical, and Others), By Pattern Technology (Conventional Wax Patterns and 3D-Printed and Rapid Prototype Patterns), and By Component Weight (Up to 1 kg, 1–10 kg, and Above 10 kg) – Forecast Till 2035.
ID: MRFR/CnM/7048-CR
157 Pages
Chitranshi Jaiswal
Last Updated: September 04, 2026
Investment Casting Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.60%
2025 Market SizeUSD 18.71 Billion
2035 Market SizeUSD 32.27 Billion
Key Players
Precision Castparts Corp.
Howmet Aerospace
Consolidated Precision Products
Doncasters Group
Impro Precision Industries
Signicast
Opportunities
  • Titanium and Vacuum-Melt Capacity Expansion
  • Digital Pattern and Tooling Workflows
  • Emerging-Market Qualification and Nearshoring

Investment Casting Market 요약

시장 조사 미래 분석에 따르면, 투자 주조 시장 규모는 2024년에 201억 4천만 달러로 추정되었습니다. 투자 주조 산업은 2025년 213억 5천만 달러에서 2035년까지 382억 3천만 달러로 성장할 것으로 예상되며, 2025 - 2035년 예측 기간 동안 연평균 성장률(CAGR)은 6.0%에 이를 것으로 보입니다.

주요 시장 동향 및 하이라이트

투자 주조 시장은 기술 발전과 지속 가능성 이니셔티브에 의해 성장할 준비가 되어 있습니다.

  • 북미는 강력한 항공 우주 및 군사 응용 프로그램에 의해 추진되어 투자 주조의 가장 큰 시장으로 남아 있습니다.
  • 아시아 태평양은 자동차 혁신 증가와 경량 소재에 대한 수요로 인해 가장 빠르게 성장하는 지역으로 부상하고 있습니다.
  • 실리카 솔 공정이 시장을 지배하고 있으며, 나트륨 실리케이트 공정은 비용 효율성과 효율성 덕분에 주목받고 있습니다.
  • 항공 우주 부문에서의 수요 증가와 재료 과학의 발전이 시장 확장을 촉진하는 주요 요인입니다.

시장 규모 및 예측

2024 시장 규모 201.4억 달러
2035 시장 규모 382.3억 달러
CAGR (2025 - 2035) 6.0%

주요 기업

프리시전 캐스트파트 Corp (미국), 알코아 코퍼레이션 (미국), 티센크루프 AG (독일), 히타치 메탈즈 Ltd (일본), 메탈 테크놀로지스 Inc (미국), RLM 산업 Inc (미국), 캐스트롤 리미티드 (영국), 오베르 & 듀발 (프랑스), KSM 캐스팅스 그룹 (독일)

Investment Casting Market Treiber

Energy Sector Developments

The energy sector, particularly renewable energy, is driving growth in the investment casting market. As the world shifts towards sustainable energy sources, there is an increasing demand for components used in wind turbines and solar energy systems. Investment casting allows for the production of complex parts that are essential for the efficiency and reliability of these systems. In 2025, the energy sector is expected to represent a growing segment of the investment casting market, with projections indicating a rise in demand for high-performance materials. This trend is likely to be fueled by government initiatives aimed at promoting renewable energy, thereby creating opportunities for investment casting manufacturers to expand their offerings.

Healthcare Sector Expansion

Automotive Industry Innovations

Advancements in Material Science

Rising Demand in Aerospace Sector

시장 세그먼트 통찰력

Investment Casting Market에 대한 더 자세한 통찰력 얻기

지역 통찰력

North America : Market Leader in Innovation

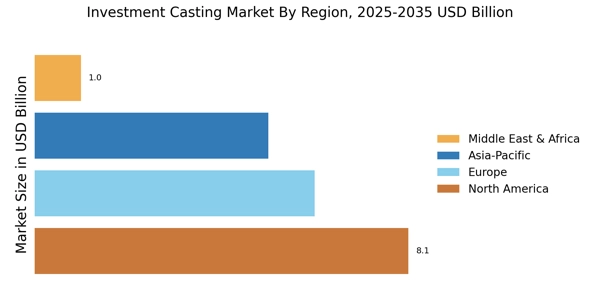
North America is the largest market for investment casting, holding approximately 40% of the global share. The region benefits from advanced manufacturing technologies, a strong aerospace and automotive sector, and increasing demand for precision components. Regulatory support for innovation and sustainability further drives growth, with initiatives aimed at enhancing production efficiency and reducing environmental impact. The United States is the primary contributor, with key players like Precision Castparts Corp and Alcoa Corporation leading the market. The competitive landscape is characterized by a focus on technological advancements and strategic partnerships. The presence of established companies fosters a robust ecosystem, ensuring continuous growth and innovation in investment casting processes.

Europe : Emerging Market with Potential

Europe is witnessing significant growth in the investment casting market, accounting for around 30% of the global share. The region's demand is driven by the automotive and aerospace industries, which are increasingly adopting lightweight materials and complex geometries. Regulatory frameworks promoting sustainability and energy efficiency are also pivotal in shaping market dynamics, encouraging investments in advanced casting technologies. Germany and France are the leading countries in this sector, with companies like Thyssenkrupp AG and Aubert & Duval playing crucial roles. The competitive landscape is marked by innovation and collaboration among manufacturers, focusing on high-quality products and customized solutions. The presence of major players enhances the region's capability to meet diverse industrial needs.

Asia-Pacific : Rapid Growth and Expansion

Asia-Pacific is rapidly emerging as a significant player in the investment casting market, holding approximately 25% of the global share. The region's growth is fueled by increasing industrialization, urbanization, and a rising demand for consumer goods. Countries like China and India are investing heavily in manufacturing capabilities, supported by government initiatives aimed at enhancing production efficiency and technological advancements. China is the largest market in the region, with a strong presence of key players such as Hitachi Metals Ltd. The competitive landscape is characterized by a mix of local and international companies, focusing on cost-effective solutions and innovation. The region's investment in infrastructure and technology is expected to further bolster its position in the global market.

Middle East and Africa : Emerging Opportunities Ahead

The Middle East and Africa region is gradually developing its investment casting market, currently holding about 5% of the global share. The growth is driven by increasing investments in infrastructure and manufacturing sectors, particularly in countries like the UAE and South Africa. Regulatory support for industrial development and foreign investments is fostering a conducive environment for market expansion. The competitive landscape is still evolving, with local players beginning to establish their presence. Companies are focusing on enhancing their capabilities to meet the growing demand for high-quality casting products. As the region continues to diversify its economy, the investment casting market is expected to gain momentum, attracting more players and investments.

Investment Casting Market Regional Image

주요 기업 및 경쟁 통찰력

The Investment Casting Market is currently characterized by a dynamic competitive landscape, driven by technological advancements and increasing demand across various sectors, including aerospace, automotive, and healthcare. Key players such as Precision Castparts Corp (US), Alcoa Corporation (US), and Thyssenkrupp AG (DE) are strategically positioning themselves through innovation and regional expansion. For instance, Precision Castparts Corp (US) has focused on enhancing its manufacturing capabilities to meet the growing demand for lightweight components, while Alcoa Corporation (US) emphasizes sustainability in its operations, aiming to reduce carbon emissions through advanced casting technologies. These strategies collectively shape a competitive environment that is increasingly focused on efficiency and environmental responsibility.
In terms of business tactics, companies are localizing manufacturing to reduce lead times and optimize supply chains. The Investment Casting Market appears moderately fragmented, with a mix of large corporations and smaller specialized firms. The collective influence of key players is significant, as they leverage their technological expertise and market reach to establish competitive advantages. This structure allows for a diverse range of offerings, catering to various customer needs while fostering innovation.
In August 2025, Thyssenkrupp AG (DE) announced a strategic partnership with a leading aerospace manufacturer to develop next-generation investment cast components. This collaboration is poised to enhance Thyssenkrupp's position in the aerospace sector, enabling the company to leverage advanced materials and manufacturing techniques. The strategic importance of this partnership lies in its potential to drive innovation and improve product performance, aligning with the industry's shift towards lightweight and high-strength materials.
In September 2025, Hitachi Metals Ltd (JP) unveiled a new investment casting facility in Japan, aimed at increasing production capacity for automotive components. This facility is expected to utilize cutting-edge technology to enhance efficiency and reduce production costs. The establishment of this facility underscores Hitachi Metals' commitment to meeting the rising demand in the automotive sector, particularly for electric vehicles, where lightweight components are crucial for performance and efficiency.
In October 2025, Alcoa Corporation (US) launched a new line of sustainable investment cast products, utilizing recycled materials in their production process. This initiative not only aligns with global sustainability trends but also positions Alcoa as a leader in environmentally friendly manufacturing practices. The strategic importance of this launch is multifaceted; it addresses consumer demand for sustainable products while potentially reducing production costs associated with raw material sourcing.
As of October 2025, current competitive trends in the Investment Casting Market are heavily influenced by digitalization, sustainability, and the integration of artificial intelligence. Companies are increasingly forming strategic alliances to enhance their technological capabilities and market reach. This shift indicates a movement away from traditional price-based competition towards a focus on innovation, technology, and supply chain reliability. Looking ahead, competitive differentiation is likely to evolve, with firms that prioritize sustainable practices and advanced technologies gaining a significant edge in the market.

Investment Casting Market 시장의 주요 기업은 다음과 같습니다

산업 발전

보도 자료에 따르면, 2022년 10월, 중요한 금속 부품의 고급 제조업체인 Winsert가 투자 주조 및 가공 회사인 Alloy Cast Products Inc.를 인수했습니다. 이는 두 회사가 제품 개발의 새로운 영역을 탐색할 수 있게 해줄 것입니다.

2022년 8월, AmeriTi Manufacturing은 디트로이트 시장에 티타늄 부품을 출시하기 위해 TriTech Titanium Parts를 설립했습니다. TriTech Titanium Parts는 금속 주입, 3D 바인더 제트 프린팅 및 투자 주조를 포함한 고급 방법으로 고품질 제품을 생산합니다. 이러한 티타늄 부품은 다양한 산업, 항공우주, 자동차 및 의료 응용 분야를 위해 설계되었습니다.

2021년 10월, 알코아 코퍼레이션은 전 세계 모든 운영에서 2050년까지 온실가스(GHG) 배출량을 순제로로 달성하겠다는 약속을 공개했습니다. 이는 지속 가능한 성장을 위한 회사의 비전과 일치하며, 2025년까지 알루미늄 제련 및 알루미나 정제 작업에서 직접 및 간접 GHG 배출량을 각각 30% 및 50% 줄이는 현재 목표를 추가한 것입니다.

목표는 회사의 전략에 따라 직접(범위 1) 및 간접(범위 2) 배출량을 통해 2050년까지 순 GHG 배출량을 제로로 달성하는 것입니다.

향후 전망

Investment Casting Market 향후 전망

투자 주조 시장은 2024년부터 2035년까지 6.0%의 CAGR로 성장할 것으로 예상되며, 기술 발전과 항공 우주 및 자동차 부문에서의 수요 증가에 의해 추진됩니다.

2035년까지 투자 주조 시장은 강력한 성장을 달성할 것으로 예상되며, 주요 제조 부문으로서의 입지를 확고히 할 것입니다.

시장 세분화

투자 주조 시장 유형 전망

  • 실리카 솔 공정
  • 수산화 나트륨 공정

투자 주조 시장 응용 전망

  • 항공 우주 및 군사
  • 일반 산업
  • 산업용 가스 터빈
  • 자동차
  • 기타

보고서 범위

Parameter Detail
Market Scope Global Investment Casting Market by process type, material, end-user, pattern technology, component weight and region
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.60% (2026–2035)
Market Size Checkpoints USD 18.71 Billion (2025); USD 19.76 Billion (2026); USD 25.95 Billion (2031); USD 32.27 Billion (2035)
Fastest Growing Segments Superalloys (material); Energy and Power (end-user); 3D-Printed and Rapid Prototype Patterns (pattern technology); North America (region)
Companies Profiled 10 major suppliers including Precision Castparts Corp., Howmet Aerospace, Consolidated Precision Products, Doncasters Group, Impro Precision Industries, Signicast, MetalTek International, Zollern, PTC Industries, Barron Industries
Valuation Currency USD Billion, constant 2025 prices

FAQs

2024년 투자 주조 시장의 현재 가치는 얼마입니까?

투자 주조 시장은 2024년에 201.4억 달러로 평가되었습니다.

2035년 투자 주조 시장의 예상 시장 가치는 얼마입니까?

시장은 2035년까지 382.3억 달러의 가치를 달성할 것으로 예상됩니다.

2025년부터 2035년까지의 투자 주조 시장의 예상 CAGR은 얼마입니까?

2025년부터 2035년까지의 투자 주조 시장의 예상 CAGR은 6.0%입니다.

투자 주조 시장에 포함된 유형별 세그먼트는 무엇입니까?

투자 주조 시장에는 실리카 솔 공정 및 나트륨 실리케이트 공정과 같은 세그먼트가 포함됩니다.

2035년까지 실리카 솔 공정과 나트륨 실리케이트 공정의 예상 가치는 얼마입니까?

실리카 솔 공정은 191.2억 달러에 이를 것으로 예상되며, 나트륨 실리케이트 공정은 191.1억 달러에 이를 것으로 예상됩니다.

투자 주조 시장의 성장을 이끄는 응용 프로그램은 무엇입니까?

주요 응용 프로그램에는 항공우주 및 군사, 일반 산업, 산업 가스터빈 및 자동차가 포함됩니다.

2035년까지 자동차 응용 프로그램 세그먼트의 예상 가치는 얼마입니까?

자동차 응용 프로그램 세그먼트는 2035년까지 150억 달러에 이를 것으로 예상됩니다.

투자 주조 시장의 주요 업체는 누구입니까?

주요 업체에는 프리시전 캐스트파트 Corp, 알코아 코퍼레이션, 티센크루프 AG 및 히타치 메탈즈 Ltd.가 포함됩니다.

2035년까지 일반 산업 응용 프로그램 세그먼트의 예상 성장은 얼마입니까?

일반 산업 응용 프로그램 세그먼트는 2035년까지 70억 달러로 성장할 것으로 예상됩니다.

투자 주조 시장의 성장은 다양한 응용 프로그램 간에 어떻게 비교됩니까?

자동차 세그먼트는 가장 높은 성장 잠재력을 보이며, 항공우주 및 군사는 2035년까지 55억 달러로 예상됩니다.

저자
Author
Author Profile
Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry standards repositories, peer-reviewed metallurgical journals, technical publications, and authoritative manufacturing organizations. Key sources included the U.S. Department of Commerce (DOC), Bureau of Industry and Security (BIS), International Trade Administration (ITA), U.S. Geological Survey (USGS), Federal Aviation Administration (FAA), European Aviation Safety Agency (EASA), U.S. Department of Defense (DoD) procurement databases, NATO Support and Procurement Agency (NSPA), American Foundry Society (AFS), European Foundry Association (CAEF), China Foundry Association (CFA), Investment Casting Institute (ICI), Metal Casting Design & Purchasing, ASM International (Materials Information Society), The Minerals, Metals & Materials Society (TMS), SAE International, Association des Industries de Fonderie (AIFF), Japan Foundry Engineering Society (JFS), Bureau of Labor Statistics (BLS), Eurostat Industrial Production Database, OECD Steel and Non-Ferrous Metals Indicators, and national manufacturing statistics from key markets including NBS China and Make in India initiative reports. These sources were utilized to collect foundry production statistics, aerospace & defense procurement data, material pricing trends (titanium, nickel superalloys, aluminum), regulatory compliance data (AS9100, NADCAP), capacity utilization rates, and technological landscape analysis for silica sol processing, sodium silicate processing, and emerging additive manufacturing hybrid techniques.


Primary Research

As part of the initial research process, stakeholders from both the supply and demand sides were interviewed to get both qualitative and quantitative information. CEOs, Presidents, VPs of Manufacturing, plant managers, top metallurgists, R&D heads, and sales directors from investment casting foundries, precision casting OEMs, and raw material suppliers (specialty alloy producers) were some of the people who were on the supply side. Demand-side sources included purchasing managers from aerospace OEMs (airframers and engine manufacturers), military and defense contractors, powertrain engineers for cars, makers of industrial gas turbines, and supply chain managers from tier-1 aviation suppliers. Primary research confirmed process-specific market segmentation (silica sol vs. sodium silicate), confirmed facility expansion and capacity addition timelines, and gathered information on how complex superalloy castings are adopted, how prices for raw materials and finished parts change over time, and the rules for qualifying new casting facilities.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Value Chain Position: Investment Casting Foundries (45%), End-Use OEMs (30%), Raw Material/Equipment Suppliers (15%), Industry Consultants/Associations (10%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)

By Process Type: Silica Sol Process Specialists (55%), Sodium Silicate Process Specialists (35%), Both/Mixed Process Operators (10%)

By End-Use Segment: Aerospace & Military (40%), Automotive (25%), Industrial Gas Turbines (20%), General Industrial/Medical/Others (15%)
 

Market Size Estimation

Global market valuation was derived through production volume mapping and revenue analysis across casting processes. The methodology included:

Identification of 60+ key foundry groups and precision casting manufacturers across North America, Europe, Asia-Pacific, and Latin America

Process mapping across silica sol (lost-wax precision) casting, sodium silicate (water glass) casting, and specialized vacuum-assisted/centrifugal investment casting technologies

Material segmentation analysis covering nickel-based superalloys, titanium alloys, aluminum alloys, and stainless/carbon steels

Analysis of reported and modeled annual revenues specific to investment casting divisions/facilities, derived from primary interviews, company financial reports, and foundry capacity databases

Coverage of foundries representing 75-80% of global market share in terms of production tonnage and revenue in 2024

Extrapolation using bottom-up (casting volume × average selling price by alloy type × geographical cost factors) and top-down (foundry revenue validation against end-use industry procurement data) approaches to derive segment-specific valuations by process type, application vertical, and regional markets

Capacity utilization analysis incorporating data from regional foundry associations and industrial energy consumption metrics to validate production volume estimates

Cross-verification with aerospace & defense procurement databases to confirm high-value superalloy casting volumes in aviation and military applications

This methodology ensured comprehensive coverage of the investment casting value chain, from wax pattern production and ceramic shell manufacturing to final casting finishing and non-destructive testing (NDT) qualification, providing validated market sizing across all identified process technologies and end-use sectors.

무료 샘플 다운로드

이 보고서의 무료 샘플을 받으려면 아래 양식을 작성하십시오

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.