High Density Packaging Market (2026 – 2035)

High Density Packaging Market Size, Share and Research Report By Packaging Technique (MCM, MCP, SIP, and 3D-TSV), By Application (Consumer Electronics, Aerospace & Defence, Medical Devices, IT & Telecom, Automotive, and Other Applications) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035
ID: MRFR/SEM/40977-HCR 128 Pages Nirmit Biswas, Garvit Vyas Last Updated: October 06, 2026
High Density Packaging Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.2%
2025 Market SizeUSD 42.60 Billion
2035 Market SizeUSD 123.14 Billion
Key Players
ASE Technology Holding
Amkor Technology
Samsung Electronics
JCET Group
Intel Corporation
Powertech Technology
Opportunities
  • Chiplet Ecosystems and Open Die-to-Die Standards
  • India and Southeast Asia Back-End Build-Out
  • Glass Substrates and Panel-Level Packaging

High Density Packaging Market Summary

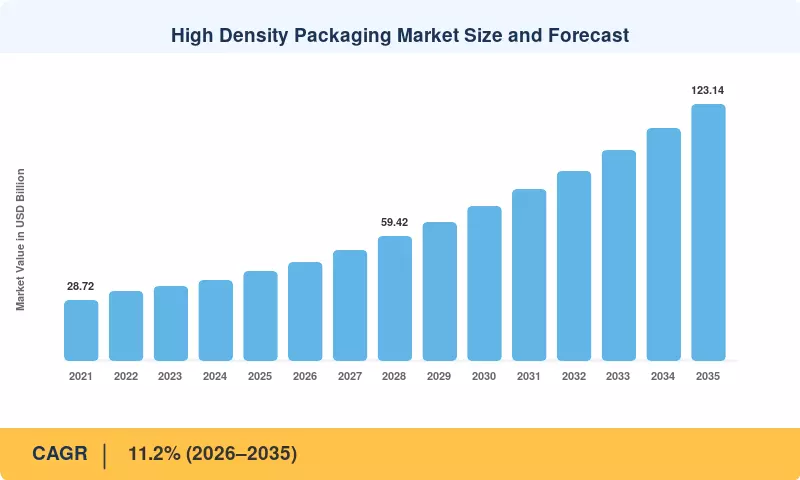
The High Density Packaging Market reached USD 42.60 billion in 2025. It is projected to grow from USD 47.37 billion in 2026 to USD 123.14 billion by 2035, a CAGR of 11.2% over 2026–2035. Two catalysts anchor this outlook. The US CHIPS and Science Act set aside roughly USD 3 billion for the National Advanced Packaging Manufacturing Program [1]. TSMC also expanded CoWoS capacity aggressively through 2024 and 2025, which shows how quickly AI accelerator demand is pulling packaging investment forward [7].

Packaging is no longer the low-value back end of chipmaking. Wire-bonded single-die packages and conventional flip-chip on organic laminate are giving way to multi-chip modules, SIP architectures and through-silicon-via stacks. These formats place logic, memory and passives within millimetres of each other. Interconnect density now sets the performance ceiling for AI and mobile silicon as much as transistor shrink does. That shift is one reason the European Chips Act mobilises more than EUR 43 billion, with packaging pilot lines in scope [2].

North America leads with a 36.4% share in 2025, supported by hyperscaler demand and new domestic packaging plants. Asia-Pacific is the second-largest region and home to most outsourced assembly and test capacity. It is also the fastest-growing, at a 13.1% CAGR. Europe follows on the strength of automotive and industrial electronics demand. Over the next decade, the High Density Packaging Market will be shaped less by unit volumes than by how many dies, and how much bandwidth, fit into each package.

Key Report Takeaways

• By Packaging Technique

  • SIP holds a 34.6% share of the High Density Packaging Market in 2025, led by smartphone, wearable and RF front-end modules
  • 3D - TSV is the fastest-growing technique, at a 14.9% CAGR through 2035, on the back of high-bandwidth memory stacking

• By Application

  • Consumer Electronics accounts for a 38.2% share of 2025 revenue, anchored by flagship handsets and wearables.
  • Automotive expands at a 14.2% CAGR as zonal architectures and ADAS processors move to multi-die packages.

• By Region

  • North America leads the High Density Packaging Market with a 36.4% share in 2025
  • Asia-Pacific grows fastest, at a 13.1% CAGR, on OSAT expansion in China, India and ASEAN

Market Size and Forecast (2021–2035)

Market Research Future built its estimates for the High Density Packaging Market bottom-up. The starting point was shipment volumes and average selling prices across the MCM, MCP, SIP and 3D - TSV formats. Those figures were then reconciled top-down against company filings, WSTS semiconductor revenue data and SEMI capacity trackers [3][4][5]. Historical values for 2021–2024 reflect reported packaging revenue from OSATs and integrated device makers. Forecasts apply application-level demand models to the 2025 base.
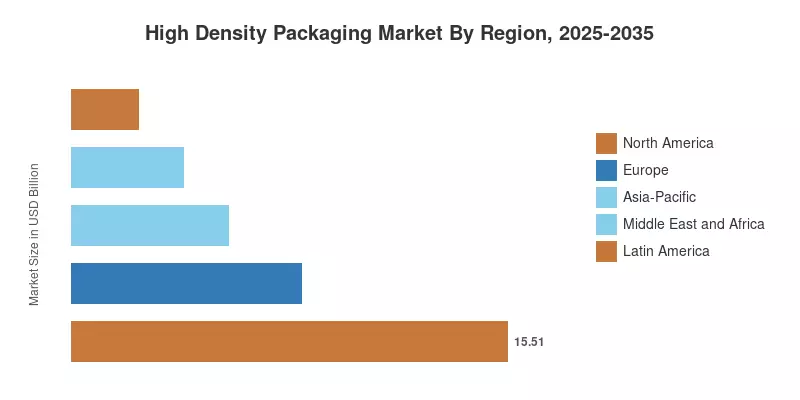
High Density Packaging Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

The impact percentages below show the direction and relative weight of each driver in the High Density Packaging Market. They are not additive. Drivers overlap, interact and partly offset the restraints listed in Section 5, so their sum does not reconstruct the headline CAGR.

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
AI and high-performance computing accelerators +2.8% North America, Asia-Pacific Medium term (2–4 yr)
Smartphone and wearable miniaturization +2.1% Asia-Pacific, North America Short term (≤2 yr)
Government packaging incentives +1.9% North America, Europe, Asia-Pacific Long term (≥4 yr)
Vehicle electrification and ADAS +1.6% Global Long term (≥4 yr)
IoT device proliferation +1.2% Global Medium term (2–4 yr)
5G infrastructure and RF module density +1.0% Asia-Pacific, Europe Short term (≤2 yr)


AI and High-Performance Computing Accelerators

Every leading AI accelerator now ships as a multi-die package, typically a logic die paired with six to eight HBM stacks on a silicon interposer. TSMC reported that CoWoS capacity stayed tight through 2024 despite a sharp expansion [7]. The IEA estimates that data-centre electricity use reached about 415 TWh in 2024 and could more than double by 2030 [16]. That compute build-out turns directly into demand for interposers, TSVs and substrates, which makes AI the largest single growth contributor.

Smartphone and Wearable Miniaturization

Data show global smartphone shipments recovering to roughly 1.24 billion units in 2024 . Flagship handsets now integrate RF front ends, power management and sensors as SIP modules, which frees board area for larger batteries. Smartwatches and earbuds depend on dense module packaging to fit inside a few cubic centimetres. Short product cycles keep replacement demand steady, so this driver acts within two years.

Government Packaging Incentives

Policy support has moved from front-end fabs toward back-end capacity. The US CHIPS Act allocated USD 52.7 billion in total, including about USD 3 billion for the National Advanced Packaging Manufacturing Program [1]. India's Semiconductor Mission carries a ₹76,000 crore outlay and has already approved several assembly and test plants [13]. The European Chips Act targets EUR 43 billion in combined public and private investment [2]. Because new plants take years to build, most of this impact lands after 2028.

Vehicle Electrification and ADAS

According to the IEA, electric car sales reached about 17 million units in 2024, more than one in five new cars sold worldwide [15]. A battery-electric vehicle carries far more semiconductor content than a combustion model. Centralised ADAS compute increasingly relies on multi-chip modules that must meet automotive reliability grades. As zonal architectures replace dozens of discrete ECUs, packaging density per vehicle rises steadily into the 2030s.

IoT Device Proliferation

IoT Analytics counted about 18.8 billion connected IoT devices at the end of 2024 and expects that base to keep growing through 2030 [18]. Industrial sensors, smart meters and asset trackers need the radio, microcontroller and power stages combined in packages only a few millimetres square. Compact MCP and SIP formats meet that requirement at a price that works for high-volume, low-margin endpoints. That gives this driver broad global relevance.

5G Infrastructure and RF Module Density

Ericsson projected that global 5G subscriptions would pass 2.3 billion by the end of 2024 [19]. Massive MIMO radios and millimetre-wave handsets need antenna-in-package designs and multi-die RF modules that keep signal paths short and losses low. Base-station rollouts in China, India and Europe are front-loaded. The impact is therefore concentrated in the near term before shifting to 5G-Advanced upgrades.

Restraints Impact Analysis

The negative percentages below show how strongly each restraint holds back the High Density Packaging Market. Like the driver figures, they are directional rather than additive. Some restraints, such as substrate shortages, ease over time as new capacity comes online.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High capital intensity of packaging lines −1.4% Global Long term (≥4 yr)
Export controls and geopolitical fragmentation −1.1% China, North America Medium term (2–4 yr)
Thermal and yield challenges in 3D stacking −0.9% Global Medium term (2–4 yr)
Substrate and materials supply constraints −0.8% Asia-Pacific Short term (≤2 yr)
Skilled workforce shortages −0.6% North America, Europe Long term (≥4 yr)


High Capital Intensity of Packaging Lines

A single advanced packaging campus can cost several billion dollars. Amkor's Arizona project was initially budgeted at about USD 2 billion [9]. TSMC guided that around 10% of its USD 38–42 billion capital budget for 2025 would go to advanced packaging, testing, masks and related items [7]. Smaller OSATs cannot match that level of spending, which slows their move into TSV and interposer work.

Export Controls and Geopolitical Fragmentation

The US Bureau of Industry and Security tightened controls on advanced computing items in October 2022 and October 2023. In December 2024, it extended them to high-bandwidth memory [20]. These rules limit which packaged products can reach Chinese buyers and which tools Chinese OSATs can import. The result is duplicated supply chains and some stranded capacity.

Thermal and Yield Challenges in 3D Stacking

Stacking dies increases heat density and worsens yield loss because one bad die might take out a full stack. Twelve- and sixteen-high HBM stacks stretch thermal budgets to the edge. Hybrid bonding also requires particle-free surfaces and sub-micron alignment [12]. Yield learning adds expense and delays qualification notably for 3D - TSV programs.


Substrate and Materials Supply Constraints

A small number of Japanese and Taiwanese companies supply high-layer-count organic substrates and Ajinomoto Build-up Film. In the 2021-2022 shortage, substrate lead times were more than 40 weeks [10]. Big AI packages require several times the substrate footprint of a traditional CPU, so supply tightens again as demand surges.


Skilled Workforce Shortages

A 2023 study by the Semiconductor Industry Association projected a shortfall of about 67,000 US semiconductor workers by 2030 [21]. Packaging engineers with thermal design, bonding and failure-analysis expertise are especially scarce outside Asia. That scarcity lengthens ramp times for new Western facilities.

High Density Packaging Market Opportunities

Chiplet Ecosystems and Open Die-to-Die Standards

The UCIe consortium's 2.0 specification, released in 2024, standardises die-to-die links so designers can combine dies from different vendors [11]. That opens the High Density Packaging Market to OSATs offering interposer, bridge and test services for mixed-vendor chiplets. Previously, this work was largely captive to integrated device makers and leading foundries.

India and Southeast Asia Back-End Build-Out

The most obvious geographic disparity is emerging markets. Micron’s USD 2.75 billion Sanand assembly and test plant includes government backing; India approved Tata’s Assam facility; CG Power–Renesas OSAT [13]; Malaysia is responsible for around 13% of the world’s assembly, packaging and test and its 2024 National Semiconductor Strategy is aimed toward higher value advanced packaging [14]. Suppliers of equipment, materials and packaging services can take early positions to gain first-wave share in the High Density Packaging Market.


Glass Substrates and Panel-Level Packaging

Intel announced in September 2023 that it plans to introduce glass core substrates later this decade, citing better flatness and finer interconnect pitch [22]. Panel-level formats raise area utilisation compared with round wafers. Together, these shifts open a new materials and equipment opportunity for suppliers able to qualify large-format processes.

Yield Data Monetization and Packaging-as-a-Service

Packaging houses generate a lot of data concerning testing, inspection and reliability. Selling yield analytics, digital-twin process models and design-enablement kits generates recurrent revenue in addition to per-unit assembly fees. The most responsive purchasers of these new business models are fabless start-ups building their initial chiplet devices and lacking in-house packaging teams.


Medical Implantables and Wearable Diagnostics

The WHO projects that nearly 2.5 billion people will live with some degree of hearing loss by 2050 [23]. Hearing aids, continuous glucose monitors and implantable neurostimulators need biocompatible, ultra-compact packages built under ISO 13485 quality systems. Volumes are smaller than in consumer devices, but margins are higher, and customers stay for many years.

High Density Packaging Market Future Outlook

Heterogeneous Integration Becomes the Default for Compute

By the early 2030s, most high-end processors will be assembled from multiple dies rather than built as single monolithic chips. The IEA expects data-centre electricity demand to approach 945 TWh by 2030 [16]. That puts a premium on performance per watt, and shorter die-to-die links deliver it. Advanced semiconductor packaging will therefore account for a growing share of total chip value, with glass substrates and hybrid bonding as the key enabling steps.

Chiplet Platform Economics

Chiplets turn packaging into a platform business. Vendors that control interposer design rules, die-to-die IP and known-good-die testing will shape which third-party chiplets can be combined. As UCIe adoption broadens [11], expect pricing power to shift toward companies that offer an integrated design, packaging and test flow instead of discrete assembly steps.

Electrified Mobility Raises Packaging Content

The IEA's stated policies scenario has electric cars approaching 40% of global sales by 2030 [15]. Software-defined vehicles consolidate compute into a few domain controllers, each built around a multi-die SoC. That raises packaged value per vehicle and pushes automotive qualification standards into formats once reserved for data centres.

Sustainability and Supply-Chain Disclosure

Packaging plants consume large amounts of water and energy, and customers increasingly ask suppliers for Scope 3 emissions data. TSMC has committed to 100% renewable electricity across its operations by 2040 [7]. Similar pressure is reaching OSATs through European sustainability-reporting rules. Low-carbon processes and lead-free interconnects will become selection criteria in the High Density Packaging Market rather than optional extras.

Regional Market Share Analysis

Region Key Metric (2025 share / 2025 value / 2026–2035 CAGR) Primary Investment Themes
North America 36.4% share AI accelerators, CHIPS-funded packaging plants, defence electronics
Europe USD 8.18 B Automotive power and sensor modules, Chips Act pilot lines
Asia-Pacific 13.1% CAGR OSAT capacity, HBM stacking, smartphone SIP
Latin America 5.6% share Consumer electronics assembly, nearshoring
Middle East and Africa 9.4% CAGR Sovereign technology funds, telecom infrastructure
Total USD 42.60 B —

The High Density Packaging Market splits between demand-heavy North America and supply-heavy Asia-Pacific. Figures below allocate revenue by consumption region, meaning where packaged devices are purchased, rather than where assembly takes place.


North America

Country Key Metric Key Driver
US 82.5% share of region Hyperscaler AI spending, CHIPS Act packaging awards
Canada 10.6% CAGR Photonics packaging and the Bromont assembly cluster
Mexico USD 1.12 B Electronics and auto-parts nearshoring


Hyperscaler spending keeps North America at the top of the High Density Packaging Market. The largest US cloud operators collectively guided well over USD 200 billion of capital expenditure for 2025, and much of it goes to AI accelerators that ship in multi-die packages. On the supply side, CHIPS Act support for Amkor in Arizona and SK hynix in Indiana is building the region's first high-volume interposer and HBM packaging lines [9][24]. Mexico gains as electronics and auto-parts makers move final assembly closer to US customers.

Europe

Country Key Metric Key Driver
Germany 24.8% share of region Automotive tier-1 demand, power modules
UK 9.8% CAGR Compound semiconductor and RF design
France USD 1.06 B Aerospace & defence electronics, FD-SOI ecosystem
Italy 9.6% share of region Power and MEMS packaging
Spain 9.1% CAGR PERTE Chip programme investments
Nordic Countries USD 0.52 B Telecom infrastructure and medical devices
Russia 4.1% share of region Domestic substitution amid sanctions
Rest of Europe 8.6% CAGR Assembly operations in Central and Eastern Europe


Germany anchors European demand through automotive tier-1 suppliers that need radar packages and power modules qualified to automotive grades. Under the European Chips Act, the APECS pilot line led by Fraunhofer focuses on advanced packaging and heterogeneous integration, giving smaller European designers access to prototype capacity [2]. Europe's position in the High Density Packaging Market rests on reliability-critical niches rather than consumer volumes.

Asia-Pacific

Country Key Metric Key Driver
China 41.2% share of region Domestic OSAT scale-up, localisation policy
India 16.4% CAGR Semiconductor Mission ATMP approvals
Japan USD 2.38 B Substrate and materials leadership
South Korea 13.5% share of region HBM stacking at memory majors
ASEAN 14.8% CAGR Malaysian and Vietnamese OSAT expansion
Rest of Asia-Pacific USD 1.04 B Taiwan's CoWoS and OSAT base, Australian niches


Asia-Pacific is the production centre of the High Density Packaging Market. China holds the largest country position, as JCET, Tongfu and Huatian scale domestic capacity in response to export controls. India is the fastest-growing country in the region, with approved plants from Micron, Tata and CG Power–Renesas set to start output between 2025 and 2027 [13]. Taiwan, counted within Rest of Asia-Pacific, hosts TSMC's CoWoS lines and ASE's largest sites [7][8].

Latin America

Country Key Metric Key Driver
Brazil 58.4% share of region Manaus electronics assembly, PADIS incentives
Argentina 9.2% CAGR Tierra del Fuego electronics manufacturing
Rest of Latin America USD 0.62 B Costa Rica's test and assembly operations


Brazil dominates regional demand through the Manaus Free Trade Zone, where handsets, notebooks and set-top boxes are assembled for the domestic market. The PADIS tax regime has long encouraged local semiconductor assembly. Costa Rica, home to an Intel assembly and test site, gives the rest of the region a foothold in the back-end supply chain.

Middle East and Africa

Country Key Metric Key Driver
Saudi Arabia USD 0.46 B Vision 2030 National Semiconductor Hub
UAE 11.4% CAGR Sovereign AI investment, data-centre build-out
South Africa 15.8% share of region Automotive and telecom electronics
Egypt 9.7% CAGR Electronics design and assembly incentives
Rest of Middle East and Africa 33.0% share of region Israel's chip design and fab base


Sovereign capital is reshaping a region that historically imported nearly all packaged chips. Saudi Arabia launched a National Semiconductor Hub in 2024 to attract fabless firms. The UAE is channelling sovereign funds into AI data centres that consume accelerator-class packages. Israel, within the rest of the region, contributes deep design and fabrication expertise that supports local packaging demand.

High Density Packaging Market By Region, 2025-2035

High Density Packaging Market Segmentation

By Packaging Technique

The High Density Packaging Market is segmented by technique into MCM, MCP, SIP and 3D - TSV, each serving distinct cost and performance needs.

Segment Key Metric Primary Demand Driver
MCM USD 10.65 B Server CPUs, AI accelerators, defence modules
MCP 18.8% share Memory stacking in mobile and storage devices
SIP 34.6% share Smartphone RF, wearables, IoT modules
3D - TSV 14.9% CAGR HBM and logic-on-memory stacks


SIP is the dominant technique with a 34.6% share. It combines processors, RF chips and passives side by side in one module, which suits space-constrained phones and wearables. 3D - TSV grows fastest, at a 14.9% CAGR, because every HBM stack depends on vertical through-silicon vias, and 3D IC packaging is spreading from memory into logic. MCM remains essential for chiplet-based server processors, while MCP serves cost-sensitive NAND and DRAM combinations in mobile and storage products.

By Application

Application demand in the High Density Packaging Market spans Consumer Electronics, Aerospace & Defence, Medical Devices, IT & Telecom, Automotive and Other Applications.

Segment Key Metric Primary Demand Driver
Consumer Electronics 38.2% share Smartphones, wearables, tablets
Aerospace & Defence 9.6% CAGR Radar, satellite payloads, secure electronics
Medical Devices 7.4% share Hearing aids, implantables, diagnostics
IT & Telecom USD 9.93 B AI servers, 5G radios, networking ASICs
Automotive 14.2% CAGR ADAS processors, EV power modules
Other Applications USD 3.07 B Industrial automation, energy and utility controls


Consumer Electronics leads with a 38.2% share, driven by the module-heavy design of modern handsets and wearables. Automotive is the fastest-growing application, at a 14.2% CAGR, as centralised compute and silicon-carbide power modules multiply packaged content per vehicle. IT & Telecom carries the highest value per unit because of AI servers and 5G radios—Aerospace & Defence and Medical Devices value long-term reliability over cost, which keeps supplier relationships stable.

Competitive Benchmarking

The High Density Packaging Market has low-to-moderate concentration, with an estimated HHI of 850–950. The top five players hold roughly 48–55% of revenue [6]. Foundries and memory makers dominate the most advanced interposer and HBM work. OSATs lead in SIP and MCP volumes, and a long tail of regional assemblers serves industrial and consumer niches [8][9].

Company Est. Revenue Share Range Key Offerings for High Density Packaging Market Strategic Positioning
ASE Technology Holding ~14–17% SIP, fan-out, 2.5D integration, test Largest OSAT with a global multi-site footprint
Taiwan Semiconductor Manufacturing Company (TSMC) ~10–13% CoWoS, InFO, SoIC Front-to-back integration for AI accelerators
Amkor Technology ~9–12% SIP, flip-chip, 2.5D, automotive packages US and Asia diversification, Arizona campus
Samsung Electronics ~6–9% HBM stacking, I-Cube, X-Cube Memory-plus-foundry turnkey offering
JCET Group ~6–8% SIP, fan-out, XDFOI chiplet platform China's largest OSAT, domestic substitution
Intel Corporation ~5–8% EMIB, Foveros, glass substrates Foundry services with in-house packaging
Powertech Technology ~3–5% Memory MCP, TSV, flip-chip Memory-focused OSAT
Tongfu Microelectronics ~3–5% Flip-chip, MCM for CPUs and GPUs Close partnership with leading processor vendors
Toshiba Corporation ~1–3% Power modules, MCP Automotive and industrial power focus
IBM Corporation ~1–2% Chiplet R&D, co-packaged optics Research and licensing leadership
Fujitsu Limited ~1–2% High-reliability modules, server packaging Mission-critical computing niche


Recent News & Developments

Developments shaping the market between 2023 and 2025:

  • Intel (September 2023): Unveiled glass core substrates targeted for the second half of the decade, aiming at larger, flatter packages for AI chips [22]
  • US Department of Commerce (November 2023): Outlined the roughly USD 3 billion National Advanced Packaging Manufacturing Program, funding substrates, chiplets and pilot lines [1]
  • Tata Electronics (February 2024): Received Indian cabinet approval for a ₹27,000 crore assembly and test plant in Assam, expanding emerging-market capacity [13]
  • JCET Group (March 2024): Agreed to acquire an 80% stake in SanDisk Semiconductor (Shanghai) for about USD 624 million, strengthening its memory packaging capability [25]
  • SK hynix (April 2024): Announced a roughly USD 3.87 billion HBM packaging plant in West Lafayette, Indiana, its first US production site [24]
  • US Bureau of Industry and Security (December 2024): Added high-bandwidth memory to advanced computing export controls, reshaping HBM supply to China [20]
  • Amkor Technology (December 2024): Signed preliminary terms for up to about USD 407 million in CHIPS Act funding for its Arizona packaging campus [9]

High Density Packaging Market Report Scope

Parameter Details
Market Scope Global High Density Packaging Market by Packaging Technique, Application and Geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 11.2% (2026–2035)
Market Size checkpoints USD 42.60 B (2025); USD 47.37 B (2026); USD 73.94 B (2030); USD 123.14 B (2035)
Fastest Growing Segments 3D - TSV (14.9% CAGR); Automotive (14.2% CAGR); Asia-Pacific (13.1% CAGR)
Companies Profiled ASE Technology Holding, TSMC, Amkor Technology, Samsung Electronics, JCET Group, Intel, Powertech Technology, Tongfu Microelectronics, Toshiba, IBM, Fujitsu
Valuation Currency USD Billion, nominal

FAQs

How should buyers choose between SIP and 3D - TSV in the High Density Packaging Market?
SIP suits cost-sensitive designs that place RF, power and sensor dies side by side. 3D - TSV justifies its premium only when bandwidth or footprint limits dominate, as in memory stacks and AI accelerators [6].
What is hybrid bonding, and why does it matter?
Hybrid bonding joins dies through direct copper-to-copper and oxide bonds, removing solder bumps and enabling pitches below 10 microns. It is moving from image sensors into logic and memory stacking [12].
Which reliability standards apply to automotive products in the High Density Packaging Market?
Automotive packages must pass AEC-Q100 qualification, and Grade 0 parts are rated from −40°C to 150°C. Suppliers also need IATF 16949 certification, which typically lengthens design-in cycles by 12–18 months [12].
Should OEMs source packaging from foundries or OSATs?
Foundries lead in interposer-based AI packaging, where front-end and back-end steps are tightly linked. OSATs offer more format choices, multi-region sites and usually lower pricing for SIP and MCP volumes [8][9].
How do export controls affect sourcing strategies in the High Density Packaging Market?
Buyers increasingly qualify a second packaging site outside China for advanced computing products to reduce licensing risk. Malaysia, Vietnam, India and the US benefit most from this diversification [20].
What are the main investment risks for new entrants?
New entrants to the High Density Packaging Market face multi-billion-dollar facility costs alongside multi-year customer qualification. Without an anchor customer or government co-funding, capacity can sit underused for years [1].
Which emerging use cases could add demand after 2030?
Co-packaged optics, which places optical engines beside switch ASICs, could cut data-centre interconnect power substantially. Quantum control electronics and neuromorphic chips are smaller niches that also need dense, low-latency packaging [16].
Author
Author Author Profile Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author Co-Author Profile Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.