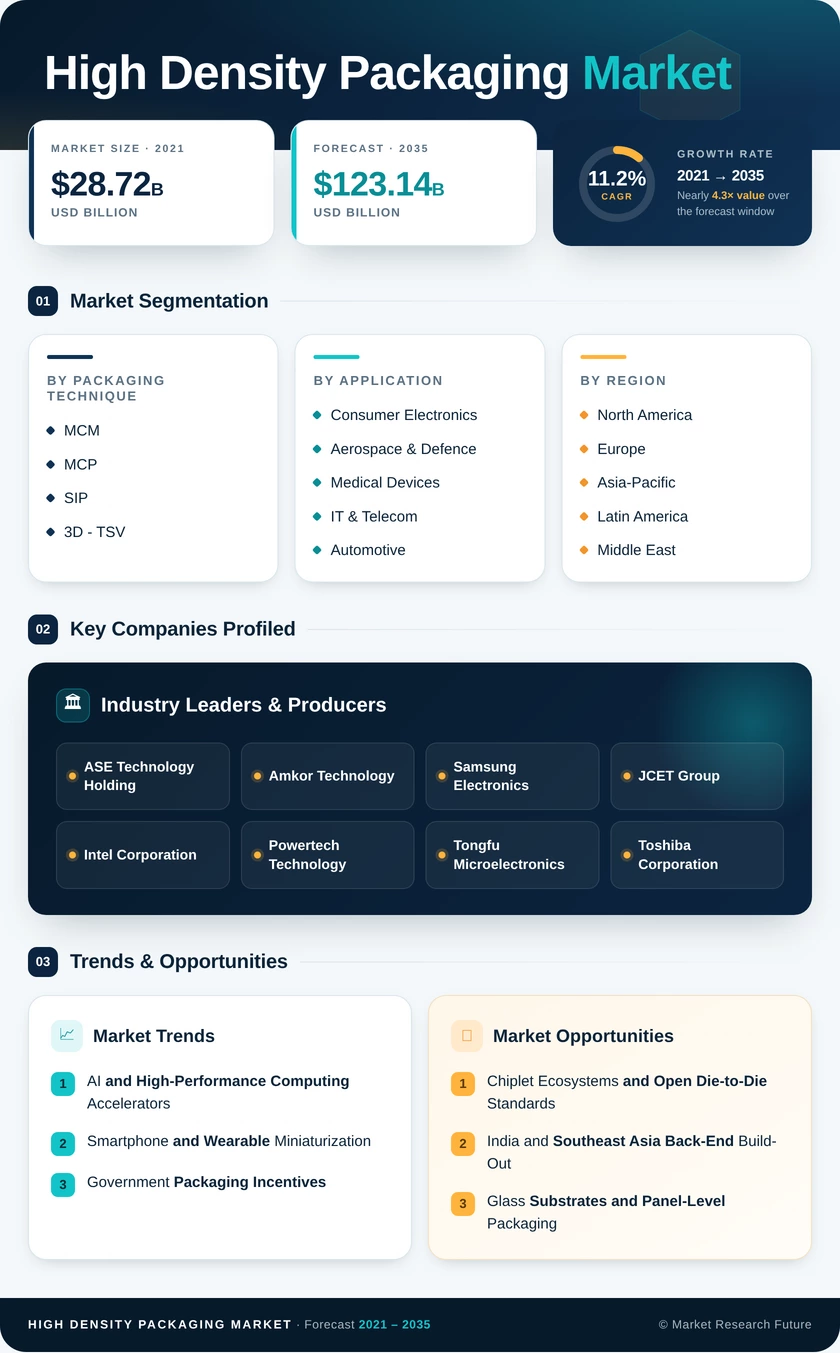
High Density Packaging Market (2026 – 2035)

ID: MRFR/SEM/40977-HCR 128 Pages Nirmit Biswas Last Updated: October 06, 2026
High Density Packaging Market Size, Share and Research Report By Packaging Technique (MCM, MCP, SIP, and 3D-TSV), By Application (Consumer Electronics, Aerospace & Defence, Medical Devices, IT & Telecom, Automotive, and Other Applications) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035
High Density Packaging Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.2%
2025 Market SizeUSD 42.60 Billion
2035 Market SizeUSD 123.14 Billion
Key Players
ASE Technology Holding
Amkor Technology
Samsung Electronics
JCET Group
Intel Corporation
Powertech Technology
Opportunities
  • Chiplet Ecosystems and Open Die-to-Die Standards
  • India and Southeast Asia Back-End Build-Out
  • Glass Substrates and Panel-Level Packaging
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Packaging Technique | |
    2. 2.2 By Application | |
    3. 2.3 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 AI and High-Performance Computing Accelerators | |
    2. 4.2 Smartphone and Wearable Miniaturization | |
    3. 4.3 Government Packaging Incentives | |
    4. 4.4 Vehicle Electrification and ADAS | |
    5. 4.5 IoT Device Proliferation | |
    6. 4.6 5G Infrastructure and RF Module Density | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 High Capital Intensity of Packaging Lines | |
    2. 5.2 Export Controls and Geopolitical Fragmentation | |
    3. 5.3 Thermal and Yield Challenges in 3D Stacking | |
    4. 5.4 Substrate and Materials Supply Constraints | |
    5. 5.5 Skilled Workforce Shortages | |
  6. 6 Opportunities | |
    1. 6.1 Chiplet Ecosystems and Open Die-to-Die Standards | |
    2. 6.2 India and Southeast Asia Back-End Build-Out | |
    3. 6.3 Glass Substrates and Panel-Level Packaging | |
    4. 6.4 Yield Data Monetization and Packaging-as-a-Service | |
    5. 6.5 Medical Implantables and Wearable Diagnostics | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 Latin America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of Latin America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Heterogeneous Integration Becomes the Default for Compute | |
    2. 8.2 Chiplet Platform Economics | |
    3. 8.3 Electrified Mobility Raises Packaging Content | |
    4. 8.4 Sustainability and Supply-Chain Disclosure | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Packaging Technique | | |
      1. 9.1.1 MCM | | |
      2. 9.1.2 MCP | | |
      3. 9.1.3 SIP | | |
      4. 9.1.4 3D - TSV | |
    2. 9.2 By Application | | |
      1. 9.2.1 Consumer Electronics | | |
      2. 9.2.2 Aerospace & Defence | | |
      3. 9.2.3 Medical Devices | | |
      4. 9.2.4 IT & Telecom | | |
      5. 9.2.5 Automotive | | |
      6. 9.2.6 Other Applications | |
  10. 10 Competitive Landscape | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Report Summary — Key Metrics, 2025–2035 | |
  16. TABLE 2 Global Market Size and Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis | |
  18. TABLE 4 Restraints Impact Analysis | |
  19. TABLE 5 Regional Summary, 2025 | |
  20. TABLE 6 North America — Country-Level Analysis | |
  21. TABLE 7 Europe — Country-Level Analysis | |
  22. TABLE 8 Asia-Pacific — Country-Level Analysis | |
  23. TABLE 9 Latin America — Country-Level Analysis | |
  24. TABLE 10 Middle East and Africa — Country-Level Analysis | |
  25. TABLE 11 Market Segmentation, by Packaging Technique | |
  26. TABLE 12 Market Segmentation, by Application | |
  27. TABLE 13 Competitive Benchmarking Matrix | |
  28. TABLE 14 Report Scope and Methodology | |
  29. TABLE 15 Detailed Sources and Citations | |
  30. TABLE 16 Segmentation Quick Reference | |
  31. TABLE 17 Packaging Technique — Sub-Segment Key Trends | |
  32. TABLE 18 Application — Sub-Segment Key Trends | | LIST OF FIGURES | |
  33. FIGURE 1 Market Dynamics Overview — Drivers, Restraints and Opportunities | |
  34. FIGURE 2 Industry Value Chain Analysis | |
  35. FIGURE 3 Porter's Five Forces Analysis | |
  36. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  37. FIGURE 5 Market Share, by Packaging Technique, 2025 | |
  38. FIGURE 6 Market Share, by Application, 2025 | |
  39. FIGURE 7 Regional Market Share, 2025 | |
  40. FIGURE 8 Regional Growth Comparison, 2026–2035 CAGR | |
  41. FIGURE 9 Competitive Landscape — Estimated Revenue Share Ranges | |
  42. FIGURE 10 Recent Developments Timeline, 2023–2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Packaging TechniqueMCM, MCP, SIP, 3D - TSVSIP — 34.6% share3D - TSV — 14.9% CAGR
By ApplicationConsumer Electronics, Aerospace & Defence, Medical Devices, IT & Telecom, Automotive, Other ApplicationsConsumer Electronics — 38.2% shareAutomotive — 14.2% CAGR
By RegionNorth America, Europe, Asia-Pacific, Latin America, Middle East and AfricaNorth America — 36.4% shareAsia-Pacific — 13.1% CAGR


Market Segmentation Overview

By Packaging Technique

Sub-SegmentKey Trend
MCMChiplet-based server CPUs and AI accelerators on silicon bridges
MCPCost-optimised DRAM and NAND combinations for mobile and storage
SIPRF front-end and sensor modules in phones and wearables
3D - TSVTwelve- and sixteen-high HBM stacks moving toward hybrid bonding


SIP leads this dimension because handset and wearable makers need RF, power and sensor dies combined in one compact module that drops straight onto a crowded board. 3D - TSV grows fastest, since every HBM stack paired with an AI accelerator relies on through-silicon vias, and taller stacks raise TSV count per package. MCM keeps steady demand from chiplet server processors, while MCP stays the low-cost route for mobile memory.

By Application

Sub-SegmentKey Trend
Consumer ElectronicsModule-heavy flagship phones, smartwatches and earbuds
Aerospace & DefenceRadiation-tolerant, secure multi-chip modules for radar and satellites
Medical DevicesBiocompatible micro-packages for hearing aids and implantables
IT & TelecomAI server accelerators and 5G massive MIMO radios
AutomotiveMulti-die ADAS SoCs and silicon-carbide power modules
Other ApplicationsIndustrial automation, energy and utility control electronics


Consumer Electronics remains the largest application because each flagship smartphone integrates several SIP modules, and annual upgrade cycles keep volumes high. Automotive grows fastest as zonal architectures concentrate ADAS compute into multi-die SoCs that must pass AEC-Q100 qualification. IT & Telecom carries the highest value per package, while Aerospace & Defence and Medical Devices reward long-term reliability over unit cost.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.