Graphics Processing Unit Market (2026 - 2035)

Graphics Processing Unit Market Size, Share and Research Report By Integration Type (Integrated GPUs (iGPU), and Discrete GPUs (dGPU)), By Device Application (Mobile Devices and Tablets, PCs and Workstations, Servers and Data Center Accelerators, Gaming Consoles and Handhelds, Automotive and ADAS, and Other Embedded and Edge Devices) – Industry Forecast Till 2035
ID: MRFR/SEM/65053-HCR 200 Pages Nirmit Biswas, Garvit Vyas Last Updated: October 06, 2026
Graphics Processing Unit Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.30%
2025 Market SizeUSD 117.85 Billion
2035 Market SizeUSD 448.47 Billion
Key Players
NVIDIA Corporation
Advanced Micro Devices
Intel Corporation
Apple Inc.
Qualcomm Technologies
MediaTek Inc.
Opportunities
  • Sovereign Compute in Emerging Markets
  • GPU-as-a-Service and Capacity Monetization
  • Edge AI and Robotics Modules

Graphics Processing Unit Market Summary

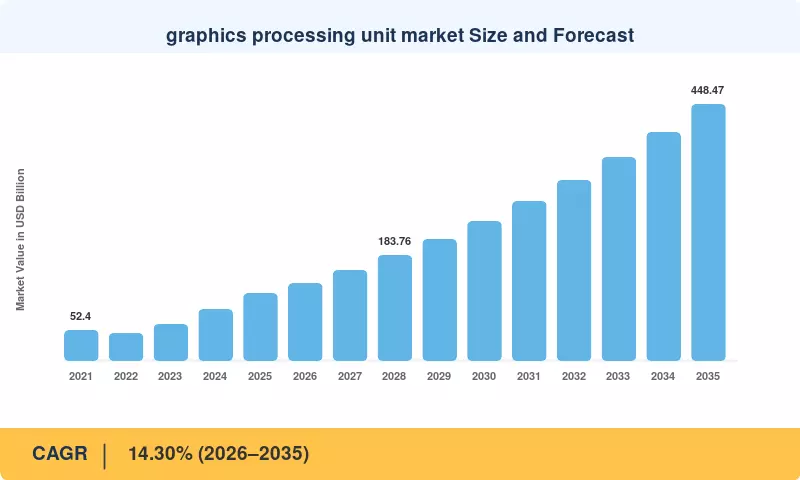
The Graphics Processing Unit Market was valued at USD 117.85 Billion in 2025 and is forecast to reach USD 134.70 Billion in 2026, rising to USD 448.47 Billion by 2035 at a CAGR of 14.30% over 2026–2035. Two catalysts anchor that path. Microsoft guided to roughly USD 80 billion of AI-enabled data center spending in fiscal 2025 [13], and the USD 500 Billion Stargate program announced in January 2025 points to multi-year demand for training and inference clusters [12].

Accelerated systems, where parallel processing gear performs AI training, inference, simulation, and rendering on the same silicon, are replacing outdated CPU-centric server racks and fixed-function graphics pipelines. In fiscal 2025, NVIDIA reported data center revenue of USD 115.2 billion, up from USD 47.5 billion the previous year [1], indicating that customers are replacing rather than expanding general-purpose capacity. The performance frontier is now defined by rack-scale systems with dense interconnects, liquid cooling, and high-bandwidth memory.

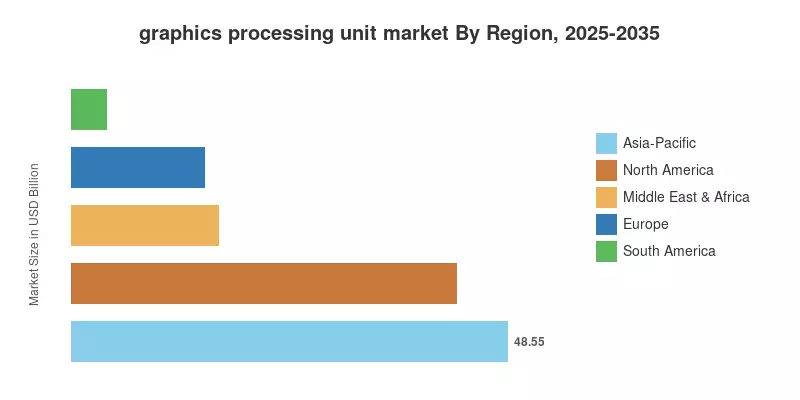
With a 41.2% market share in 2025, Asia-Pacific dominates the graphics processing unit market. It is also the fastest-growing area, thanks to new sovereign AI initiatives in India and the depth of device manufacturing in China, Japan, and South Korea. North America comes in second, with hyperscale build-outs expected to generate USD 42.90 billion in 2025. Demand will shift from model training to inference during the next ten years, expanding the customer base much beyond a small number of cloud providers.


Key Report Takeaways

• By Integration Type

  • Discrete GPUs (dGPU) held 67.2% of the Graphics Processing Unit Market in 2025, reflecting the memory bandwidth that large-model training requires.
  • Integrated GPUs (iGPU) are projected to grow at a 12.1% CAGR through 2035 as AI-capable notebooks and smartphone SoCs gain graphics headroom.

• By Device Application

  • Servers and Data Center Accelerators account for 35.9% of the Graphics Processing Unit Market, the largest application share.
  • Automotive and ADAS is the fastest-growing application at an 18.6% CAGR, driven by centralized vehicle compute
  • Mobile Devices and Tablets generated USD 20.03 Billion in 2025

• By Region

Market Size and Forecast (2021–2035)

Market Research Future built this series bottom-up from vendor-reported segment revenue, shipment data from trackers such as Jon Peddie Research [15] and hyperscaler capital expenditure disclosures, then reconciled it top-down against global semiconductor sales of USD 627.6 billion in 2024 [11]. Values for the Graphics Processing Unit Market cover discrete boards, data center accelerators and the attributed value of integrated graphics in processors and SoCs. 2024 is the spike year, when Hopper-class accelerator volumes and hyperscale capex lifted revenue 42.0%, while 2022 reflects the cryptocurrency-mining collapse and a PC channel inventory correction.
graphics processing unit market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Hyperscale AI Infrastructure Capital Expenditure +4.2% North America, Asia-Pacific Short term (≤2 yr)
Generative AI Training and Inference Scaling +3.1% Global Medium term (2–4 yr)
Sovereign AI Programs +1.6% Asia-Pacific, Middle East & Africa, Europe Medium term (2–4 yr)
AI PC and Client Refresh Cycle +1.3% Global Short term (≤2 yr)
Gaming and Neural Rendering +0.9% Asia-Pacific, North America Short term (≤2 yr)
Centralized Automotive Compute +0.8% Europe, Asia-Pacific, North America Long term (≥4 yr)
Semiconductor Industrial Policy +0.6% North America, Europe, Asia-Pacific Long term (≥4 yr)


Hyperscale AI Infrastructure Capital Expenditure

Cloud providers are the largest source of incremental demand. Microsoft guided to roughly USD 80 billion of AI data center spending in fiscal 2025 [13], and OpenAI, SoftBank and Oracle committed USD 100 billion for immediate deployment within the USD 500 billion Stargate program [12]. These budgets convert directly into accelerator orders because GPUs represent the majority of an AI server's bill of materials. Spending visibility through 2027 gives this driver the heaviest near-term weight.

Generative AI Training and Inference Scaling

Larger models, longer context windows and reasoning workloads keep pushing compute requirements upward. NVIDIA's data center revenue grew 142% in fiscal 2025 to USD 115.2 billion [1], while AMD reported more than USD 5 billion of Instinct accelerator revenue in 2024, its first full year of MI300 volume [2]. Inference now absorbs a rising share of installed capacity as enterprises deploy agents and copilots, extending demand beyond the frontier labs that dominated 2023 purchasing.

Sovereign AI Programs

Governments increasingly treat compute as strategic infrastructure. India's IndiaAI Mission allocated INR 10,371.92 crore, about USD 1.25 billion, including subsidized access to a shared pool of more than 18,000 GPUs [14]. The European Commission's InvestAI initiative targets EUR 200 billion of AI investment, with EUR 20 billion reserved for AI gigafactories [10]. Saudi Arabia's HUMAIN agreed in May 2025 to deploy an initial 18,000 NVIDIA GB300 chips [18].

AI PC and Client Refresh Cycle

Microsoft ended support for Windows 10 on 14 October 2025 [23], forcing a commercial PC refresh just as Copilot+ PCs set a 40 TOPS on-device AI baseline. AMD's Ryzen AI 300 Series pairs up to 50 TOPS of NPU compute with integrated Radeon graphics [2], raising graphics content per notebook. The refresh lifts integrated graphics value and sustains demand for entry discrete cards in creator and workstation systems.

Gaming and Neural Rendering

Gaming remains a large, recurring revenue pool. NVIDIA's gaming revenue reached USD 11.4 billion in fiscal 2025, up 9% [1], and the GeForce RTX 50 Series launched at CES 2025 introduced DLSS 4 multi-frame generation, which uses AI to create up to three extra frames per rendered frame [19]. Each architecture transition resets the upgrade cycle for PC gamers, with add-in board shipments recovering from the 2022 trough [15].

Centralized Automotive Compute

Vehicle architectures are consolidating dozens of electronic control units into a few central computers. NVIDIA's automotive revenue rose 55% to USD 1.7 billion in fiscal 2025 [1], driven by DRIVE Orin deployments, with DRIVE Thor following for Level 2+ and Level 3 programs. Each step in autonomy multiplies required inference throughput, so GPU content per vehicle rises even if light-vehicle production stays flat. Long design-win lead times make this a long-term driver.

Semiconductor Industrial Policy

Public funding is expanding domestic chip and packaging capacity. The U.S. CHIPS and Science Act provides USD 52.7 billion, including USD 39 billion in manufacturing incentives [7]. The European Chips Act aims to mobilize more than EUR 43 Billion [9], and China's third national integrated circuit fund raised RMB 344 Billion, about USD 47.5 Billion, in May 2024 [22]. New fab and advanced-packaging capacity eases supply bottlenecks over the long term.

Restraints Impact Analysis

Restraint impacts are directional estimates of downward pressure on growth in the Graphics Processing Unit Market. They interact with drivers and with one another, so they should not be summed or subtracted directly from the forecast CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Export Controls on Advanced Accelerators -1.4% Asia-Pacific (China), North America Short to medium term
Advanced Packaging and HBM Supply Constraints -1.1% Global Short term (≤2 yr)
Data Center Power Availability -1.0% North America, Europe Medium term (2–4 yr)
Custom Silicon Substitution -0.8% North America Medium to long term
High System Costs and ROI Uncertainty -0.5% Global Short term (≤2 yr)


Export Controls on Advanced Accelerators

The U.S. Bureau of Industry and Security tightened controls on advanced computing items in October 2023, closing performance-density loopholes that had allowed China-specific variants [8]. A further license requirement on the H20 in April 2025 led NVIDIA to record a USD 4.5 billion inventory charge [19]. These restrictions shrink the China data center opportunity for U.S. vendors and accelerate domestic substitution by Huawei and others.

Advanced Packaging and HBM Supply Constraints

Leading accelerators depend on CoWoS packaging and HBM stacks, both supply-limited. TSMC roughly doubled CoWoS capacity in 2024 and planned a further doubling in 2025 [4], yet TrendForce reported 2025 HBM output as largely pre-allocated [16]. Shortages ripple into graphics card manufacturing as memory and substrate costs rise, delaying shipments and squeezing board-partner margins.

Data Center Power Availability

Electricity has become a gating factor for cluster deployments. The IEA estimates data centers consumed about 415 TWh in 2024 and projects roughly 945 TWh by 2030 [5]. Lawrence Berkeley National Laboratory found U.S. data centers used 4.4% of national electricity in 2023, potentially reaching 6.7–12% by 2028 [6]. Grid interconnection queues in Virginia, Ireland and the Netherlands are delaying projects by years.

Custom Silicon Substitution

Hyperscalers are designing in-house accelerators to cut dependence on merchant GPUs. Google's TPU line, AWS Trainium2 and Meta's MTIA all target lower cost per token. Broadcom, a key custom-silicon partner, reported AI revenue of USD 12.2 billion in fiscal 2024, up 220% [24]. Wider ASIC adoption caps GPU share inside the largest cloud fleets, especially for stable, high-volume inference.

High System Costs and ROI Uncertainty

Rack-scale AI systems cost millions of dollars per rack, and a single eight-GPU server can exceed USD 300,000. Many enterprises have yet to prove measurable returns, pushing smaller buyers toward cloud rental or deferred purchases. If AI application revenue lags capex, spending could pause, much as graphics demand did in the 2022 downturn [15].

Graphics Processing Unit Market Opportunities

Sovereign Compute in Emerging Markets

Emerging economies are building national GPU clouds, and they prefer turnkey stacks that bundle hardware, networking and software. India's 18,000-GPU common compute pool [14], Saudi Arabia's HUMAIN [18] and Brazil's national AI plan, which earmarks BRL 23 billion through 2028 [25], open a new procurement channel in the Graphics Processing Unit Market. Vendors offering financing, local integration partners and data-residency guarantees stand to win these multi-year contracts.

GPU-as-a-Service and Capacity Monetization

Hourly and reserved GPU rental is turning compute into a tradable service. NVIDIA's DGX Cloud and a wave of specialist GPU clouds let operators monetize idle capacity, while utilization telemetry supports per-token and outcome-based pricing [19]. This new business model expands the Graphics Processing Unit Market to startups and enterprises that cannot fund rack-scale purchases, and it creates recurring software revenue around scheduling and orchestration.

Edge AI and Robotics Modules

Robots, smart cameras and industrial inspection systems need local inference with tight power budgets. NVIDIA cut the price of its Jetson Orin Nano developer kit to USD 249 in December 2024 while lifting performance to 67 TOPS [19], lowering the entry cost for robotics developers. Purpose-built modules for factories, warehouses and retail terminals give vendors a broad, fragmented installed base.

Software-Defined Vehicle Compute

The EU General Safety Regulation made advanced driver-assistance features mandatory on all new cars from July 2024, and Chinese automakers are racing to ship urban navigation assist. Both trends raise compute per vehicle and favor upgradable central computers. Suppliers that pair automotive-grade GPUs with safety-certified software can lock in platforms that ship for six to eight years.

Energy-Efficient Inference for Enterprise Data Centers

Most enterprise facilities cannot host 120 kW liquid-cooled racks. Air-cooled PCIe accelerators that fit existing power envelopes let companies run private inference on-premises, keeping regulated data in-house. With the IEA flagging data center efficiency as a policy priority [5], this retrofit segment offers the Graphics Processing Unit Market a large brownfield opportunity outside hyperscale campuses.

Graphics Processing Unit Market Future Outlook

Inference Becomes the Dominant Workload

Training built the first wave of the Graphics Processing Unit Market's AI boom, but inference will drive the next decade. Every deployed agent, search query and copilot consumes compute continuously, so inference capacity scales with users rather than with model releases. The IEA expects electricity use by accelerated servers to grow about 30% a year through 2030 [5], a proxy for how quickly inference fleets will expand. Vendors will compete on cost per token rather than peak training throughput.

Power, Cooling and Siting Shape Deployment

Watts, not wafers, will increasingly cap growth. With global data center demand heading toward roughly 945 TWh by 2030 [5] and U.S. data centers possibly reaching 12% of national electricity by 2028 [6], operators are co-locating clusters with nuclear, gas and renewable generation. Direct liquid cooling will move from frontier racks to the mainstream, and GPU roadmaps will prioritize performance per watt as the key purchasing metric.

Regionalized Supply Chains

Geopolitics is reshaping where GPUs are designed, packaged and sold. TSMC's Arizona fabs [4], CHIPS Act incentives [7] and China's domestic accelerator push [22] point toward parallel supply chains for U.S.-aligned and Chinese buyers. This regionalization raises costs in the Graphics Processing Unit Market but also creates duplicate capacity, which reduces single-point supply risk over the long term.

Graphics and AI Converge in Client Devices

Rendering and AI are merging in PCs, consoles and handhelds. Neural rendering techniques such as DLSS 4 generate most displayed pixels with AI [19], and unified-memory laptops can now run sizeable language models locally. Over the forecast period, client GPUs will be judged as much on AI throughput as on frame rates, blurring the line between graphics and inference silicon in consumer devices.

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America USD 42.90 Billion Hyperscale AI campuses, CHIPS Act fabs, domestic AI server assembly
Europe 12.6% CAGR (2026–2035) AI gigafactories, EuroHPC supercomputers, automotive compute
Asia-Pacific 41.2% share (2025) Device manufacturing, domestic accelerators, sovereign AI programs
South America 3.3% share (2025) National AI plans, cloud region expansion
Middle East & Africa 13.9% CAGR (2026–2035) Sovereign AI clusters, Gulf data center campuses
Total USD 117.85 Billion —

Regional demand in the Graphics Processing Unit Market follows two maps: where devices are manufactured and where AI clusters are built. Asia-Pacific dominates on both counts, North America concentrates the largest data center fleets, and the Middle East is emerging as a sovereign AI hub.


North America

Country Key Metric (2025) Key Driver
United States 88.5% of regional revenue Hyperscaler capex and frontier model labs
Canada 13.2% CAGR (2026–2035) Sovereign AI Compute Strategy
Mexico USD 1.93 Billion AI server assembly and nearshoring


United States demand is driven by the four largest cloud providers and frontier labs, with Stargate's first campus in Abilene, Texas, illustrating the scale of single-site deployments [12]. NVIDIA announced in April 2025 that it would produce Blackwell chips in Arizona and build up to USD 500 billion of AI infrastructure in the U.S. over four years [19], reinforced by CHIPS Act incentives [7]. Canada committed CAD 2 billion to a Sovereign AI Compute Strategy in Budget 2024, while Mexico's Guadalajara region is becoming a hub for rack-scale AI server assembly.

Europe

Country Key Metric (2025) Key Driver
Germany 24.8% of regional revenue Automotive compute and EuroHPC JUPITER
United Kingdom USD 3.45 Billion Isambard-AI and national compute investment
France 12.9% CAGR (2026–2035) EUR 109 billion AI investment pledges
Rest of Europe 37.0% of regional revenue Nordic data centers and AI gigafactory bids


Europe's growth rests on public-private compute programs. The EU Chips Act [9] and the EUR 200 Billion InvestAI initiative [10] fund AI gigafactories, while Germany's JUPITER exascale system at Jülich runs on roughly 24,000 NVIDIA Grace Hopper superchips. The UK's Isambard-AI in Bristol adds 5,448 GH200 chips for national research, and France secured EUR 109 billion of AI infrastructure pledges in February 2025. Power prices and grid capacity remain the main brakes on faster cluster deployment [5].

Asia-Pacific

Country Key Metric (2025) Key Driver
China 38.6% of regional revenue Domestic accelerators and gaming demand
Japan USD 7.14 Billion METI AI and semiconductor funding
South Korea 15.8% CAGR (2026–2035) HBM ecosystem and AI data centers
India 21.4% CAGR (2026–2035) IndiaAI Mission compute pool
Rest of Asia-Pacific 22.5% of regional revenue Southeast Asian data center build-outs


Asia-Pacific anchors the Graphics Processing Unit Market through manufacturing scale and fast-rising AI demand. China pairs the world's largest gaming base with a push for domestic accelerators, backed by the RMB 344 billion third national chip fund [22]. Japan's METI unveiled a framework of more than JPY 10 trillion for AI and semiconductors through 2030 [17], and South Korea benefits from hosting the leading HBM suppliers. India is the fastest-growing country, propelled by the IndiaAI Mission's subsidized GPU pool [14].

South America

Country Key Metric (2025) Key Driver
Brazil 52.4% of regional revenue National AI plan and cloud regions
Argentina 10.8% CAGR (2026–2035) Data center investment in Patagonia
Rest of South America USD 1.12 Billion Chile and Colombia cloud expansion


Brazil leads regional demand, supported by the Brazilian Artificial Intelligence Plan, which commits BRL 23 Billion to AI infrastructure, research and public services through 2028 [25], including a national supercomputer. Hyperscalers continue to add cloud regions in São Paulo and Santiago. Currency volatility and import duties on electronics raise system costs, so cloud rental rather than on-premises ownership dominates enterprise access across the region.

Middle East & Africa

Country Key Metric (2025) Key Driver
Saudi Arabia 19.2% CAGR (2026–2035) HUMAIN sovereign AI build-out
United Arab Emirates 21.6% of regional revenue Stargate UAE and G42 campuses
South Africa USD 0.71 Billion Cloud regions and financial services AI
Rest of Middle East & Africa 36.0% of regional revenue Qatar, Israel and Egypt data centers


Gulf states are converting energy wealth into compute capacity. Saudi Arabia's HUMAIN, backed by the Public Investment Fund, plans several hundred thousand NVIDIA GPUs over five years, starting with 18,000 GB300 chips [18]. The UAE announced Stargate UAE in May 2025, a 1 GW cluster in Abu Dhabi built with OpenAI, Oracle and NVIDIA. Low-cost power and fast permitting give the Gulf a structural advantage, although export licensing still governs shipment timing [8].

graphics processing unit market By Region, 2025-2035

Graphics Processing Unit Market Segmentation

By Integration Type

The Graphics Processing Unit Market splits into two integration types with very different economics: dedicated accelerator boards and graphics built into processors.

Segment Key Metric Primary Demand Driver
Integrated GPUs (iGPU) 12.1% CAGR (2026–2035) AI PCs, smartphone SoCs and unified memory platforms
Discrete GPUs (dGPU) 67.2% share (2025) AI training, HBM bandwidth and enthusiast gaming


Discrete GPUs (dGPU) dominate value and also grow faster, because frontier training and high-throughput inference depend on dedicated HBM and local memory bandwidth that shared system resources cannot match [1][19]. Integrated GPUs (iGPU) ship in far higher unit volumes inside notebooks, tablets and phones, and their 12.1% CAGR reflects rising graphics content in AI-capable processors [2]. Integrated parts will gain relevance at the edge, while discrete products hold the performance frontier and most of the profit pool.

By Device Application

Device application shapes buying behavior in the Graphics Processing Unit Market, from hyperscale procurement to consumer upgrade cycles.

Segment Key Metric Primary Demand Driver
Mobile Devices and Tablets USD 20.03 Billion (2025) On-device AI and mobile gaming
PCs and Workstations 24.6% share (2025) AI PC refresh and creator workloads
Servers and Data Center Accelerators 35.9% share (2025) AI factories and inference clusters
Gaming Consoles and Handhelds 8.4% CAGR (2026–2035) Console generations and PC handhelds
Automotive and ADAS 18.6% CAGR (2026–2035) Centralized vehicle compute
Other Embedded and Edge Devices 6.2% share (2025) Robotics, industrial vision and retail inference


Servers and Datacenter Accelerators lead, as AI factories now run as long-duration infrastructure for training, post-training and inference [1]. PCs and Workstations follow on the Windows 10 refresh [23], while Mobile Devices and Tablets add on-device AI capability. Automotive and ADAS grow fastest from a small base as vehicles centralize compute. Gaming Consoles and Handhelds grow steadily but slower, and Other Embedded and Edge Devices broaden the installed base through robotics and industrial modules.

Competitive Benchmarking

The Graphics Processing Unit Market shows medium overall concentration that masks sharp differences by tier. Market Research Future estimates the top five vendors hold roughly 82–86% of revenue and places the Herfindahl-Hirschman Index in the 2,700–3,000 range, driven by one supplier's lead in data center accelerators. Integrated and mobile graphics remain more fragmented across SoC vendors and GPU IP licensors.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
NVIDIA Corporation ~48–54% Blackwell B200/GB200, GeForce RTX 50 Series, DRIVE Thor, Jetson Full-stack leader in accelerators, networking and software
Advanced Micro Devices (AMD) ~10–13% Instinct MI300/MI350, Radeon RX 9000, Ryzen AI with integrated Radeon Second-source accelerator supplier with open software strategy
Intel Corporation ~7–10% Arc B-Series, Core Ultra Xe graphics, Gaudi 3 Integrated graphics volume leader rebuilding discrete presence
Apple Inc. ~6–8% M-series and A-series integrated GPUs Vertically integrated unified-memory platforms
Qualcomm Technologies ~5–7% Adreno GPUs in Snapdragon mobile and PC platforms Mobile and Arm-based PC graphics leader
MediaTek Inc. ~2–3% Dimensity SoCs with Arm Immortalis graphics High-volume Android and smart-device SoCs
Arm Holdings ~1–3% Mali and Immortalis GPU IP Licensing model across mobile and automotive
Huawei Technologies ~1–3% Ascend AI accelerators, MaLeon mobile GPUs Domestic alternative for China data centers
Samsung Electronics ~1–2% Xclipse GPUs in Exynos SoCs Mobile graphics plus HBM memory supply
Imagination Technologies ~<1% PowerVR and IMG DXT GPU IP Low-power IP for automotive and mobile


Recent News & Developments

  • AMD (December 2023): Launched the Instinct MI300X with 192 GB of HBM3, giving hyperscalers a credible second source for large-model inference [2]
  • NVIDIA (March 2024): Unveiled the Blackwell platform at GTC, introducing the B200 and GB200 NVL72 rack-scale system that defined 2025 data center demand [19]
  • China National IC Fund (May 2024): Raised RMB 344 billion for its third phase, funding domestic chip and accelerator capacity amid export controls [22]
  • Intel (December 2024): Released the Arc B580 at USD 249, renewing competition in mainstream discrete graphics [21]
  • OpenAI, SoftBank and Oracle (January 2025): Announced the USD 500 billion Stargate project, the largest single AI infrastructure commitment to date [12]
  • NVIDIA (January 2025): Launched the GeForce RTX 50 Series with DLSS 4 at CES, resetting the PC gaming upgrade cycle [19]
  • AMD (March 2025): Completed its USD 4.9 billion acquisition of ZT Systems, adding rack-scale system design capability [20]
  • HUMAIN and NVIDIA (May 2025): Agreed to deploy 18,000 GB300 chips in Saudi Arabia as the first phase of a sovereign AI build-out [18]

Graphics Processing Unit Market Report Scope

Parameter Details
Market Scope Graphics Processing Unit Market covering integrated and discrete GPUs across mobile, PC, server, console, automotive and embedded applications.
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 14.30% (2026–2035)
Market Size checkpoints USD 117.85 Billion (2025); USD 134.70 Billion (2026); USD 278.00 Billion (2031); USD 448.47 Billion (2035)
Fastest Growing Segments Discrete GPUs (dGPU); Automotive and ADAS (18.6% CAGR); Asia-Pacific
Companies Profiled NVIDIA, AMD, Intel, Apple, Qualcomm, MediaTek, Arm, Huawei, Samsung, Imagination Technologies
Valuation Currency USD Billion

FAQs

Should enterprises buy GPU clusters or rent cloud capacity?
Ownership typically pays back when sustained utilization stays above roughly 60–70%, because hourly cloud pricing embeds provider margin and idle-time risk. Bursty or experimental workloads remain cheaper to rent, so many buyers own a base cluster and burst to cloud for peaks.
How do software ecosystems affect switching costs in the Graphics Processing Unit Market?
CUDA's nearly two decades of libraries, kernels and developer familiarity make moving workloads to rival hardware costly in engineering time. AMD's open-source ROCm and frameworks such as PyTorch and OpenAI Triton are narrowing that gap, chiefly for inference on standard model architectures.
What end-of-life rules apply to products in the Graphics Processing Unit Market?
In the European Union, graphics cards and servers fall under the WEEE Directive, which makes producers finance collection and recycling. The Graphics Processing Unit Market also faces EU Ecodesign rules for servers, which set firmware and spare-part availability requirements.
Is there a resale market for used data center GPUs?
Yes, and it is growing as hyperscalers retire Ampere-generation accelerators after four to six years of service. Refurbished units flow to universities, startups and inference providers in the Graphics Processing Unit Market, though resale values fall quickly once a successor architecture ships.
What compliance checks matter when procuring high-end GPUs?
Buyers should confirm the product's Export Control Classification Number, typically 3A090 or 4A090 for advanced accelerators, plus any end-use licensing obligations. Resellers increasingly require know-your-customer attestations, so procurement teams should budget extra time for cross-border deliveries [8].
How does multi-die design change GPU economics?
Splitting a large processor into smaller dies raises manufacturing yield, because a single defect scraps less silicon. The trade-off is higher advanced-packaging cost and interconnect power, so multi-die designs pay off mainly in premium accelerators rather than mainstream cards.
Will open interconnect standards reshape the Graphics Processing Unit Market?
The UALink Consortium published its 1.0 specification in April 2025, defining an open scale-up fabric linking up to 1,024 accelerators. Wide adoption could reduce lock-in to proprietary interconnects and let operators mix accelerator vendors inside a single pod.
Author
Author Author Profile Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author Co-Author Profile Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.