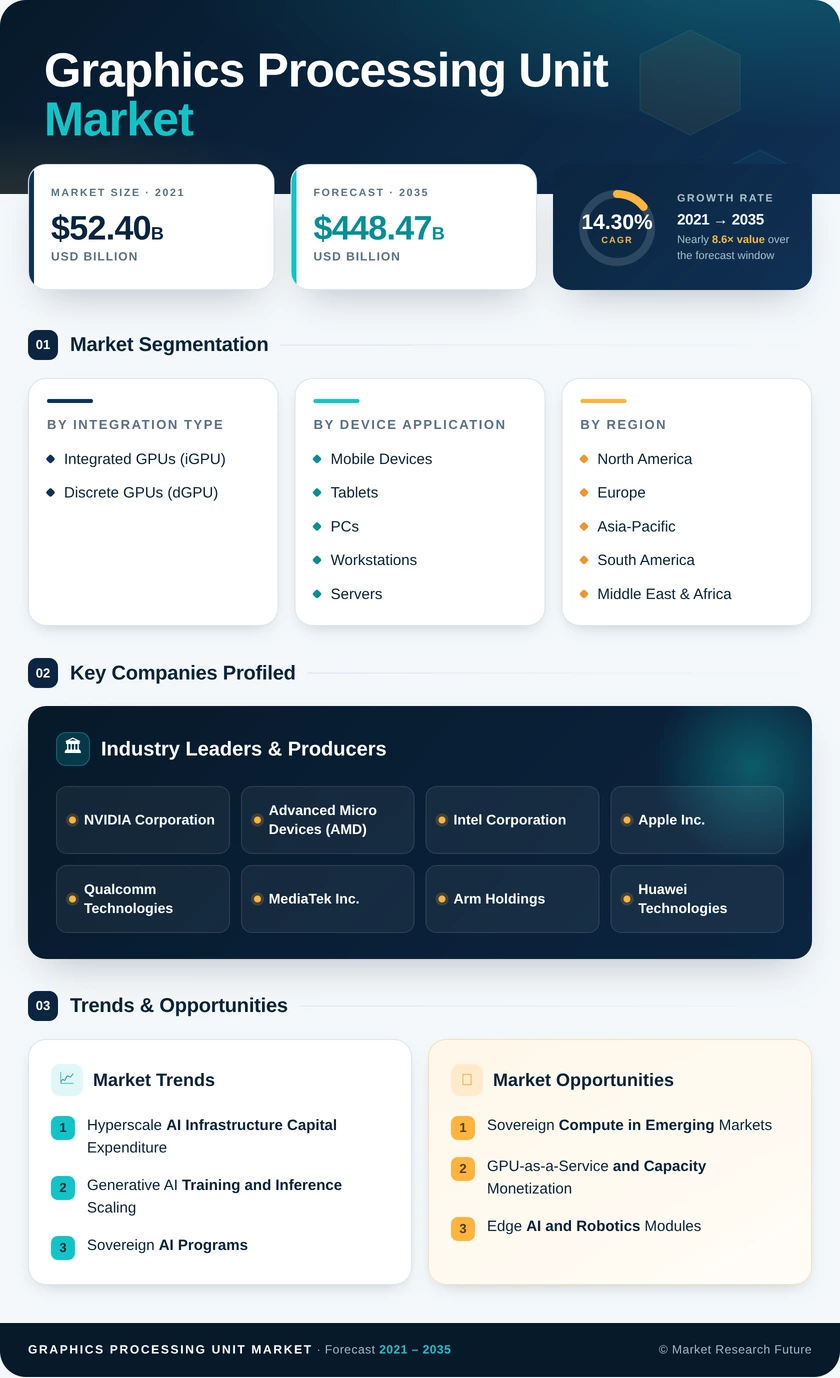
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Integration Type | Integrated GPUs (iGPU); Discrete GPUs (dGPU) | Discrete GPUs (dGPU) — 67.2% share (2025) | Discrete GPUs (dGPU) — 67.2% share (2025); outpaces Integrated GPUs (iGPU) at 12.1% CAGR (2026–2035) |
| By Device Application | Mobile Devices and Tablets; PCs and Workstations; Servers and Datacenter Accelerators; Gaming Consoles and Handhelds; Automotive and ADAS; Other Embedded and Edge Devices | Servers and Data Center Accelerators — 35.9% share (2025) | Automotive and ADAS — 18.6% CAGR (2026–2035) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific — 41.2% share (2025) | Asia-Pacific — 41.2% share (2025) |
Market Segmentation Overview
By Integration Type
| Sub-Segment | Key Trend |
|---|---|
| Integrated GPUs (iGPU) | Larger graphics blocks and unified memory in AI-capable processors |
| Discrete GPUs (dGPU) | HBM capacity and multi-die packaging push accelerator performance |
Discrete GPUs (dGPU) lead with a 67.2% share and remain the faster-growing type, because model training and large-batch inference are bound by HBM bandwidth that only dedicated boards deliver. Integrated GPUs (iGPUs) expand at a 12.1% CAGR as notebook and smartphone processors devote more die area to graphics for local AI—the split favors discrete parts for value and integrated parts for unit reach.
By Device Application
| Sub-Segment | Key Trend |
|---|---|
| Mobile Devices and Tablets | On-device generative AI and console-quality mobile games |
| PCs and Workstations | Windows 10 retirement and AI PC specifications |
| Servers and Data Center Accelerators | Rack-scale AI factories and inference fleets |
| Gaming Consoles and Handhelds | PC-class handhelds and mid-cycle console refreshes |
| Automotive and ADAS | Central vehicle computers for perception and cockpit AI |
| Other Embedded and Edge Devices | Robotics, machine vision and retail inference modules |
Servers and Datacenter Accelerators lead at a 35.9% share as hyperscalers and sovereign buyers operate AI clusters as permanent infrastructure. Automotive and ADAS grow fastest at an 18.6% CAGR, since each autonomy level multiplies inference load on central vehicle computers. Gaming Consoles and Handhelds trail at 8.4% because console generations refresh on long, fixed cycles.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA