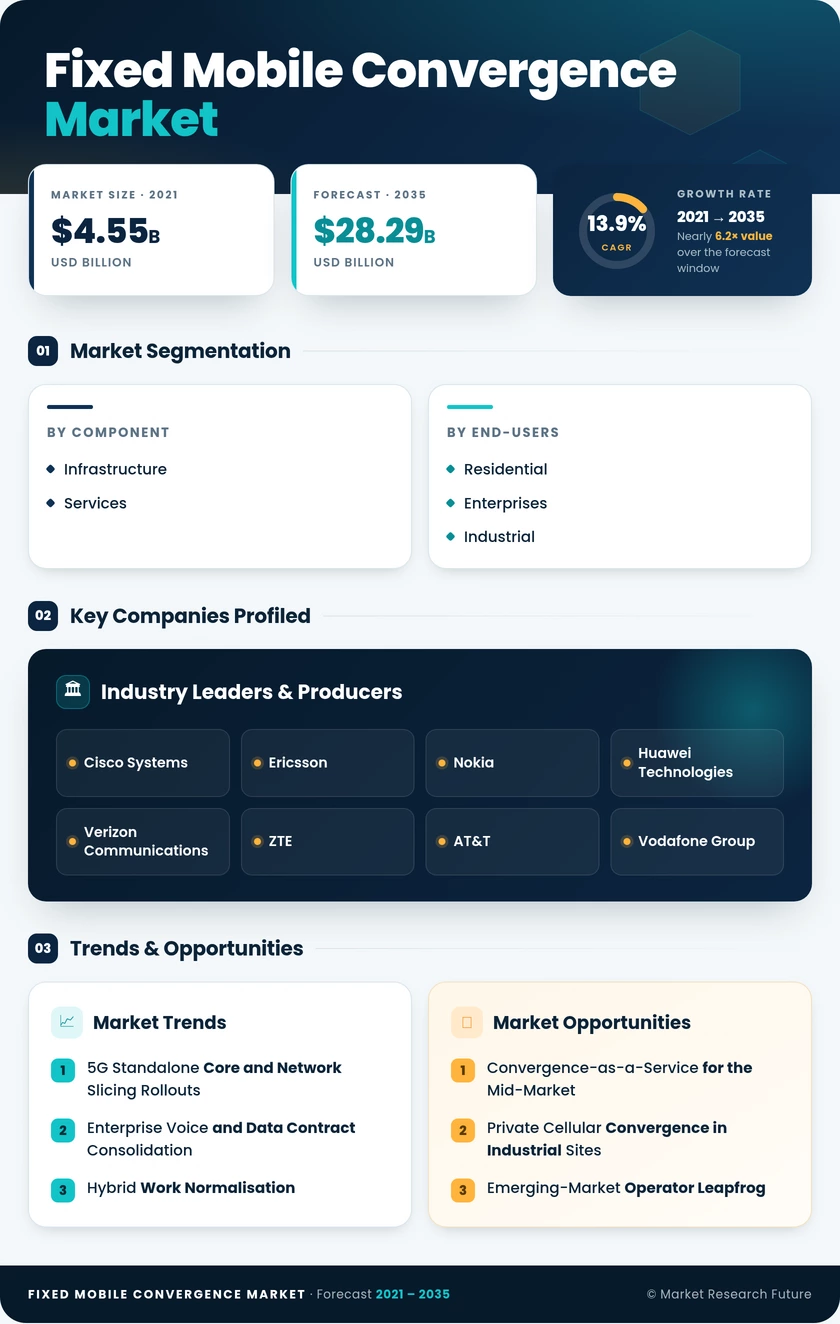
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Infrastructure, Services | Infrastructure (58.4% share, 2025) | Services (15.1% CAGR, 2026–2035) |
| By End-users | Residential, Enterprises, Industrial | Enterprises (48.2% share, 2025) | Industrial (15.6% CAGR, 2026–2035) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Infrastructure | IMS core and session border controller refresh tied to 5G standalone deployment cycles |
| Services | Growth of managed handover, integration, and lifecycle support contracts |
Infrastructure holds the leading position at 58.4% of 2025 revenue because standalone core commissioning and session border controller replacement remain capital-intensive and must precede any enterprise rollout. Services grow fastest at 15.1% CAGR, since policy tuning and multi-site handover management recur annually while hardware purchases do not. The scarcity of engineers fluent in both SIP and mobile core signalling pushes buyers toward outsourced delivery, reinforcing the services trajectory. That mix shift moves margin from equipment vendors toward integrators and carrier professional-services arms.
By End-users
| Sub-Segment | Key Trend |
| Residential | Operator quad-play bundles used to defend household ARPU and reduce churn |
| Enterprises | Consolidation of fixed, mobile, and conferencing contracts into single agreements |
| Industrial | Converged voice layered onto private cellular cores at plants, ports, and campuses |
Enterprises lead at 48.2% share because they combine large seat counts with a quantifiable consolidation case that finance functions approve quickly. Industrial buyers grow fastest at 15.6% CAGR by adding converged voice to private cellular cores already funded for machine connectivity, a marginal-cost argument unavailable to other cohorts. Residential volume stays substantial but expands slowest, constrained by saturated broadband penetration in the European and South American markets where bundling economics work best. Regulated verticals within the enterprise segment command premium pricing owing to call-recording obligations.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA