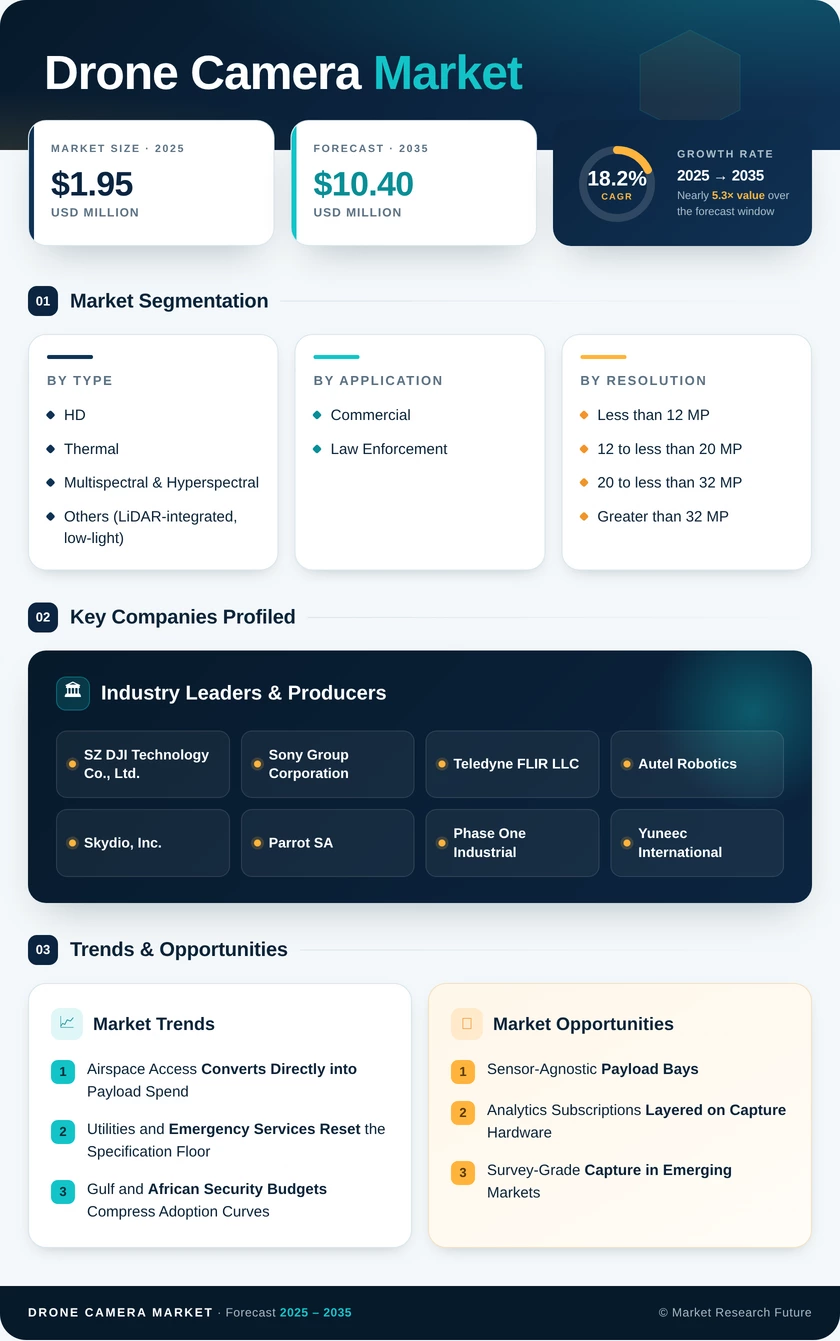
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Camera Type | HD; Thermal; Multispectral & Hyperspectral; Others | HD | Multispectral & Hyperspectral |
| By Application | Photography and Videography; Thermal Imaging; Surveillance; Mapping and Surveying; Others | Photography and Videography | Others (Inspection & Agriculture) |
| By Resolution | Less Than 12 MP; 12 To Less Than 20 MP; 20 To Less Than 32 MP; Greater Than 32 MP | 12 To Less Than 20 MP | Greater Than 32 MP |
| By End User | Commercial; Law Enforcement | Commercial | Law Enforcement |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific | Middle East & Africa |
Market Segmentation Overview
By Camera Type
| Sub-Segment | Key Trend |
| HD | Volume leadership persists, but revenue share erodes as dual-sensor bundles become the enterprise default |
| Thermal | Radiometric output moving from optional upgrade to contractual deliverable in utility and solar inspection |
| Multispectral & Hyperspectral | Subsidised agri-drone fleets and mineral survey pull narrow-band capture into mainstream pricing |
| Others | LiDAR-integrated and low-light modules gain traction in corridor mapping and night operations |
Camera type is the segmentation axis where competitive advantage is decided. Optical performance has largely commoditised at the HD tier, while thermal and analytics-grade capture remain defensible on calibration quality, detector supply and software ecosystem depth.
By Application
| Sub-Segment | Key Trend |
| Photography and Videography | Sustained by prosumer replacement cycles; lowest revenue per unit across the taxonomy |
| Thermal Imaging | Predictive maintenance mandates convert inspection from campaign-based to continuous |
| Surveillance | Highest revenue per unit; specification driven by evidentiary and perimeter-coverage requirements |
| Mapping and Surveying | Cadastral modernisation and construction progress tracking anchor demand |
| Others | Precision agronomy and asset-integrity workflows expand the addressable base fastest |
Application mix explains why headline unit volumes and revenue diverge. A single surveillance or survey payload can carry the revenue of several consumer imaging units, so revenue-weighted analysis materially changes the competitive picture.
By Resolution
| Sub-Segment | Key Trend |
| Less Than 12 MP | Confined to legacy fleets, training airframes and first-person-view applications |
| 12 To Less Than 20 MP | Mainstream commercial inspection sweet spot balancing file size against detail |
| 20 To Less Than 32 MP | Photogrammetry workflows migrate here as processing costs fall |
| Greater Than 32 MP | Precision mapping, cultural heritage and metric survey drive premium pricing |
Resolution tiering increasingly tracks data-processing economics rather than sensor cost. As cloud photogrammetry pricing declines, buyers move up the resolution ladder without a proportionate increase in total workflow expense.
By End User
| Sub-Segment | Key Trend |
| Commercial | Energy, agriculture, construction and media sustain volume across all regions |
| Law Enforcement | Response programmes and evidentiary handling requirements drive specification upward |
End-user dynamics are asymmetric: commercial buyers determine scale while law-enforcement buyers determine the feature roadmap. Requirements originating in policing — signed metadata, audit trails, secure firmware — routinely migrate into commercial product lines within two release cycles.
By Geography
| Sub-Segment | Key Trend |
| North America | Origin-based procurement rules reshape supplier mix without reducing underlying demand |
| Europe | U-space implementation varies by member state, concentrating adoption in early-designating markets |
| Asia-Pacific | Manufacturing depth plus agri-drone subsidy programmes sustain dominance |
| South America | Agribusiness volume with high-value Andean mining survey pockets |
| Middle East & Africa | Fleet-scale security and megaproject procurement delivers the steepest growth curve |
Geographic performance correlates far more strongly with regulatory permissiveness than with economic size. Markets that opened structured beyond-visual-line-of-sight pathways early are compounding payload spend; those that have not remain capped at small, low-specification fleets.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA