Direct Air Capture Market Summary
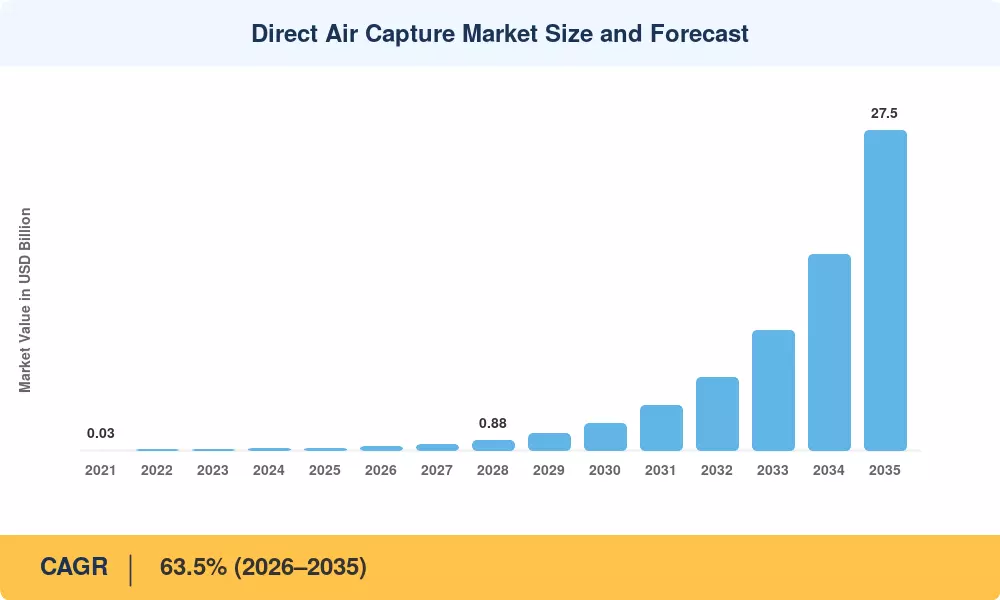
The Direct Air Capture Market reached USD 0.20 billion in 2025 and opens its forecast window at USD 0.33 billion in 2026, climbing to USD 27.50 billion by 2035 at a 63.5% CAGR. That trajectory is not organic demand growth in the conventional sense. It is policy-manufactured demand, anchored by the enhanced 45Q credit in the United States, which pays up to USD 180 per tonne for atmospheric CO₂ routed to saline storage, and by the U.S. Department of Energy's USD 3.5 billion Regional DAC Hubs program [1][3].
This is a rare case of technology substitution, when there is no legacy system to replace. Point source capture machines, attached to flue stacks, deal with concentrated streams of CO2 at 10-15% concentration. Atmospheric capture deals with 420 parts per million. Early plants had to use high-temperature calcium looping at around 900 °C. The market has moved aggressively to amine-functionalised solid sorbents that regenerate at between 80°C and 120°C, which dramatically reduces thermal demand and allows developers to pair units with geothermal, waste heat, or curtailed renewables [2][5].
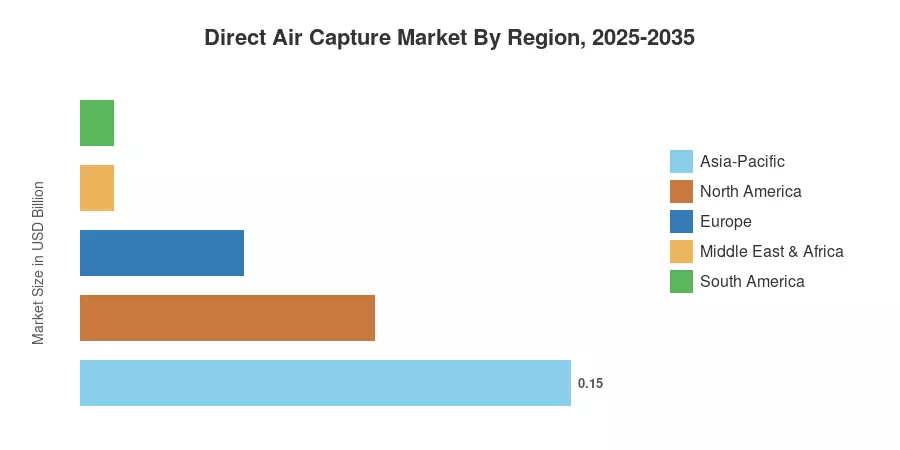
North America represents 42.8% of the Direct Air Capture Market, driven by the prevalence of Class VI storage in Louisiana, Wyoming and North Dakota. Asia-Pacific compounds at 74.8% per annum, driven by Chinese and Indian renewable overbuild, which drives marginal electricity rates to zero at solar peak times. Europe is second, thanks to the EU Carbon Removals Certification Framework. The first to solve affordable heat will set the price floor for the whole decade.
Key Report Takeaways
• By Technology
- Solid sorbent systems (S-DAC) commanded 53.5% of the Direct Air Capture Market in 2025, reflecting lower regeneration temperatures and easier modularisation.
- Membrane-based capture is the fastest-advancing technology class at a 70.9% CAGR through 2035, drawing on semiconductor-adjacent fabrication expertise.
- Liquid solvent platforms generated USD 0.06 billion in 2025 revenue, concentrated in a small number of megatonne-scale projects.
• By Sector
- Carbon sequestration into geological formations absorbed 48.4% of captured volumes in 2025
- Chemical and fertiliser end-users are expanding at a 68.6% CAGR, driven by low-carbon urea and methanol mandates.
- Oil and gas operators represented USD 0.07 billion of 2025 spending across the Direct Air Capture Market.
• By Geography
- North America held a 42.8% share in 2025, supported by mature storage permitting.
- Asia-Pacific is scaling at a 74.8% CAGR to 2035, the steepest regional curve
- Europe contributed USD 0.05 billion in 2025, with Nordic geothermal sites carrying disproportionate weight.
Market Size and Forecast (2021–2035)
The below figures are a combination of plant-level nameplate capacity tracking, validated removal credit registry data from Puro. Earth and Isometric, reported offtake contract values and equipment supplier revenue triangulation. Historical years are reconstructed from commissioned capacity rather than advertised pipelines, which are roughly four times bigger than delivered tonnage [4][16].


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



