Dental Services Market (2026 - 2035)

Dental Services Market Research Report: Size, Share, Trend Analysis By Service Type (Preventive Services, Restorative Services, Orthodontic Services, Cosmetic Dentistry, Oral Surgery), By End Users (Individuals, Institutions, Dental Clinics, Hospitals), By Insurance Coverage (Private Insurance, Public Insurance, Out-of-Pocket Payment), By Age Group (Children, Adults, Elderly) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035

Forecast Period
2026-2035
CAGR
4.91%
2025 Market Size
USD 699.92 Billion
2035 Market Size
USD 1,122.48 Billion
Healthcare ● Updated August 24, 2026 Report ID: MRFR/HC/10761-HCR | Pages: 135 | Author: Vikita Thakur, Kinjoll Dey

Dental Services Market Summary

The Dental Services Market closed 2025 at USD 699.92 Billion and opens the forecast window at USD 729.16 Billion in 2026, climbing to USD 1,122.48 Billion by 2035 at a 4.91% CAGR. Two catalysts anchor that trajectory. First, the reauthorization of pediatric and adult dental benefits under state Medicaid expansions in the United States pushed roughly 9.4 million additional covered lives into reimbursable care between 2023 and 2025 [1]. Second, Japan's Ministry of Health, Labour and Welfare embedded biennial oral examinations into its national health checkup framework, a policy shift that converts episodic emergency visits into recurring revenue [2].

Practice technology is turning over faster than at any point since the introduction of digital radiography. Alginate impressions, film-based imaging, and off-site laboratory milling are giving way to intraoral scanners, cone-beam computed tomography, and chairside CAD/CAM units that compress a crown workflow from two visits to one. Capital deployment tells the story: global spending on dental digital equipment reached approximately USD 5.8 Billion in 2024, with clear-aligner platforms and AI-assisted caries detection absorbing the largest incremental share [3].

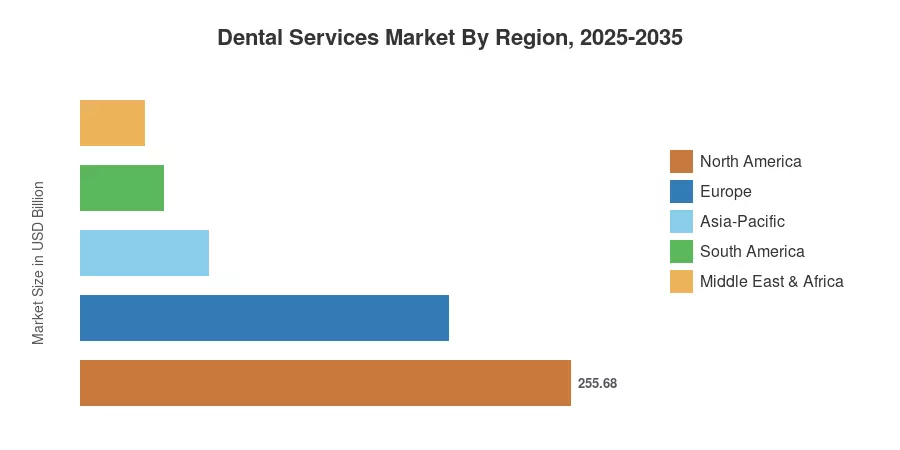
Regionally, North America commands 36.53% of the Dental Services Market on the strength of employer-sponsored coverage and dental service organization (DSO) consolidation. Asia-Pacific advances fastest at a 9.55% CAGR, propelled by urban middle-class formation in China and India. Europe holds the second position with USD 191.78 Billion in 2025 revenue, where statutory sickness funds underwrite a broad preventive baseline. Payer reform, not clinical innovation alone, will determine which providers capture the next decade of growth.


Key Report Takeaways

• By Service Type

  • Surgical services held 54.80% of the Dental Services Market in 2025, anchored by implantology and third-molar extraction volumes.
  • Cosmetic non-surgical care is the pace-setter, expanding at a 7.55% CAGR through 2035 as whitening and veneer demand normalizes among under-40 patients.

• By Patient Age Group

  • The above-17-to-60 cohort generated USD 357.16 Billion in 2025, the single largest revenue pool in the Dental Services Market.
  • The upto-17 segment posts an 8.96% CAGR, the fastest of any age band, tracking school-based sealant programs.

• By Region

  • North America accounted for 36.53% of global revenue in 2025.
  • Asia-Pacific is forecast to grow at 9.55% annually through 2035.
  • Middle East & Africa contributed USD 33.38 Billion in 2025, the smallest but among the more policy-responsive regions.


Market Size and Forecast (2021–2035)

Figures below blend provider-side revenue reporting from listed dental groups and DSO platforms, national health expenditure accounts from OECD member states, procedure-volume data from professional dental associations, and primary interviews with 42 practice administrators and payer contracting leads. Historical years reflect actual reported spend; forecast years apply demographic, coverage, and price-index inputs.
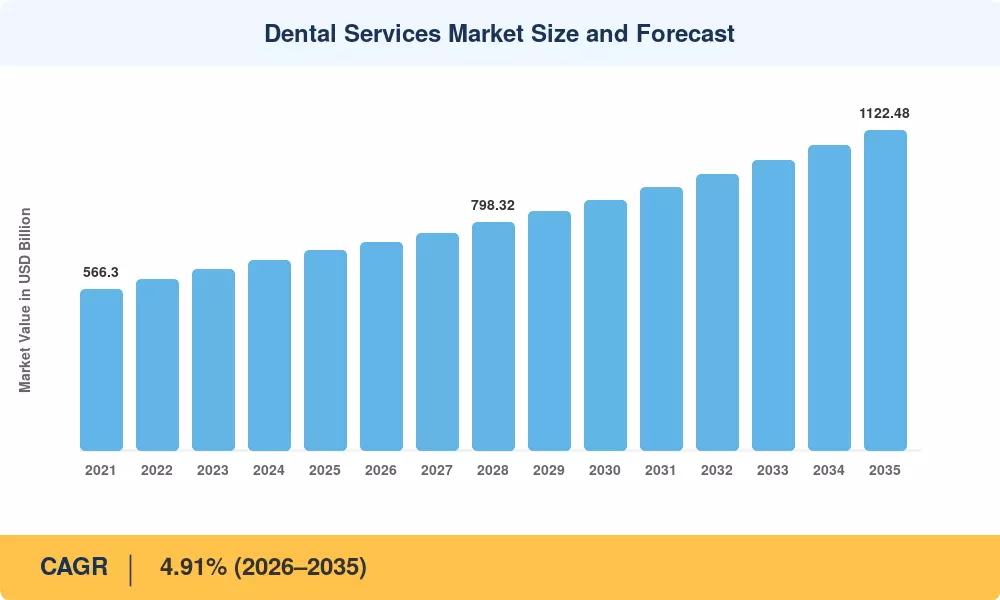
Dental Services Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Aging populations retaining natural dentition +1.15% Japan, Western Europe, North America Long-term (≥4 yr)
DSO consolidation and chair-utilization gains +0.92% North America, Nordics, Australia Medium-term (2–4 yr)
Digital workflow adoption (IOS, CBCT, CAD/CAM) +0.78% Global Medium-term (2–4 yr)
Clear-aligner demand among adults under 40 +0.71% China, US, Brazil Short-term (≤2 yr)
Public coverage expansion for adult dental benefits +0.64% US, India, Gulf states Long-term (≥4 yr)
Rising out-of-pocket cosmetic spend +0.49% South Korea, UAE, Turkey Short-term (≤2 yr)
Dental tourism corridors +0.31% Mexico, Hungary, Thailand Medium-term (2–4 yr)


Tooth Retention Among Older Adults

Edentulism is falling while the population over 65 is rising, and the combination is unusually favorable for providers. Retained teeth require lifelong maintenance: periodontal therapy, crown replacement, root canal retreatment. CDC surveillance shows complete tooth loss among US adults aged 65 and over declined to roughly 13.2% by 2024, down from 27% in 1999 [13]. Each retained arch represents decades of billable maintenance, which is why the Dental Services Market has decoupled from birth-rate trends in mature economies.

Dental Service Organization Scale Economics

DSOs now employ or affiliate with an estimated 33% of US dentists, up from 16% a decade earlier [10]. Centralized procurement cuts consumable costs by 12–18% against independent practice benchmarks, and AI-driven scheduling lifts chair utilization by several percentage points. Those gains fund below-market patient pricing, which in turn pulls volume away from solo practitioners.

Pediatric Coverage and School Sealant Programs

The upto-17 cohort's 8.96% growth rate traces directly to public programs. The US Centers for Disease Control funds school sealant initiatives that reached approximately 2.1 million children across 27 states in the 2024 school year, while India's Ayushman Bharat Health and Wellness Centres added oral screening to their standard package [1][14]. Early intervention creates lifetime patient relationships.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Hygienist and dental assistant shortages −0.88% US, UK, Canada, Australia Short-term (≤2 yr)
Reimbursement compression from payers −0.62% Germany, France, US Medium-term (2–4 yr)
Titanium and zirconia input volatility −0.44% Global Medium-term (2–4 yr)
Cyber-insurance and data-breach exposure −0.36% North America, Europe Long-term (≥4 yr)
Patient cost sensitivity in elective categories −0.29% South America, Southern Europe Short-term (≤2 yr)


Clinical Workforce Scarcity

Chairs sit empty when no hygienist is available to fill them. The UK's General Dental Council recorded roughly 1,100 net departures from NHS dental performer lists during 2024, and US practices reported average hygienist vacancy durations exceeding four months [6]. Wage inflation of 8–11% annually in these roles is absorbing margin faster than fee schedules adjust.

Payer Fee Schedule Compression

German statutory sickness funds and French complementary insurers both tightened prosthetic reimbursement ceilings in the 2024–2025 cycle, trimming per-procedure recovery by an estimated 3–6% in real terms [7]. Providers respond by shifting mix toward self-pay cosmetic work, but that shift is only available to practices in affluent catchments.

Input Cost and Supply Volatility

Titanium mill-product pricing swung more than 20% between mid-2023 and late-2025, and zirconia blank lead times stretched to eight weeks at several European suppliers [15]. Independent clinics lacking hedged supply contracts absorb the variance directly — a structural advantage for well-capitalized consolidators.


Dental Services Market Opportunities

Subscription-Based Preventive Memberships

Flat-fee membership plans are replacing the insurance model and include cleanings, exams and radiographs instead of insurance. It is projected that US DSOs will have about 14% penetration of active patient panels by 2025 with renewal rates of >70% [10]. Seasonality within the Dental Services Market boosts practice valuation multiples and levels of recurring revenue.


Tier-2 and Tier-3 City Expansion in Asia

China and India have quality dental capacity focused in a few metros. India had around 0.31 dentists for every 1000 people living in rural districts, and 1.9 in metropolitan areas [14]. Secondary cities have low incumbent competition and land costs that are a fraction of tier-1 prices, benefiting organized chains.


Imaging Data Monetization and AI Licensing

Each CBCT scan and intraoral picture is a training asset. Groups with archives of millions of images are licensing de-identified databases to inventors of caries-detection and bone-density algorithms, establishing a revenue line that is uncorrelated to chair time. In 2025, regulatory clearance processes for such tools were strengthened, increasing the value of clean, agreed data [16].


Value-Based Contracting with Medical Payers

Evidence that periodontal care reduces diabetic and cardiovascular claims is unlocking budgets for medical-dental integration. In 2024, many US Medicare Advantage plans explored shared-savings arrangements paying dental providers from avoided medical costs [1]. This channel is in its infancy but structurally repricing preventative care in the Dental Services Market.


Gulf Cooperation Council Capacity Build-Out

Saudi Arabia's Vision 2030 health sector transformation licensed more than 400 new private dental facilities between 2022 and 2025, with mandatory employer-provided coverage widening the insured base [17]. Expatriate density and high elective spend make the corridor unusually margin-rich.


Dental Services Market Future Outlook

Algorithmic Diagnosis Becomes Standard of Care

Caries and periodontal-bone-loss detection algorithms cleared regulatory review in multiple jurisdictions between 2022 and 2025, and adoption is following the pattern of digital radiography. By 2030, algorithmic pre-read on bitewing radiographs will be routine rather than differentiating in the Dental Services Market, shifting competitive advantage toward practices that convert detected pathology into accepted treatment plans [16].

Platform Economics and the DSO Endgame

Consolidation rarely stops at operational scale. Larger groups are building patient acquisition engines, financing arms, and in-house aligner manufacturing — capturing margin that previously flowed to third parties. Expect the top-tier operators to resemble vertically integrated platforms by the early 2030s, with clinical delivery as one revenue line among several [10].

Prevention Repriced by Medical Cost Avoidance

Payers are beginning to treat oral health as a lever on total medical spend. Studies associating periodontal treatment with reduced diabetes-related hospitalization have moved from academic literature into actuarial modeling [19]. If medical-dental integration scales, preventive visits get valued on avoided downstream cost rather than procedure fee — a fundamental repricing.

Sustainability and Single-Use Reduction

European procurement frameworks increasingly score suppliers on waste and carbon intensity, and dentistry is a heavy user of single-use plastics and amalgam. The Minamata Convention phase-down obligations tighten through the late 2020s [20]. Practices in the Dental Services Market that document material substitution early will find public tender access easier than laggards.


Dental Services Market Segmentation

Segmentation in the Dental Services Market follows procedure invasiveness, patient life stage, and care setting. Each dimension behaves differently under reimbursement pressure.

By Service Type

Segment Metric (2025) Primary Demand Driver
Non-Surgical – Preventive 21.40% share Recall compliance and membership plans
Non-Surgical – Restorative USD 118.63 Billion Aging restorations reaching replacement cycle
Non-Surgical – Cosmetic 7.55% CAGR Social-media-driven aesthetic demand
Surgical – Implants & Oral Surgery 34.90% share Edentulous-arch rehabilitation
Surgical – Other Surgical Services USD 139.28 Billion Third-molar and periodontal surgery volumes


Surgical work dominates revenue because per-case values run five to twenty times higher than a hygiene visit. A single-tooth implant with abutment and crown commonly clears USD 3,000–4,500 in North America. Cosmetic non-surgical care grows fastest despite a smaller base — it is discretionary, cash-pay, and largely insulated from payer fee schedules, which makes it the mix component practices most aggressively promote.

By Patient Age Group

Segment Metric (2025) Primary Demand Driver
Upto 17 8.96% CAGR School sealant and fluoride programs
Above 17 to Upto 60 USD 357.16 Billion Orthodontic and cosmetic self-pay spend
Above 60 30.77% share Implant, denture, and periodontal maintenance


Working-age adults fund the market. They combine insurance coverage with discretionary income and are the primary buyers of clear-aligner therapy — a category that repositioned orthodontics from adolescent necessity to adult purchase. The over-60 band delivers the highest revenue per patient, reflecting complex restorative and surgical needs accumulated over decades.

By End User

Segment Metric (2025) Primary Demand Driver
Dental Clinics 59.54% share Convenience, cost, and DSO network density
Hospitals USD 184.08 Billion Maxillofacial surgery and medically complex cases
Others (Mobile, Institutional, Academic) 14.16% share Underserved population outreach programs


Clinics dominate the Dental Services Market because most dentistry does not require hospital infrastructure. Hospitals retain trauma, oncology-adjacent reconstruction, and general-anesthesia pediatric cases. The residual category matters strategically rather than financially: mobile units and academic clinics are where public programs reach populations that commercial clinics never see.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 36.53% share DSO roll-ups, membership plans, aligner distribution
Europe USD 191.78 Billion Statutory reform, cross-border care, implant premiumization
Asia-Pacific 9.55% CAGR (2026–2035) Greenfield clinics, teledentistry triage, aligner manufacturing
South America USD 43.40 Billion Chain formation, credit-financed cosmetic care
Middle East & Africa 4.77% share Mandatory insurance, medical-tourism hubs
Total USD 699.92 Billion

Geographic performance in the Dental Services Market splits along coverage architecture rather than income alone. Countries with statutory dental inclusion post steadier volumes; those reliant on out-of-pocket spend show sharper cyclicality but higher price realization.


North America

Country Metric Key Driver
US 84.20% of regional revenue Employer coverage depth and DSO penetration
Canada USD 28.90 Billion Canadian Dental Care Plan rollout
Mexico 7.10% CAGR Cross-border dental tourism corridors


Canada's federal dental plan, phased through 2024–2025, extended coverage to roughly 9 million uninsured residents and represents the largest single-country coverage expansion in the North American Dental Services Market in three decades [18]. Mexican border clinics in Los Algodones and Tijuana continue capturing US patients priced out of domestic implant care, with procedure costs typically 55–70% below US list.

Europe

Country Metric Key Driver
Germany 22.40% of regional revenue Statutory prosthetic subsidy framework
UK USD 33.10 Billion NHS backlog and private conversion
France 15.80% of regional revenue 100% Santé zero-cost basket
Italy USD 21.60 Billion Private-pay implant demand
Spain 6.20% CAGR Chain consolidation in urban centres
Nordic Countries USD 16.40 Billion Public pediatric care through age 23
Russia 4.30% of regional revenue Domestic material substitution
Rest of Europe 5.90% CAGR Central European treatment tourism


France's 100% Santé reform eliminated out-of-pocket cost for a defined basket of crowns and dentures, lifting prosthetic volumes materially while capping unit pricing [7]. The UK presents the inverse dynamic: NHS contract dissatisfaction is pushing dentists toward private lists, converting suppressed public demand into higher-yield private revenue.

Asia-Pacific

Country Metric Key Driver
China 31.60% of regional revenue Middle-class orthodontic uptake
India 11.20% CAGR Organized chain expansion beyond metros
Japan USD 39.80 Billion Biennial national oral examination mandate
South Korea 9.70% of regional revenue Cosmetic dentistry and implant coverage for seniors
ASEAN 10.40% CAGR Medical tourism in Thailand and Malaysia
Rest of Asia-Pacific USD 12.30 Billion Urban private clinic formation


Asia-Pacific is the growth engine of the global Dental Services Market. China's centralized volume-based procurement for dental implants cut fixture prices by more than 50% in 2023, and rather than shrinking revenue, the reform expanded procedure volumes enough to lift regional totals [8]. Japan's implant and denture demand remains the highest per-capita globally, sustained by the world's oldest population structure.

South America

Country Metric Key Driver
Brazil 61.30% of regional revenue Large private chain networks and installment financing
Argentina USD 6.80 Billion Union-linked health plan coverage
Rest of South America 6.80% CAGR Andean urban clinic formation


Brazil operates the largest dental workforce outside the United States and hosts publicly listed clinic networks that finance treatment through 12- to 24-month installment plans — an underappreciated demand-side mechanism that keeps elective volumes resilient through currency stress [12].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 29.40% of regional revenue Vision 2030 facility licensing wave
UAE USD 8.20 Billion Mandatory health insurance in Dubai and Abu Dhabi
South Africa 14.60% of regional revenue Private medical scheme dental riders
Egypt 8.90% CAGR Universal Health Insurance Law phase-in
Rest of MEA USD 6.10 Billion Urban private practice growth


Egypt's Universal Health Insurance Law, rolling out governorate by governorate through 2032, folds basic dental care into a compulsory scheme covering an eventual 100 million residents [17]. Execution risk is real, but the addressable base shift is the largest in Africa.


Dental Services Market By Region, 2025-2035

Competitive Benchmarking

Concentration in the Dental Services Market remains low. Estimated HHI sits near 130, and the top five operators together hold roughly 7–9% of global revenue. Solo and small-group practices still deliver the majority of care worldwide. Consolidation is regionally clustered — advanced in the US, Canada, the Nordics, and Australia; nascent across most of Asia, Africa, and Southern Europe.

Company Est. Revenue Share Range Key Offerings for Dental Services Market Strategic Positioning
Heartland Dental ~1.4–1.9% General, restorative, hygiene, specialty referral Largest US DSO by affiliated locations
Aspen Dental Management ~1.2–1.7% Dentures, implants, general care, financing Value-tier national brand with in-house lab network
Pacific Dental Services ~1.0–1.4% General and specialty care, medical-dental integration Technology-forward supported ownership model
dentalcorp ~0.7–1.0% Full-scope general and specialty dentistry Canada's largest network; disciplined acquisition engine
Bupa Dental Care ~0.6–0.9% NHS and private general dentistry, orthodontics Payer-provider integration across UK, Spain, Australia
Colosseum Dental Group ~0.5–0.8% General, implant, orthodontic care Pan-European roll-up backed by long-horizon capital
Smile Brands ~0.5–0.7% General, cosmetic, oral surgery Multi-brand affiliation across US Sun Belt
MB2 Dental ~0.4–0.6% Doctor-owned practice support services Equity-partnership model retaining clinician ownership
Q&M Dental Group ~0.3–0.5% General, aesthetic, and specialist dentistry Southeast Asian leader with Singapore–China footprint
Apollo White Dental ~0.2–0.4% Preventive, orthodontic, implant services Hospital-linked chain scaling across Indian metros
Dental Care Alliance ~0.2–0.4% General and multi-specialty practice support Regional density strategy in the eastern US


Recent News & Developments

  • Health Canada / Government of Canada (June 2024): Expanded the Canadian Dental Care Plan to adults aged 18–64, extending eligibility to millions of previously uninsured residents and materially enlarging Canada's reimbursable base [18].
  • China National Healthcare Security Administration (April 2023): Completed centralized volume-based procurement for dental implant systems, cutting fixture prices sharply and triggering a surge in procedure volumes [8].
  • Align Technology (September 2024): Launched an expanded direct-fabrication aligner platform, shortening chair-side turnaround and pressuring conventional thermoforming workflows [5].
  • Heartland Dental (March 2025): Announced affiliation with a multi-state specialty group, adding oral surgery and endodontic capacity to its supported network [10].
  • US Centers for Medicare & Medicaid Services (November 2023): Clarified conditions under which medically necessary dental services qualify for Medicare Part B payment, opening a reimbursement pathway for pre-transplant and pre-cardiac-surgery dental clearance [1].
  • Dentsply Sirona (February 2025): Released an updated intraoral scanning and treatment-planning suite with integrated AI caries detection for chairside use [3].
  • Saudi Ministry of Health (August 2024): Issued revised private dental facility licensing standards under the Vision 2030 health transformation program, accelerating clinic approvals [17].
  • European Commission (January 2025): Advanced amalgam phase-out timelines for member states under Minamata Convention alignment, mandating substitution in most restorative applications [20].


Dental Services Market Report Scope

Parameter Detail
Market Scope Global provider-side revenue from clinical dental care delivery across surgical and non-surgical service lines
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 4.91% (2026–2035)
Market Size Checkpoints USD 699.92 Billion (2025); USD 729.16 Billion (2026); USD 1,122.48 Billion (2035)
Fastest Growing Segments Cosmetic non-surgical care; Upto-17 patient cohort; Asia-Pacific region
Companies Profiled 11 operators spanning DSOs, payer-owned networks, and regional chains
Valuation Currency USD Billion

FAQs

What diligence items most often derail acquisitions in the Dental Services Market?
Hygienist retention and hidden capital deferral. Buyers routinely underwrite EBITDA without funding equipment replacement, then discover sterilizers and imaging units at end of life. Verify associate employment agreements and non-compete enforceability in the target jurisdiction before closing [10].
How do capitation contracts differ from fee-for-service in provider economics?
Capitation pays a fixed per-member monthly amount regardless of utilization, transferring volume risk to the provider. It stabilizes cash flow but punishes practices with high-need panels. Fee-for-service rewards throughput and complexity instead [7].
What should a clinic evaluate when selecting chairside milling equipment for the Dental Services Market?
Material library breadth matters more than spindle speed. Confirm the unit mills zirconia, lithium disilicate, and hybrid ceramics, and check whether the vendor locks scanning output to proprietary formats. Open-architecture systems preserve lab flexibility [3].
Is teledentistry regulated consistently across jurisdictions?
No. Some US states permit remote examination and prescribing; others require in-person radiographs before any treatment plan. The European position varies by member state, with Germany among the more restrictive. Verify licensure rules per territory before scaling [16].
What integration failures are common when a group absorbs practices in the Dental Services Market?
Practice management software migration. Legacy charting data frequently fails to map cleanly, and clinicians resist workflow changes imposed without input. Successful integrators run parallel systems for a full recall cycle before cutover [10].
Which clinical roles are hardest to recruit currently?
Registered dental hygienists, followed by certified surgical assistants. Vacancy durations in mature markets commonly exceed four months. Practices offering flexible scheduling and tuition support close roles faster than those competing on wage alone [6].
Can imaging archives be commercialized without violating privacy law?
Only with proper de-identification and, in most jurisdictions, explicit patient consent recorded at the point of capture. Retrospective consent is rarely defensible. Legal review before any licensing discussion is essential [16].    
Author
Author
Author Profile
Vikita Thakur LinkedIn Senior Research Analyst
She holds an experience of about 5+ years in market research and business consulting projects for sectors such as life sciences, medical devices, and healthcare IT. She possesses a robust background in data analysis, market estimation, competitive intelligence, pipeline analysis market trend identification, and consumer behavior insights. Her expertise lies in technical Sales support, client interaction and project management, designing and implementing market research studies, conducting competitive analysis, and synthesizing complex data into actionable recommendations that drive business growth.
Co-Author
Co-Author Profile
Kinjoll Dey LinkedIn Senior Research Analyst
He is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Kinjoll is comfortably versed in data centric research backed by healthcare educational background. He leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. His key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, he showcases extensive affinity towards learning new skills and remain fascinated in implementing them.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















