Dehydrated Food Market (2026 - 2035)

Dehydrated Food Market Size, Share, Industry Trend & Analysis Research Report: By Drying Technology (Spray-Dried, Freeze-Dried, Vacuum-Dried, Drum-Dried, Air- and Sun-Dried), By Product Category (Fruits and Vegetables, Meat and Seafood, Dairy and Eggs, Nutraceutical and Functional Powders, Herbs, Spices and Seasonings), By Nature (Conventional, Organic), By End Use Application (Industrial Packaged Food, Foodservice, Retail), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
ID: MRFR/FnB/39836-HCR 100 Pages Sakshi Gupta Last Updated: September 17, 2026
Dehydrated Food Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.6%
2025 Market SizeUSD 291.5 Billion
2035 Market SizeUSD 551.4 Billion
Key Players
Kerry Group plc
Olam Food Ingredients
Ingredion Incorporated
International Flavors & Fragrances
Symrise AG
Sensient Technologies
Opportunities
  • Continuous Freeze-Drying at Industrial Scale
  • Nutraceutical and Functional Powder Adjacency
  • Africa and ASEAN as Emerging Supply Hubs

Dehydrated Food Market Summary

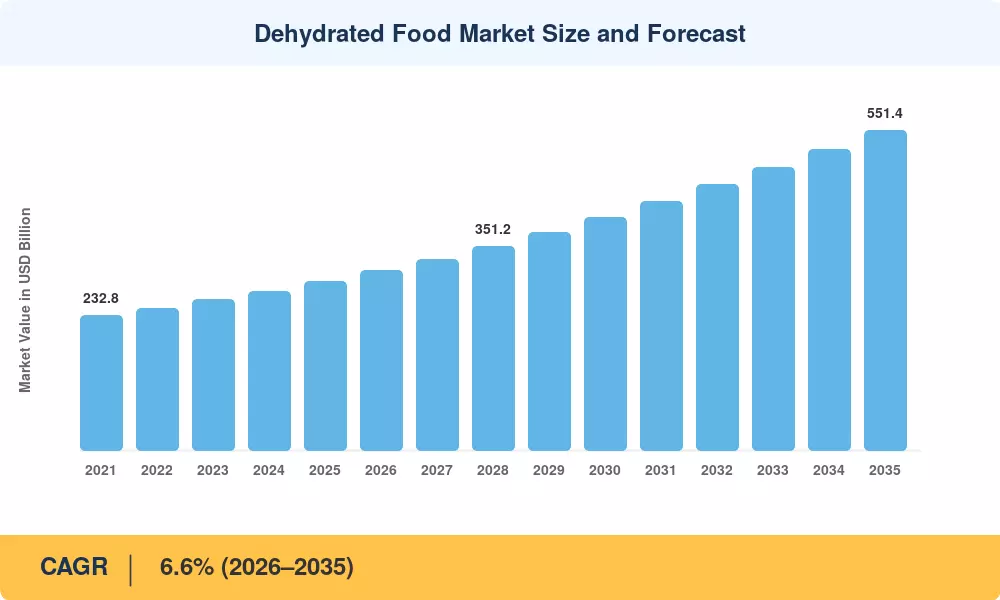
The Dehydrated Food Market was valued at USD 291.5 billion in 2025 and is projected to open the forecast window at USD 309.7 billion in 2026 before reaching USD 551.4 billion by 2035, expanding at a 6.6% CAGR. Two catalysts anchor that trajectory. India's Pradhan Mantri Kisan Sampada Yojana has channeled roughly USD 700 million into cold-chain and processing infrastructure, much of it into drying and powder lines [1]. The European Union's Farm to Fork targets, meanwhile, push processors toward formats that cut post-harvest loss without cold storage [2].

The Dehydrated Food Market is quietly rewriting itself in technology. Energy hogs with uneven moisture profiles are traditional cabinet and tunnel dryers. They are being replaced with hybrid spray-dryers with heat-recovery loops, pulsed vacuum systems and continuous freeze-drying trains. The U.S. Department of Energy estimates that industrial drying accounts for up to 12% of the energy consumed in manufacturing processes, which is exactly why funding keeps flowing into recovery-integrated equipment [3].

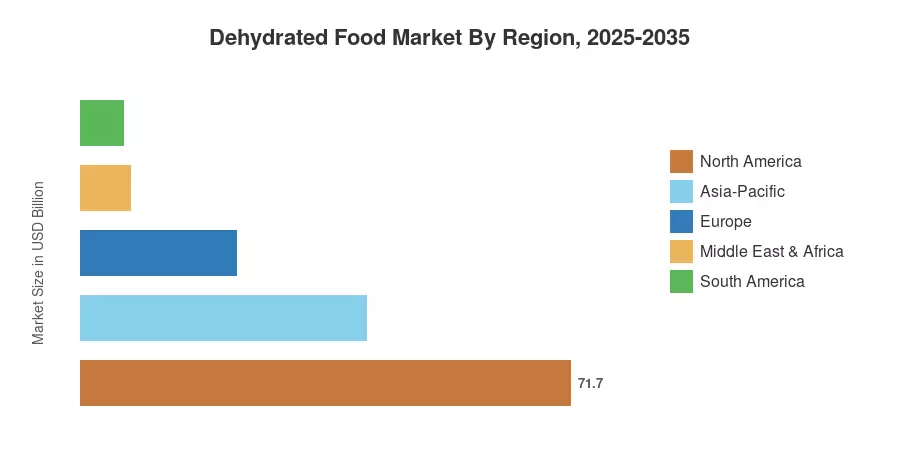
On a regional basis, Asia-Pacific is the largest Dehydrated Food Market, accounting for a 41.9% share and the quickest CAGR of 8.1% during the forecast period, owing to the fruit and vegetable processing base in China and spice-drying clusters in India. North America is second with 24.6%, with outdoor and emergency-preparedness channels supporting premium pricing. Europe is third, defending margins with organic certification, not volume. The processors that combine energy efficiency with clean-label credibility will reap the rewards over the coming decade.


Key Report Takeaways

• By Technology

  • Spray-drying commanded 35.4% of the Dehydrated Food Market in 2025, remaining the throughput workhorse for dairy, egg and botanical powders.
  • Freeze-drying is forecast to advance at a 7.6% CAGR through 2035 as nutrient-retention claims move from niche to mainstream.
  • Vacuum-drying accounted for USD 34.8 billion in 2025, concentrated in heat-sensitive fruit and nutraceutical applications.

• By Sector

  • Fruits and vegetables held 34.0% of the Dehydrated Food Market in 2025, the single largest product category.
  • Nutraceutical and functional powders are projected to grow at a 9.4% CAGR, the fastest of any category.
  • Industrial packaged food end use represented 52.6% of demand in 2025

• By Region

  • Asia-Pacific led with a 41.9% share in 2025
  • North America generated USD 71.7 billion in 2025
  • Middle East & Africa is forecast to expand at a 7.3% CAGR, the strongest among the smaller regions.


Market Size and Forecast (2021–2035)

Historical values were triangulated from national trade statistics, processor capacity filings, and customs-level shipment data for dried fruit, vegetable powder, milk powder and freeze-dried preparations, then reconciled against publicly reported segment revenues from listed ingredient groups. Forecast years apply a demand-side build combining per-capita consumption, processing capacity additions, and price-index adjustments.
Dehydrated Food Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Convenience and shelf-stable meal adoption ~22% Global Short-term (≤2 yr)
Industrial reformulation toward powder inputs ~18% APAC, Europe Medium-term (2–4 yr)
Post-harvest loss reduction programs ~15% APAC, Africa Long-term (≥4 yr)
Clean-label and organic premiumisation ~14% Europe, North America Medium-term (2–4 yr)
Outdoor recreation and emergency preparedness ~12% North America Short-term (≤2 yr)
Energy-efficient drying technology adoption ~11% Global Long-term (≥4 yr)
Cross-border trade liberalisation in dried goods ~8% MEA, South America Medium-term (2–4 yr)


Convenience Demand Meets Urban Density

Urban households are trading cooking time for assembly time, and dried inputs sit precisely at that intersection. UN-Habitat reports that the urban population in Asia exceeds 2.2 billion people, and projections indicate an additional growth of roughly 1.2 billion people by 2050. This structural shift reliably accelerates processed-food intensity per capita. Retail-pack dried vegetables, instant soup bases, and reconstitutable fruit pieces all benefit from this transition. What makes this durable rather than cyclical is packaging economics: a dried format ships at a fraction of the weight of its fresh equivalent, so last-mile delivery margins improve materially.


Post-Harvest Loss Programs Create Supply

India's Ministry of Food Processing Industries reports that roughly 30% of horticultural output is lost between farmgate and consumer, a gap worth close to USD 12 billion annually [1]. Drying capacity is the cheapest structural fix. Subsidy schemes covering 35–50% of capital cost for mechanised dryers have pushed hundreds of small units into formal supply chains, expanding the raw-material base rather than merely redistributing it. Similar logic underpins African Development Bank agro-processing zone funding.

Clean-Label Pressure Reshapes Formulation

European food safety regulations and ongoing reviews under Regulation (EC) No 1333/2008 on food additives continue to tighten parameters for synthetic ingredients, prompting food processors to substitute artificial preservatives with natural alternatives like dried botanical concentrates. Data from the European Commission and the Research Institute of Organic Agriculture (FiBL) indicate that the broader European organic market has steadily rebounded, with total retail sales surpassing €50 billion. Premium pricing models for certified organic and clean-label inputs remain commercially robust, helping sustain long-term producer investments in certified agricultural acreage.


Restraints Impact Analysis

Restraint weightings are directional and reflect analyst assessment of drag on realised growth within the Dehydrated Food Market. They are not subtractive inputs to the published CAGR.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Energy intensity of drying operations ~24% Europe, APAC Short-term (≤2 yr)
Raw-material price and harvest volatility ~21% Global Short-term (≤2 yr)
Nutrient and flavour degradation perception ~17% North America, Europe Medium-term (2–4 yr)
Fragmented food-safety compliance regimes ~15% MEA, South America Long-term (≥4 yr)
Capital barriers to freeze-drying capacity ~13% APAC, Africa Medium-term (2–4 yr)


Energy Costs Squeeze Thin Margins

Drying is thermodynamically expensive, and European processors felt that acutely when industrial gas prices spiked above EUR 100/MWh during 2022–2023 [18]. Even after normalisation, energy represents 20–30% of conversion cost for spray-dried powders. Carbon border adjustment mechanisms add a second layer for importers. Operators without heat-recovery integration face a structural cost disadvantage that no amount of volume growth erases.

Harvest Volatility Passes Straight Through

Dried commodities offer almost no buffer between field and factory. When devastating agricultural frosts struck Turkey's primary producing region of Malatya in April 2025, production yields dropped by over 90% (with regional losses approaching complete failure), triggering immediate, sharp spikes in global export prices within a single quarter. Buyers increasingly demand fixed-price annual contracts that processors cannot reliably hedge, compressing gross margins. Vertical integration into growing regions is the mitigation of choice, but it consumes capital that might otherwise fund technology upgrades.


Dehydrated Food Market Opportunities

Continuous Freeze-Drying at Industrial Scale

Batch freeze-drying has always been the bottleneck — long cycles, high energy, limited throughput. Continuous tray-transfer systems now entering commercial deployment cut cycle time by 30–40% . Processors who install early will capture the 7.6% CAGR freeze-dried segment at a cost base competitors cannot match for several years.

Nutraceutical and Functional Powder Adjacency

Botanical extracts, protein isolates and fruit-derived actives all rely on gentle drying. Global supplement demand growth in the high single digits pulls directly into this capability . Existing spray-drying assets can often be requalified for pharmaceutical-grade output with modest incremental investment, turning a commodity line into a margin engine.

Africa and ASEAN as Emerging Supply Hubs

Vietnam, Indonesia and Kenya combine abundant horticultural output with low post-harvest processing penetration. Trade preference schemes under the African Continental Free Trade Area reduce intra-regional tariffs on processed agricultural goods . First movers who establish drying capacity near source secure both cost advantage and origin-story marketing value in the Dehydrated Food Market.

Traceability Data as a Monetisable Asset

Blockchain-linked batch records covering origin, moisture history and pesticide residue are becoming a purchasing requirement for multinational buyers. Processors that build this layer can license verified provenance data to brand owners as a subscription service rather than absorbing it as a compliance cost. Early pilots in the EU dried-fruit trade suggest buyers will pay 2–4% premiums for audited chains [15].


Dehydrated Food Market Future Outlook

Process Intelligence and Autonomous Drying Control

Machine-vision moisture sensing paired with adaptive control loops is moving from pilot to production. Early industrial deployments report 8–12% energy reduction and materially tighter moisture-variance bands [3]. Over the decade, this becomes table stakes for the Dehydrated Food Market rather than a differentiator, but the transition period will separate operators who invest from those who defer.

Energy Transition Reshapes Cost Curves

The International Energy Agency projects industrial electrification to expand substantially through 2035, and drying is a prime candidate given the maturity of heat-pump and mechanical vapour recompression technology [21]. Processors switching from gas-fired to electrified drying in low-carbon grid regions gain both cost stability and exportable emissions credentials.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
Asia-Pacific 41.9% share Horticultural drying capacity, spice powders, export processing zones
North America USD 71.7 Billion Outdoor meal formats, emergency stock, protein powders
Europe 22.8% share Organic certification, energy retrofit, clean-label reformulation
South America 6.3% share Tropical fruit drying, export logistics
Middle East & Africa 7.3% CAGR Food security reserves, date and legume processing
Total 100.0% —

Geographic performance across the Dehydrated Food Market reflects where raw material, energy cost and consumer willingness-to-pay intersect most favourably.


North America

Country Metric Key Driver
US USD 51.2 Billion Outdoor recreation and preparedness channels
Canada 13.8% of region Pulse and berry drying for export
Mexico 7.4% CAGR Chilli, tomato and avocado powder capacity


The FDA's Food Safety Modernization Act preventive-controls rule established validation requirements for water-activity thresholds that effectively raised the technical bar for small dryers, consolidating volume among larger processors [17]. Federal emergency-preparedness stockpiling contracts add a stable, price-insensitive demand floor for the North American Dehydrated Food Market. Mexico's position is different again — proximity to U.S. buyers plus low energy cost has made it the preferred nearshoring location for vegetable powder lines.

Europe

Country Metric Key Driver
Germany 19.6% of region Industrial ingredient demand from food manufacturers
UK USD 10.1 Billion Retail snacking and meal-kit formats
France 6.3% CAGR Organic fruit processing
Italy 11.1% of region Tomato and herb drying heritage
Spain USD 6.2 Billion Paprika, citrus and vegetable powders
Nordic Countries 6.8% CAGR Berry powders and functional nutrition
Russia 8.4% of region Domestic substitution of imported inputs
Rest of Europe USD 10.1 Billion Contract manufacturing capacity


Europe's story in the Dehydrated Food Market is margin over mass. The EU organic action plan targets 25% of agricultural land under organic management by 2030, which guarantees a widening certified raw-material pool [2]. Processors are pairing that with energy retrofits funded partly through the Innovation Fund. Germany anchors industrial demand; Spain and Italy anchor supply. The tension worth watching is whether carbon border adjustment costs push low-value drying offshore while certified premium lines stay resident.

Asia-Pacific

Country Metric Key Driver
China USD 41.8 Billion Vegetable dehydration and export processing scale
India 9.6% CAGR Spice, onion and garlic drying clusters
Japan 13.1% of region Instant meal and miso ingredient demand
South Korea USD 9.0 Billion Convenience retail and health powders
ASEAN 8.9% CAGR Tropical fruit and coconut processing
Rest of Asia-Pacific 9.8% of region Emerging contract drying capacity


China's dominance rests on Gansu and Shandong dehydration corridors that supply both domestic manufacturers and global buyers. India's Agricultural and Processed Food Products Export Development Authority reports dried onion and garlic exports crossing USD 500 million annually, concentrated in Gujarat and Maharashtra [6]. Government capital subsidies under national food-processing missions continue to underwrite new lines. The Asia-Pacific Dehydrated Food Market grows fastest not because consumption alone is rising but because supply, policy and export demand are moving together.

South America

Country Metric Key Driver
Brazil USD 9.7 Billion Tropical fruit and coffee-adjacent powders
Argentina 21.4% of region Legume and vegetable drying for export
Rest of South America 6.9% CAGR Andean grain and fruit processing


Brazil's Ministry of Agriculture has expanded credit lines for agro-industrial equipment through the Plano Safra, with allocations exceeding BRL 400 billion across the broader agricultural programme [19]. Fruit pulp powders for beverage manufacturing represent the clearest growth vector. Currency volatility remains the persistent complication — it makes imported drying equipment expensive while simultaneously improving export competitiveness, which leaves investment decisions unusually sensitive to timing.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 27.3% of region Strategic food reserve and date processing
UAE USD 2.5 Billion Re-export hub and foodservice demand
South Africa 6.7% CAGR Fruit drying for European export
Egypt 14.7% of region Onion, herb and legume dehydration
Rest of MEA USD 2.1 Billion Emerging processing capacity


Food security policy drives this region more than consumer preference. Saudi Arabia's National Food Security Strategy commits to multi-year strategic reserves, and shelf-stable dried commodities are structurally suited to that mandate [20]. The Gulf Standardization Organization's harmonised food-safety standards have simplified intra-GCC trade, lowering compliance friction for processors serving multiple markets. Egypt's dehydrated onion sector, meanwhile, has become a genuine global supplier rather than a regional one.


Dehydrated Food Market By Region, 2025-2035

Dehydrated Food Market Segmentation

By Drying Technology

Segment Metric Primary Demand Driver
Spray-Dried 35.4% share (2025) Dairy, egg and botanical powder throughput
Freeze-Dried 7.6% CAGR Nutrient retention and premium texture
Vacuum-Dried USD 34.8 Billion Heat-sensitive fruit and actives
Drum-Dried 4.9% CAGR Starch, cereal and infant formula bases
Air- and Sun-Dried 12.6% share Low-cost herb, spice and fruit processing


Spray-drying holds its lead in the Dehydrated Food Market on unit economics alone — no competing method matches its cost per tonne at scale, and the installed base is enormous. Freeze-drying is where the growth narrative lives. Cycle-time improvements and the credibility of freeze-dried food preservation with premium buyers have moved it beyond a niche technique. Vacuum-drying occupies useful middle ground, delivering much of the quality benefit at meaningfully lower capital intensity.

By Product Category

Segment Metric Primary Demand Driver
Fruits and Vegetables 34.0% share (2025) Retail snacking and industrial ingredient use
Meat and Seafood USD 43.2 Billion Shelf-stable protein and pet nutrition
Dairy and Eggs 5.9% CAGR Bakery, confectionery and formula demand
Nutraceutical and Functional Powders 9.4% CAGR Supplement and fortified food growth
Herbs, Spices and Seasonings 11.8% share Seasoning blends and foodservice bases


Fruits and vegetables anchor the Dehydrated Food Market because they serve both retail and industrial channels without reformulation. Nutraceutical powders grow fastest for a different reason: they attach to a supplement industry expanding independently of food-processing cycles, and they carry pharmaceutical-adjacent margins that reward the drying quality investment.

By Nature

Segment Metric Primary Demand Driver
Conventional 80.5% share (2025) Industrial cost sensitivity and volume supply
Organic 14.0% CAGR Certification premiums and retail positioning


Conventional product still carries four-fifths of volume, and industrial buyers optimising for cost will keep it there. Organic's growth rate reflects a small base multiplying quickly against genuine willingness-to-pay in European and North American retail.

By End Use Application

Segment Metric Primary Demand Driver
Industrial Packaged Food 52.6% share (2025) Ingredient inputs for manufactured foods
Foodservice USD 66.8 Billion Kitchen efficiency and inventory reduction
Retail 8.6% CAGR Consumer packs and preparedness stocking


Industrial buyers remain the volume backbone of the Dehydrated Food Market, purchasing powders and flakes as formulation inputs rather than finished goods. Retail grows faster because consumer awareness of dehydrated food shelf life storage has improved markedly, converting an emergency-only category into a routine pantry purchase.


Competitive Benchmarking

Concentration in the Dehydrated Food Market sits in the medium band, with an estimated HHI between 700 and 900 and a top-five combined share of roughly 26–31%. Fragmentation is regional rather than global: large ingredient groups dominate powders and functional actives, while hundreds of specialised regional dryers control fruit, vegetable and spice categories. That structure makes bolt-on acquisition the default growth route.

Company Est. Revenue Share Range Key Offerings for the Dehydrated Food Market Strategic Positioning
Kerry Group plc ~7–10% Spray-dried flavours, savoury bases, functional powders Global taste and nutrition integrator
Olam Food Ingredients (OFI) ~6–9% Dehydrated onion, garlic, tomato, spice powders Vertically integrated from farmgate
Ingredion Incorporated ~5–8% Starch-based and fruit powder systems Texture and clean-label formulation focus
International Flavors & Fragrances ~4–7% Dried botanical extracts, culinary powders Science-led premium ingredients
Symrise AG ~4–6% Dehydrated vegetables, herbs, pet nutrition inputs Diversified across food and pet channels
Sensient Technologies ~3–5% Dried colours, seasonings, dehydrated vegetables Colour and flavour specialisation
Van Drunen Farms ~2–4% Freeze-dried fruits, vegetables, grains Freeze-drying capacity leadership
BCFoods Inc. ~2–4% Air-dried and freeze-dried vegetable ingredients Multi-origin sourcing network
Silva International ~1–3% Dehydrated fruit, vegetable and herb ingredients Custom-blend industrial supplier
Mercer Foods ~1–3% Freeze-dried fruit and vegetable snacks Retail-adjacent premium formats
Harmony House Foods ~1–2% Retail dried vegetable and legume packs Direct-to-consumer preparedness niche


Recent News & Developments


  • Olam Food Ingredients (September 2023): Expanded dehydrated onion and garlic processing in India, adding capacity aimed squarely at European and U.S. industrial buyers [6]
  • European Commission (January 2024): Advanced revisions to organic import equivalency rules, simplifying certification recognition for dried agricultural products from third countries [2]


  • U.S. FDA (July 2023): Issued updated guidance on water activity validation for low-moisture foods, raising documentation requirements for dried ingredient suppliers [17]


  • India MoFPI (February 2025): Approved a new tranche of mega food park and processing cluster funding with explicit dehydration line allocations [1]


Dehydrated Food Market Report Scope

Parameter Detail
Market Scope Global Dehydrated Food Market by drying technology, product category, nature, end use application and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.6% (2026–2035)
Market Size Checkpoints USD 291.5 Billion (2025); USD 309.7 Billion (2026); USD 551.4 Billion (2035)
Fastest Growing Segments Freeze-dried technology; nutraceutical and functional powders; organic nature; retail end use
Companies Profiled 11 major players including Kerry Group, Olam Food Ingredients, Ingredion, IFF, Symrise, Sensient, Van Drunen Farms, BCFoods, Silva International, Mercer Foods, Harmony House Foods
Valuation Currency USD Billion

FAQs

What contract structures reduce raw-material risk when sourcing from the Dehydrated Food Market?
Multi-origin split contracts with quarterly price resets outperform annual fixed-price deals. Buyers increasingly add crop-failure substitution clauses naming an alternative origin. This shifts harvest volatility exposure back toward processors who can hedge it [16].
How should procurement teams evaluate a dryer's technical qualification?
Request water-activity validation records, moisture-variance data across at least three production batches, and microbial kill-step documentation. Suppliers unable to produce batch-level evidence rarely pass multinational audits [17].
Is freeze-drying always the better technology choice in the Dehydrated Food Market?
No. Freeze-drying costs three to five times more per kilogram and only pays back where texture, colour or heat-sensitive actives command a premium. For seasoning bases and industrial powders, spray-drying wins on economics [3].
What regulatory nuance most often delays cross-border shipments?
Pesticide maximum residue limits diverge sharply between EU and Codex standards, and dried products concentrate residues relative to fresh weight. Testing against the destination standard before shipment avoids most detentions [23].
Which emerging application deserves attention from Dehydrated Food Market investors?
Pet nutrition. Premium pet food brands are adopting dried vegetable and protein inclusions at a faster rate than human food categories, and they accept ingredient specifications with fewer certification hurdles [11].
What integration challenge derails reformulation projects most often?
Rehydration behaviour. Dried inputs absorb water at rates that shift downstream viscosity and process timing, so pilot-scale trials must replicate actual line conditions rather than laboratory beakers .
How does the Dehydrated Food Market handle sustainability reporting requirements?
Leading suppliers now issue per-batch emissions factors covering drying energy and transport. Buyers should request these at tender stage, since retrofitting supplier disclosure mid-contract is considerably harder [22].    
Author
Author Author Profile Sakshi Gupta LinkedIn Team Lead - Research
Currently a Team Lead in consumer goods, FMCG, and F&B, she translates rigorous research into decisive strategy. She develops GTM roadmaps, pricing architectures, and competitive benchmarks for companies across Europe, the US, and APAC. She synthesize insights, align cross-functional teams, and drive execution from brief to measurable outcomes. She leads end-to-end engagements with crisp analysis, compelling storytelling, and a strong command of Power BI, Tableau, SQL, and advanced research platforms.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed food science journals, agricultural publications, and authoritative health and food safety organizations. Key sources included the US Food & Drug Administration (FDA), European Food Safety Authority (EFSA), US Department of Agriculture (USDA), Food and Agriculture Organization (FAO) of the United Nations, Codex Alimentarius Commission, National Agricultural Statistics Service (NASS), Agricultural and Processed Food Products Export Development Authority (APEDA) of India, China National Food Industry Association, International Food Information Council (IFIC), Institute of Food Technologists (IFT), Global Food Safety Initiative (GFSI), US Centers for Disease Control and Prevention (CDC) – Food Safety Division, World Health Organization (WHO) – Food Safety Programme, EU Eurostat Agricultural Database, National Institutes of Health (NIH) – Food and Nutrition Research, National Center for Biotechnology Information (NCBI/PubMed) for food preservation studies, International Trade Centre (ITC) Trade Map, UN Comtrade Database, and national agricultural ministry reports from key markets (India Ministry of Food Processing Industries, Brazil Ministry of Agriculture, China Ministry of Agriculture and Rural Affairs). These sources were used to collect production statistics, regulatory approval data, food safety studies, consumer trend analysis, and market landscape analysis for dehydrated fruits, dehydrated vegetables, dehydrated meat, dehydrated seafood, dehydrated herbs, and other processed food technologies across air drying, sun drying, freeze drying, drum drying, and microwave drying methods.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. From dehydrated food manufacturers, food processing equipment suppliers, and OEMs, supply-side sources comprised CEOs, VPs of Product Development, regulatory affairs chiefs, quality assurance directors, supply chain managers, and commercial directors. Demand-side sources included procurement leaders from food and beverage companies, retail category managers, food service operators, restaurant chain executives, hotel and hospitality procurement leads, outdoor recreation retailers, emergency preparedness distributors, and import/export traders. Market segmentation was validated, product pipeline timelines were confirmed, and insights regarding processing technology adoption patterns, pricing strategies, shelf-life optimization, distribution channel dynamics, and export-import regulations were gathered through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and production volume analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across dehydrated fruits, dehydrated vegetables, dehydrated meat, dehydrated seafood, dehydrated herbs, and other specialty categories

Technology mapping across air drying, sun drying, freeze drying, drum drying, and microwave drying processing methods

Analysis of reported and modeled annual revenues specific to dehydrated food portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (production volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations across food and beverage industry, retail, food service, and household end-use segments, with further granularity by online, supermarkets, convenience stores, and specialty store distribution channels

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















