Copra Meal Market (2026 - 2035)

Copra Meal Market Size, Share, Industry Trend & Analysis Research Report By Livestock Type (Ruminants (Dairy & Beef), Poultry, Swine, Aquaculture, Others (Equine, Pet)), By Form (Pellets, Expeller Cake / Chunks, Powder / Mash), By Nature (Conventional, Organic), By Distribution Channel (Direct Mill-to-Feed Manufacturer, Traders & Distributors, Online & Commodity Platforms), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035

ID: MRFR/Agri/39861-HCR 128 Pages Snehal Singh Last Updated: September 17, 2026
Copra Meal Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.75%
2025 Market SizeUSD 3.75 Million
2035 Market SizeUSD 5.97 Million
Key Players
Primex Coco Products Inc.
Celebes Coconut Corporation
PT Global Coconut
Greenville Agro Corporation
Cargill Incorporated
SC Global Coco Products
Opportunities
  • Contaminant-Certified Premium Grades
  • Middle East Dairy Import Substitution
  • African Smallholder Feed Market Entry

Copra Meal Market Summary

The Copra Meal Market was valued at USD 3.75 Million in 2025 and opens the forecast horizon at USD 3.93 Million in 2026, advancing to USD 5.97 Million by 2035 at a CAGR of 4.75% between 2026 and 2035. Two catalysts anchor that trajectory. The Philippine Coconut Authority's Coconut Farmers and Industry Trust Fund, capitalised at roughly PHP 75 billion under Republic Act 11524, is funding replanting and mill modernisation across 3.6 million hectares of coconut land . Alongside it, Indonesia's Ministry of Agriculture has committed to rehabilitating more than 120,000 hectares of senile palm annually, directly lifting crushable copra volumes [2].

Processing economics are shifting underneath the Copra Meal Market. Sun-dried, smoke-kiln copra — long the default in smallholder supply chains — is giving way to mechanically dried, solvent-assisted and double-press expeller lines that cut residual oil from 8–10% down to 3–5% and sharply reduce aflatoxin incidence. The Asian and Pacific Coconut Community estimates that upgraded drying and storage infrastructure across member states will absorb close to USD 410 million in public and private capital through 2030 . Buyers are paying for that consistency.

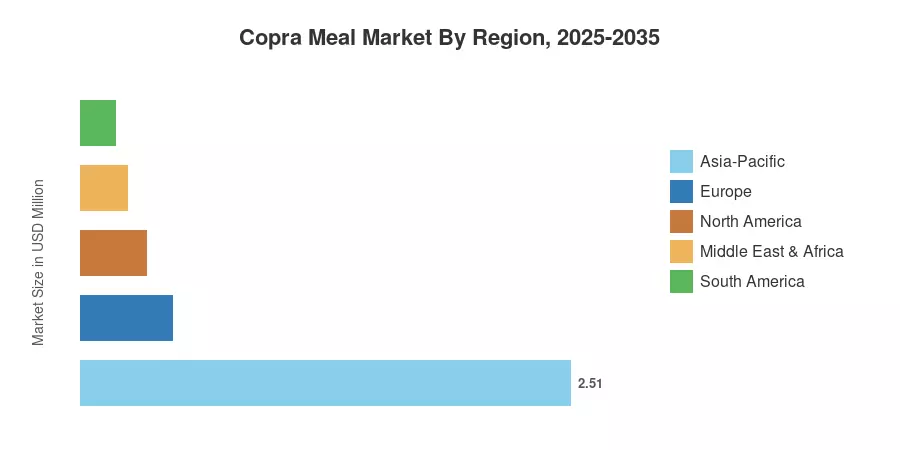
Asia-Pacific dominates the Copra Meal Market with a 67.0% share, drawing on the Philippines, Indonesia and India, which together crush the bulk of world copra. The same region grows fastest, compounding at 5.3% through 2035 as domestic aquafeed and dairy demand absorbs tonnage once destined for export. Europe holds 12.5%, sustained by non-GMO compounding mandates in Germany and the Netherlands. Expect the Copra Meal Market to reward processors who can certify contaminant thresholds rather than simply ship volume.


Key Report Takeaways

• By Livestock Type

  • Ruminant and dairy feed commands 41.5% of the Copra Meal Market, the largest single consumption block
  • Aquaculture feed is the fastest-expanding application at a 6.1% CAGR through 2035

• By Form

  • Pelletised copra meal accounted for USD 1.61 Million in 2025 revenue
  • Expeller cake and chunk formats grow at 3.9% CAGR, constrained by handling losses

• By Region

  • Asia-Pacific holds 67.0% of the Copra Meal Market in 2025
  • Europe posts a 4.4% CAGR, tied to certified non-GMO protein sourcing
  • Middle East & Africa represents USD 0.24 Million of 2025 demand


Market Size and Forecast (2021–2035)

Figures below are triangulated from customs-level trade records, national crushing statistics published by producing-country agriculture ministries, and a bottom-up build of compound feed inclusion rates across dairy, poultry, swine and aqua rations. Volume data was converted at annual average FOB prices for Philippine and Indonesian origin material, then cross-checked against importer declarations. The Copra Meal Market series below reflects merchant-traded tonnage only; on-farm captive use is excluded.
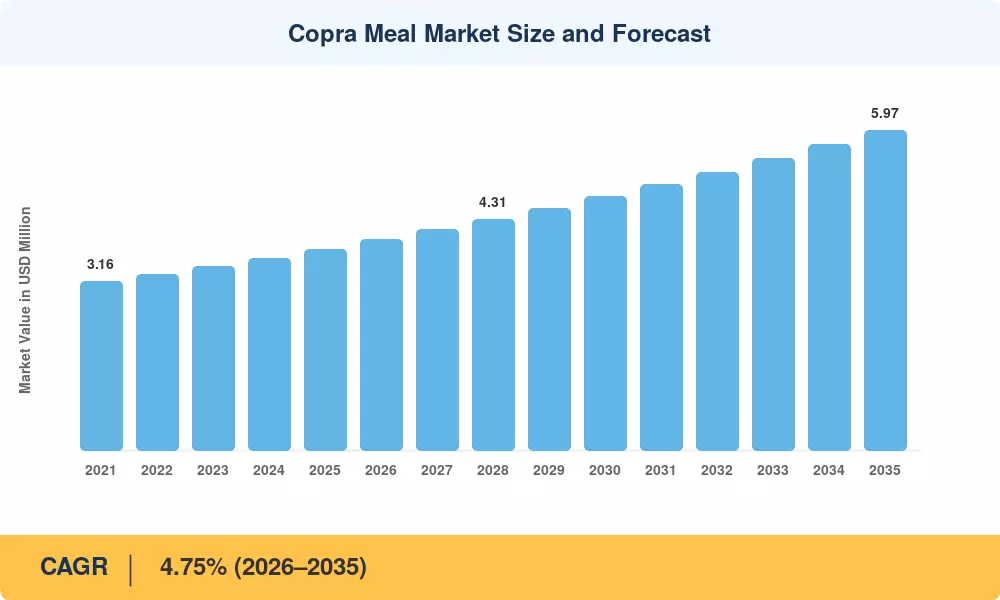
Copra Meal Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Expanding global ruminant and dairy herds +0.9 Asia-Pacific, MEA Medium-term (2–4 yr)
Price arbitrage against soybean meal +0.8 Global Short-term (≤2 yr)
Rising coconut oil crushing volumes +0.7 Asia-Pacific Medium-term (2–4 yr)
Aquafeed and swine compound feed growth +0.6 Asia-Pacific, South America Long-term (≥4 yr)
Non-GMO and clean-label feed sourcing +0.5 Europe Long-term (≥4 yr)
Tariff-free feed ingredient access in GCC +0.4 Middle East Short-term (≤2 yr)
Pelletising and mycotoxin-control upgrades +0.3 Global Long-term (≥4 yr)


Livestock Herd Expansion Anchors Baseline Demand

The Copra Meal Market's most resilient demand driver is still herd increase. According to the Food and Agriculture Organization's 2023 statistical report, the world's cattle inventory increased by about 1.4% year over year. The OECD-FAO Agricultural Outlook predicts that global milk production will increase by 1.6% annually until 2033, with more than half of that increase coming from India and Pakistan [12][15]. Both economies are close to the copra supply and already incorporate 8–15% of the meal into buffalo and crossbred dairy meals. Measurable protein-meal tonnage is pulled behind each additional million tons of milk.


Soybean Meal Spreads Reward Substitution

Spread economics, not sentiment, is activated by feed formulators. According to USDA Economic Research Service data, Philippine-origin copra expeller cake traded in a USD 175–215 per ton FOB band, while US Gulf soybean meal averaged above USD 380 per ton for the whole of 2024 [13]. Even after adjusting for reduced lysine content with synthetic amino acids, the disparity of well over USD 150 per ton makes partial substitution appealing. The rest is handled by least-cost formulation software, which automatically increases inclusion whenever the spread exceeds about USD 120 per ton.


Crushing Capacity Modernisation in Producing Nations

Supply-side investment is finally catching up with demand. Indonesia's replanting allocation and the Philippine Coconut Authority's mill retrofit grants have together supported more than 60 desiccating and expelling facility upgrades since 2023, according to Asian and Pacific Coconut Community reporting . Modern lines deliver meal with tighter moisture control below 10% and free fatty acid consistency that importers in Japan and South Korea specify contractually. Consistency, more than raw availability, is what unlocks premium contracts.

Aquafeed Formulations Open a New Demand Channel

Shrimp and tilapia producers across Vietnam, Indonesia, and Ecuador have been substituting fishmeal under sustained price pressure. The FAO notes global aquaculture production surpassed capture fisheries for aquatic animal food supply, a structural shift that expands the addressable base for plant-protein meals [14]. Copra meal enters these rations at modest 5–8% inclusion, yet the sheer scale of aquafeed volume makes even a low ratio commercially meaningful for exporters.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Aflatoxin and mycotoxin contamination risk −0.7 Global export channels Short-term (≤2 yr)
Low lysine and methionine profile caps inclusion −0.6 Global Long-term (≥4 yr)
Ageing palm stock and stagnant copra output −0.5 Asia-Pacific Medium-term (2–4 yr)
Bulk freight volatility on long-haul routes −0.4 Europe, MEA Short-term (≤2 yr)
Substitution by palm kernel expeller and DDGS −0.4 Global Medium-term (2–4 yr)


Contamination Thresholds Gate Export Access

The industry's ongoing liability is aflatoxin B1. Aflatoxin B1 is capped at 20 µg/kg for the majority of supplemental feed products under European Union feed laws; shipments that exceed this limit are rejected and notified via the Rapid Alert System [8]. Smoke-kiln drying, which is still common among smallholders, increases the danger of mold and polycyclic aromatic hydrocarbons. A significant portion of production is locked out of the highest-value destinations until mechanical hot-air drying replaces kiln methods at scale. Instead, it clears into domestic livestock channels at lower costs.


Amino Acid Profile Limits Monogastric Use

In terms of nutrition, the product is inferior to soybean meal. Lysine content is close to 0.6% of dry matter, or about a fifth of soybean levels, while crude protein usually varies from 20–22% compared to 44–48% in soybean meal [16]. High crude fiber—typically 12–15%—further limits its incorporation to single digits in layer and broiler diets. Crystalline lysine and methionine can be used by formulators to make corrections, but this expense partially negates the raw price advantage and effectively caps the addressable share of monogastric diets.


Senile Palm Stock Constrains Raw Material

Roughly a third of the Philippine coconut population exceeds 60 years of age, well past peak bearing, and replanting rates have historically trailed senescence . Because a newly planted palm takes six to eight years to reach commercial yield, today's replanting investment does not translate into crushable copra until the early 2030s. That lag imposes a hard ceiling on near-term supply elasticity regardless of how strong demand signals become.


Copra Meal Market Opportunities

Contaminant-Certified Premium Grades

Japanese and Korean compound feed customers are paying USD 25–40 per ton incentives to processors who can reliably record aflatoxin levels below 15 µg/kg and moisture levels below 10%. One way to turn a compliance cost into a pricing lever is to incorporate third-party laboratory certification into standard shipping documents.


Middle East Dairy Import Substitution

Following Saudi Arabia's import limitations on water-driven feed, Gulf dairy businesses are diversifying away from their reliance on concentrated alfalfa and soybeans [7]. Copra meal is a good supplemental energy-protein source, especially for integrated dairies in the United Arab Emirates and Oman, due to its tolerance in high-forage ruminant feeds.


African Smallholder Feed Market Entry

Coastal East Africa — Tanzania, Mozambique and Kenya — combines growing poultry and dairy sectors with domestic coconut production that is currently underutilised for feed. Establishing small-scale expeller units near existing copra collection points could serve regional demand without incurring ocean freight, an emerging-market gap that remains largely unaddressed.

Traceability Data as a Commercial Product

Blockchain-linked or QR-coded batch provenance — origin farm cluster, drying method, laboratory results — is becoming a saleable service layer rather than a cost centre. Exporters bundling verified batch data into supply contracts are negotiating longer tenors and firmer offtake commitments, monetising information alongside tonnage.

Co-Product Valorisation Beyond Feed

Coconut protein concentrates and dietary fibre isolates extracted from defatted meal address human nutrition and pet food segments at multiples of feed-grade pricing. Pilot lines in India and Sri Lanka have demonstrated technical feasibility; commercial scale-up is the remaining hurdle.


Copra Meal Market Future Outlook

Precision Nutrition and Formulation Analytics

Near-infrared spectroscopy at mill intake is moving from optional to standard, allowing real-time crude protein, fibre and oil residue readings that feed directly into least-cost formulation engines. This matters disproportionately for variable-quality ingredients — the Copra Meal Market has historically been discounted precisely because buyers priced in uncertainty. Faster analytical feedback narrows that discount and lets formulators lift inclusion rates with confidence.

Circular Processing and Zero-Waste Coconut Mills

Integrated facilities that recover coconut shell for activated carbon, husk for coir, water for beverages, and meal for feed spread fixed costs across multiple revenue lines. The International Trade Centre notes that value-added coconut product exports have grown faster than raw copra trade, restructuring mill economics [20]. Meal becomes a stabilising by-product rather than the primary margin driver.

Carbon and Deforestation-Free Sourcing Scrutiny

EU Deforestation Regulation compliance obligations, phasing in for covered commodities, have raised the documentation bar across all imported agricultural inputs. Coconut is not currently a listed commodity, which gives copra-derived meal a temporary procedural advantage over palm-derived alternatives in European feed chains [21]. Buyers hedging regulatory exposure are quietly building this into supplier scorecards.

Climate Volatility and Origin Diversification

Typhoon exposure in the Philippines and drought cycles in Indonesia create correlated supply shocks that importers increasingly hedge by qualifying secondary origins in Papua New Guinea, Sri Lanka and the Solomon Islands. The Copra Meal Market should see origin concentration ease modestly through 2035 as buyers accept slightly higher landed costs in exchange for supply continuity.


Regional Market Share Analysis

Region Metric Primary Investment Themes
Asia-Pacific 67.0% share Mill modernisation, aquafeed integration, replanting
Europe 12.5% share Non-GMO certification, contaminant testing infrastructure
North America USD 0.34 Million Organic dairy rations, specialty pet food inputs
South America 4.9% CAGR Shrimp feed formulation, port-side blending
Middle East & Africa 6.5% share Dairy import substitution, regional expeller units
Total USD 3.75 Million (2025) —

The Copra Meal Market is geographically lopsided by construction — production, processing, and the largest consuming herds all cluster within a narrow tropical band. That concentration creates both pricing efficiency and single-origin risk for importers.


North America

Country Metric Key Driver
US 71.0% of region Organic and non-GMO dairy ration demand
Canada 4.6% CAGR Specialty ruminant and equine feed blends
Mexico USD 0.06 Million Coastal aquaculture and swine finishing diets


North American demand is niche but high-value. USDA National Organic Program rules bar synthetic amino acid supplementation in certified organic poultry diets, which pushes organic formulators toward a broader palette of natural protein sources including coconut-derived meals [18]. Volumes remain small relative to Asia, yet realised prices run materially above commodity levels. Canadian buyers, meanwhile, source through US Gulf and West Coast entry points rather than importing directly, which understates true Canadian consumption in customs data.

Europe

Country Metric Key Driver
Germany 24.0% of region Non-GMO dairy compounding standards
UK 15.5% of region Ruminant blend formulation flexibility
France 4.3% CAGR Organic livestock sector expansion
Italy 11.0% of region Buffalo dairy ration inclusion
Spain USD 0.05 Million Intensive pig and dairy operations
Nordic Countries 4.6% CAGR Sustainability-linked sourcing policies
Russia 6.0% of region Domestic dairy herd rebuilding
Rest of Europe 12.0% of region Port-side blending in Netherlands and Belgium


Rotterdam and Hamburg function as the region's clearing houses, with material blended and redistributed rather than consumed at point of entry. Germany's VLOG non-GMO certification scheme now covers a substantial share of the country's fluid milk supply, and copra meal qualifies without the identity-preservation costs attached to segregated soy [10]. European Feed Manufacturers' Federation reporting shows compound feed output holding near 148 million tonnes annually, a stable base into which incremental substitution can occur [19].

Asia-Pacific

Country Metric Key Driver
China 18.5% of region Swine herd reconstitution and dairy scale-up
India 21.0% of region Buffalo dairy and domestic crushing capacity
Japan USD 0.21 Million Premium contaminant-certified imports
South Korea 5.5% CAGR Compound feed import diversification
ASEAN 34.0% of region Origin production plus captive aquafeed use
Rest of Asia-Pacific 8.0% of region Pacific island copra exports


Asia-Pacific is where the Copra Meal Market is made. The Philippines and Indonesia supply the majority of internationally traded tonnage, while India's Coconut Development Board data shows domestic production increasingly diverted to value-added coconut products, tightening copra availability for crushing . China's swine sector rebuild after African Swine Fever restored a large protein-meal appetite, though inclusion rates in Chinese diets remain conservative. Vietnam and Thailand sit in the middle — both origin and consumer — with aquafeed mills absorbing local production before it reaches export channels.

South America

Country Metric Key Driver
Brazil 58.0% of region Aquaculture and dairy ration diversification
Argentina 4.5% CAGR Feedlot supplementary protein
Rest of South America USD 0.04 Million Ecuadorian shrimp feed formulation


Ecuador's shrimp industry, the world's largest by export value, is the region's most interesting demand pocket. Sustained fishmeal price inflation has pushed formulators toward blended plant-protein packages in which copra meal serves as a fibre and energy contributor rather than a primary protein source [14]. Brazil's own abundant soybean supply limits substitution incentive, so growth there concentrates in specialty and organic segments rather than mainstream compound feed.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 29.0% of region Fodder import policy and dairy self-sufficiency
UAE 22.5% of region Integrated dairy and re-export trade
South Africa 5.2% CAGR Commercial dairy and poultry compounding
Egypt USD 0.03 Million Buffalo dairy and subsidised feed programmes
Rest of MEA 24.0% of region East African coastal processing potential


Saudi Arabia's phased restriction on water-intensive green fodder cultivation forced dairy operators into structural import dependence, and the Kingdom's feed subsidy framework covers several imported protein and energy ingredients [7]. Jebel Ali's re-export function amplifies UAE trade volumes well beyond domestic consumption. Sub-Saharan opportunity remains largely theoretical until reliable drying and storage infrastructure is established near coastal copra production zones.


Copra Meal Market By Region, 2025-2035

Copra Meal Market Segmentation

By Livestock Type

Ration economics determine where tonnage lands, and within the Copra Meal Market, ruminants absorb the largest share because their rumen microbiota handle high-fibre inputs efficiently.

Segment Metric Primary Demand Driver
Ruminants (Dairy & Beef) 41.5% share Fibre tolerance and milk fat response
Poultry 22.0% share Cost substitution at low inclusion rates
Swine 19.5% share Grower-finisher diet energy contribution
Aquaculture 6.1% CAGR Fishmeal replacement in shrimp and tilapia feed
Others (Equine, Pet) USD 0.13 Million Specialty and organic formulations


Dairy remains the anchor. Field trials across South and Southeast Asia have repeatedly shown copra meal inclusion at 10–20% of concentrate maintaining or slightly improving milk fat percentage, which matters commercially in markets where milk is priced on fat and solids-not-fat [16]. Aquaculture is the growth story rather than the volume story — inclusion rates stay modest, but the segment's absolute expansion outpaces every other channel, and shrimp feed millers in Ecuador and Vietnam are actively qualifying new suppliers.

By Form

Physical format drives handling cost and shipping density more than nutrition, and buyers in the Copra Meal Market increasingly specify pellets contractually.

Segment Metric Primary Demand Driver
Pellets USD 1.61 Million Bulk handling efficiency and reduced dust loss
Expeller Cake / Chunks 3.9% CAGR Legacy small-mill output and local trade
Powder / Mash 26.5% share Direct compound feed line integration


Pelletisation adds roughly USD 12–18 per tonne in processing cost but recovers more than that through improved container fill, lower shrinkage and reduced fumigation frequency. Chunk-format cake persists mainly in domestic Philippine and Indonesian trade where buyers collect from mills directly and handling distances are short.

By Nature

Segment Metric Primary Demand Driver
Conventional 93.0% share Cost-led mainstream compound feed
Organic 6.4% CAGR Certified organic dairy and pet food chains


Organic certification is where copra meal livestock nutrition claims translate into pricing power, particularly in European and North American organic dairy where synthetic amino acid supplementation is prohibited. Certification costs and audit burden keep the segment small, but per-tonne realisations run 45–70% above conventional.

By Distribution Channel

Segment Metric Primary Demand Driver
Direct Mill-to-Feed Manufacturer 47.0% share Volume certainty and specification control
Traders & Distributors USD 1.28 Million Origin aggregation and credit provision
Online & Commodity Platforms 7.2% CAGR Price transparency and spot procurement


Direct Mill-to-Feed Manufacturer remains the dominant distribution channel, accounting for 47.0% share, supported by direct sourcing, cost efficiency, and established supply relationships. Traders & Distributors represent a significant channel with USD 1.28 million in value, while Online & Commodity Platforms are the fastest-growing segment, expanding at a 7.2% CAGR as digital procurement and commodity trading gain adoption.


Competitive Benchmarking

Fragmentation defines the Copra Meal Market. Our estimated Herfindahl-Hirschman Index sits near 640, indicating an unconcentrated structure, with the top five participants accounting for roughly 28–33% of merchant-traded value. Thousands of village-scale expeller units feed into a middle layer of regional consolidators, and only a handful of players operate integrated crush-to-export platforms with laboratory certification capability. Scale advantage comes from quality assurance and logistics control rather than production volume.

Company Est. Revenue Share Range Key Offerings for Copra Meal Market Strategic Positioning
Primex Coco Products Inc. ~7–10% Pelletised and cake-format copra meal Integrated Philippine crush and export
Franklin Baker Company ~6–9% Defatted meal from desiccated coconut lines Co-product optimisation model
Celebes Coconut Corporation ~5–8% Expeller meal, certified export grades Contaminant certification leader
PT Global Coconut ~4–7% Bulk meal and pellets Indonesian origin scale
Greenville Agro Corporation ~4–6% Feed-grade meal and coconut oil Diversified coconut portfolio
Cargill Incorporated ~3–6% Blended compound feed incorporating copra meal Global formulation and distribution reach
Louis Dreyfus Company ~3–5% Origination and bulk trading Trade finance and freight optimisation
SC Global Coco Products ~2–5% Organic and conventional meal grades Certification-focused niche
Tantuco Enterprises Inc. ~2–4% Expeller cake and pellets Long-standing Philippine exporter
Mahathi Coconuts ~2–4% Indian-origin meal and value-added derivatives Domestic market specialisation


Recent News & Developments

  • Philippine Coconut Authority (March 2024): Released expanded Coconut Farmers and Industry Development Plan disbursement guidelines covering mill equipment grants, easing capital access for expeller upgrades .
  • Asian and Pacific Coconut Community (September 2024): Published harmonised quality guidelines for traded copra and copra meal covering moisture, free fatty acid and aflatoxin thresholds across member states .
  • Indonesia Ministry of Agriculture (January 2025): Confirmed continuation of the coconut replanting subsidy programme with expanded hectarage targets in Sulawesi and North Sumatra [2].
  • Cargill (July 2024): Expanded aquafeed formulation capacity in Vietnam, increasing regional demand for alternative plant-protein and fibre ingredients [22].
  • Coconut Development Board, India (November 2023): Launched cluster-based processing incentives aimed at raising domestic value addition from coconut and copra streams .
  • European Commission (June 2024): Reaffirmed maximum aflatoxin B1 limits for feed materials under existing directive framework, sustaining testing obligations on tropical oilseed meal ingredient imports [8].
  • Sri Lanka Coconut Development Authority (February 2025): Announced export facilitation measures for coconut by-products including meal, targeting diversification beyond desiccated coconut [11].
  • Saudi Arabia Ministry of Environment, Water and Agriculture (October 2024): Extended feed import support mechanisms for licensed dairy operators, broadening the qualifying ingredient list [7].


Copra Meal Market Report Scope

Parameter Detail
Market Scope Global merchant-traded copra meal, expeller cake, pellets and powder for animal feed applications
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 4.75% (2026–2035)
Market Size Checkpoints USD 3.75 Million (2025); USD 3.93 Million (2026); USD 5.97 Million (2035)
Fastest Growing Segments Aquaculture (livestock type); Online & commodity platforms (channel); Asia-Pacific (region)
Companies Profiled 10 leading participants across origination, processing and trading
Valuation Currency USD Million
Publisher Market Research Future

FAQs

What contractual specifications should procurement teams insist on when buying into the Copra Meal Market?
Fix moisture below 10%, crude fibre ceiling at 14%, aflatoxin B1 below 20 µg/kg, and residual oil under 6%. Require third-party analysis at load port, not destination, with rejection rights attached [8].
How does copra meal compare with palm kernel expeller for ruminant feeding?
Copra meal carries slightly higher crude protein and better palatability; palm kernel expeller offers lower cost and wider availability. Most formulators blend both rather than choosing one [17].
What are the main integration challenges when adding copra meal to existing feed mill lines?
Bulk density variability disrupts volumetric dosing, and higher oil residue can gum conveyors. Mills typically need weigh-based batching and more frequent cleaning cycles [16].
Which certifications materially improve resale value in the Copra Meal Market?
GMP+ FSA and organic certification deliver the clearest premiums, followed by non-GMO verification for European buyers. Certification typically pays back within two shipping seasons [19].
How should investors assess counterparty risk among Copra Meal Market suppliers?
Prioritise exporters with owned drying facilities rather than pure aggregators, since quality control ends at the drying stage. Verify laboratory accreditation and three years of rejection history .
Are there emerging non-feed applications worth tracking?
Defatted coconut protein concentrate for pet food and coconut fibre for prebiotic ingredients are the two credible adjacencies. Both remain at pilot scale but carry substantially higher realisations [20].
What hedging tools exist for buyers exposed to price volatility?
No exchange-traded contract exists, so buyers rely on fixed-price forward contracts and correlation hedges against soybean meal futures. Basis risk remains meaningful and should be sized conservatively [23].    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of agricultural databases, commodity trade publications, peer-reviewed journals, and authoritative food and agriculture organizations. Key sources included the Food and Agriculture Organization of the United Nations (FAO), United States Department of Agriculture (USDA), Coconut Development Board (CDB) - India, Philippine Coconut Authority (PCA), Indonesian Ministry of Agriculture, Malaysian Palm Oil Board (MPOB), International Coconut Community (ICC), United States Food and Drug Administration (FDA), European Food Safety Authority (EFSA), Association of American Feed Control Officials (AAFCO), European Feed Manufacturers' Federation (FEFAC), International Feed Industry Federation (IFIF), World Bank Commodity Markets, International Monetary Fund (IMF) Commodity Price Data, UN Comtrade Database, OECD-FAO Agricultural Outlook, and national agricultural statistics departments from key coconut-producing regions. These sources were utilized to collect production and trade statistics, regulatory frameworks, nutritional research data, price trends, and supply chain analysis for copra meal across animal feed, fertilizer, food industry, and cosmetic applications.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, managing directors of copra processing facilities, heads of procurement, and commercial directors from enterprises that extract coconut oil, produce animal feed, and trade agricultural commodities were examples of supply-side sources. Livestock nutritionists, feed formulators, procurement managers from dairy and poultry farms, makers of organic fertilizer, chiefs of R&D in the cosmetics sector, and sustainability executives from large food corporations were examples of demand-side sources. Primary research verified coconut oil extraction, kernel, and husk sourcing channels, validated market segmentation across powder, pellets, and granule forms, and collected information on pricing dynamics, regional adoption patterns, and nutritional content preferences (high fiber, high protein, low fat).

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (28%), Europe (22%), Asia-Pacific (42%), Rest of World (8%)


Market Size Estimation

Global market valuation was derived through production volume mapping and revenue analysis across the value chain. The methodology included:

Identification of 60+ key manufacturers and processors across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across animal feed, fertilizer, food industry, and cosmetic applications with granular analysis of powder, pellet, and granule forms

Analysis of reported and modeled annual revenues specific to copra meal portfolios, including by-product utilization from coconut oil extraction

Coverage of manufacturers and cooperatives representing 75-80% of global market share in 2024

Extrapolation using bottom-up (production volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches, cross-referenced with FAO and USDA production statistics to derive segment-specific valuations for high fiber, high protein, and low fat nutritional variants

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















