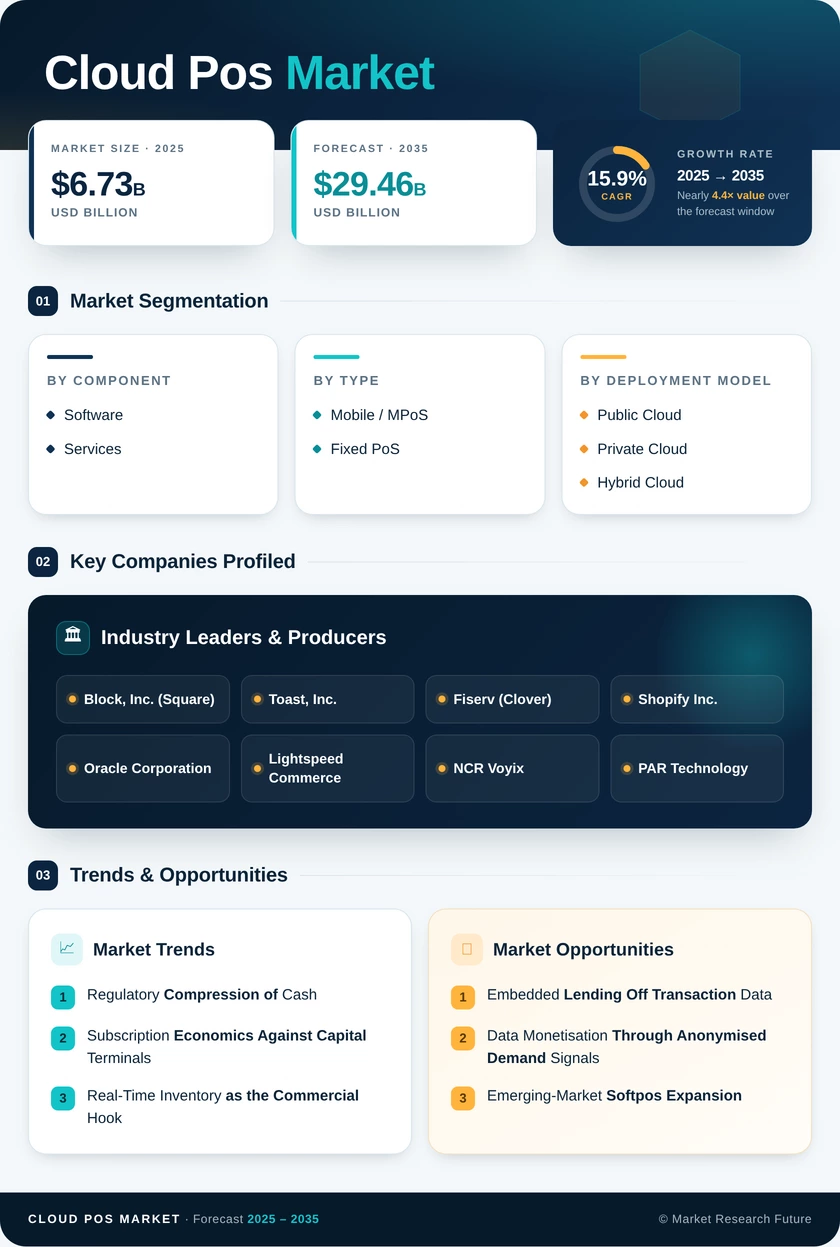
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Software; Services | Software | Services |
| By PoS Type | Fixed PoS; Mobile / MPoS | Mobile / MPoS | Mobile / MPoS |
| By Deployment Model | Public Cloud; Private Cloud; Hybrid Cloud | Public Cloud | Hybrid Cloud |
| By Organization Size | Small and Medium Enterprises (SMEs); Large Enterprises | Small and Medium Enterprises (SMEs) | Large Enterprises |
| By End-User Industry | Retail and Consumer Goods; Hospitality and Restaurants; Healthcare; Entertainment and Leisure; Transportation and Logistics; Others | Retail and Consumer Goods | Healthcare |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Software | Module attach — payroll, loyalty, scheduling — lifts revenue per location well above base subscription |
| Services | Managed configuration and integration outsourcing rises as multi-location estates standardise |
Value has migrated decisively from the counter device to the subscription layer. Vendors now treat hardware as a customer acquisition cost, sometimes free on multi-year commitments, and defend margin through software breadth.
By PoS Type
| Sub-Segment | Key Trend |
| Fixed PoS | Retained in grocery, pharmacy, and high-throughput lanes needing scale and age-verification integration |
| Mobile / MPoS | Handhelds and tablet-based cloud POS solutions dominate hospitality, pop-up retail and queue-busting deployments |
Portability changed the deployment calculus. Once a handheld could run the full catalogue and take payment anywhere in the venue, the fixed lane stopped being the default and became a considered choice.
By Deployment Model
| Sub-Segment | Key Trend |
| Public Cloud | Default for SMEs on cost and provisioning speed |
| Private Cloud | Enterprise estates with bespoke ERP and loyalty integration |
| Hybrid Cloud | Residency-driven split between local transaction storage and central analytics |
Regulatory geography now dictates architecture. Jurisdictions mandating local storage of payment data have made hybrid the pragmatic answer for vendors serving both compliance officers and merchandising teams.
By Organization Size
| Sub-Segment | Key Trend |
| Small and Medium Enterprises (SMEs) | Self-service onboarding and bundled financing sustain volume growth |
| Large Enterprises | Legacy estate replacement drives faster percentage growth off a smaller base |
Long-tail merchants supply the volume; enterprise conversions supply the momentum. Enterprise deals close slowly but replace hundreds of sites at once, which is why growth rates diverge from share.
By End-User Industry
| Sub-Segment | Key Trend |
| Retail and Consumer Goods | Single-ledger inventory enabling cloud POS for omnichannel retail fulfilment |
| Hospitality and Restaurants | Delivery aggregator and kitchen display integration lift revenue per location |
| Healthcare | Co-pay collection and dispensing records converge into one workflow |
| Entertainment and Leisure | Ticketing and concession systems merge onto shared platforms |
| Transportation and Logistics | Mobile fare and freight collection on connected endpoints |
| Others | Education, public sector and professional services adoption |
Vertical specialisation is now the primary competitive axis. Generalist platforms win on price and breadth; specialists win on workflow fit, and healthcare remains the most contestable vertical of the coming decade.
By Geography
| Sub-Segment | Key Trend |
| North America | Highest software attach rates and embedded lending penetration |
| Europe | Compliance-forced upgrades under e-invoicing and instant payment rules |
| Asia-Pacific | Account-to-account rails redefine acceptance software requirements |
| South America | Instant payment ubiquity and inflation-driven repricing needs |
| Middle East & Africa | E-invoicing mandates and mobile money merchant conversion |
Regional demand is diverging in character, not just in pace. Mature markets buy depth; emerging markets buy access — and platforms that cannot serve both economics will find their addressable base narrowing after 2030.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA