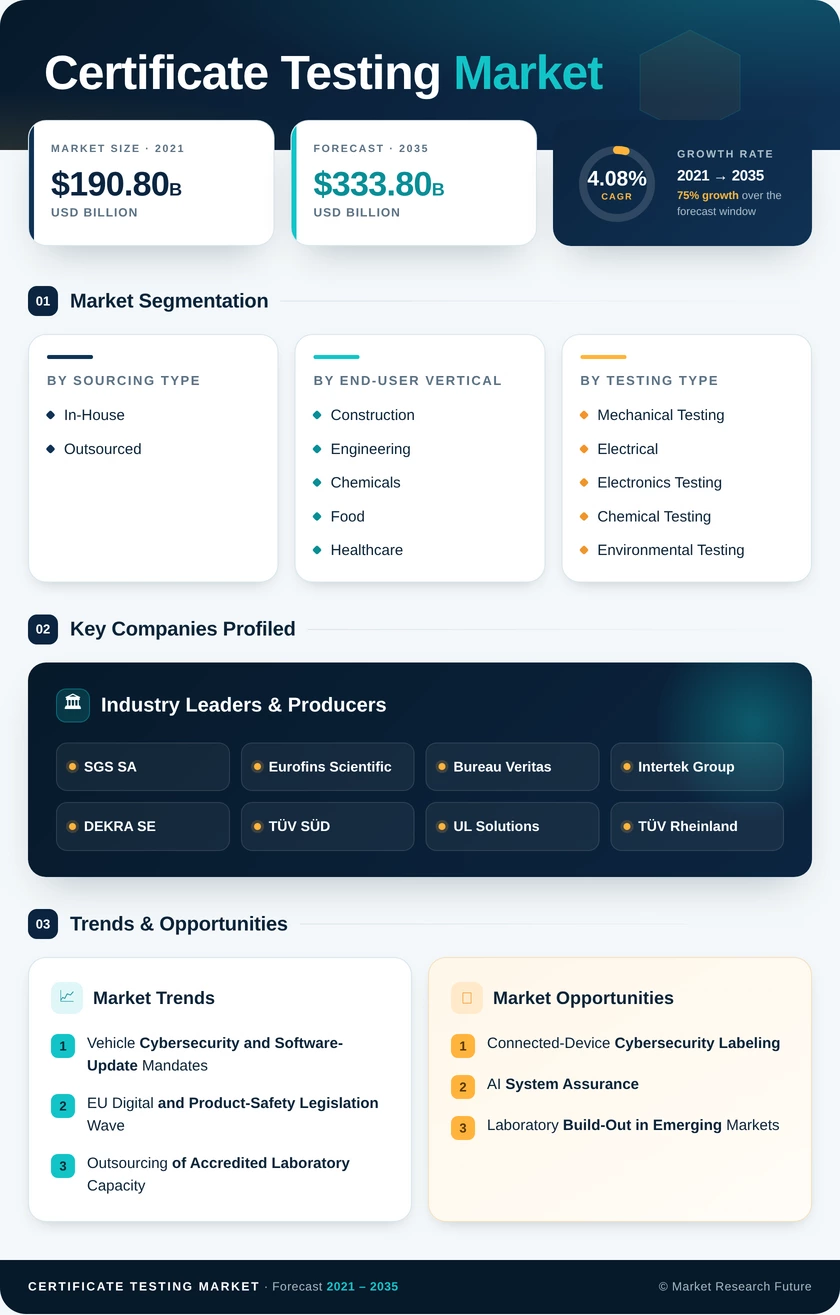
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Sourcing Type | In-House, Outsourced | Outsourced (67.4% share) | Outsourced (67.4% share) |
| By End-User Vertical | Construction and Engineering, Chemicals, Food and Healthcare, Energy and Commodities, Transportation, Other End-User Verticals | Food and Healthcare (30.1% share) | Transportation (5.66% CAGR (2026–2035)) |
| By Testing Type | Mechanical Testing, Electrical and Electronics Testing, Chemical Testing, Environmental Testing, Software and Cybersecurity Testing, Other Testing Types | Electrical and Electronics Testing (42.6% share) | Software and Cybersecurity Testing (5.39% CAGR (2026–2035)) |
| By Certification Type | Product Certification, Management System Certification, Service Certification, Personnel Certification | Product Certification (49.3% share) | Management System Certification (6.02% CAGR (2026–2035)) |
| By Service Type | Testing, Certification | Testing (55.8% share) | Certification (5.02% CAGR (2026–2035)) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific (36.4% share) | Asia-Pacific (36.4% share) |
Market Segmentation Overview
The overview below condenses the key trend for each sub-segment of the Certificate Testing Market, in the same order as Section 9.
By Sourcing Type
| Sub-Segment | Key Trend |
|---|---|
| In-House | Retained for early screening and IP-sensitive work |
| Outsourced | Absorbing accredited volume as captive labs close |
Outsourced providers lead and also grow fastest, because accreditation upkeep, equipment recalibration and staff qualification are cheaper when spread across many clients. In-House laboratories remain relevant in pharmaceuticals and semiconductors, where protecting formulations and process data outweighs cost, yet even these firms increasingly send peak and specialist volumes outside.
By End-User Vertical
| Sub-Segment | Key Trend |
|---|---|
| Construction and Engineering | Materials and structural testing tied to infrastructure budgets |
| Chemicals | Substance registration and hazard classification work |
| Food and Healthcare | Traceability and pharmaceutical quality audits |
| Energy and Commodities | Grid equipment, mining and fuel quality testing |
| Transportation | Cybersecurity, software-update and battery approvals |
| Other End-User Verticals | Consumer goods, textiles and industrial equipment |
Food and Healthcare leads because audits recur at every stage from farm to pharmacy and quality rules are non-negotiable. Transportation grows fastest as UN R155 and R156 add cybersecurity and software-update approvals to every vehicle type, while battery safety protocols multiply test hours per model. Energy and Commodities and Construction and Engineering follow infrastructure and grid investment cycles.
By Testing Type
| Sub-Segment | Key Trend |
|---|---|
| Mechanical Testing | Steady demand from construction, aerospace and medical parts |
| Electrical and Electronics Testing | Safety and EMC marks gating powered product launches |
| Chemical Testing | Restricted-substance and contaminant screening |
| Environmental Testing | Thermal, humidity and vibration qualification for batteries and electronics |
| Software and Cybersecurity Testing | Penetration and update validation under new mandates |
| Other Testing Types | Photometric, acoustic and specialty methods |
Electrical and Electronics Testing leads since nearly every powered product needs safety and electromagnetic compatibility approval before launch. Software and Cybersecurity Testing grows fastest, driven by vehicle cyber regulations, the Cyber Resilience Act and IoT labeling programs that require penetration testing and update-policy review. Environmental Testing gains support from battery qualification protocols.
By Certification Type
| Sub-Segment | Key Trend |
|---|---|
| Product Certification | CE, CCC and FCC marks as hard entry gates |
| Management System Certification | Integrated ISO audits driven by investor and buyer demands |
| Service Certification | Schemes for hospitality, logistics and IT services |
| Personnel Certification | Qualification of welders, inspectors and auditors |
Product Certification leads because a mark is legally required before goods reach shelves in most major economies. Management System Certification grows fastest as suppliers pursue ISO 9001, ISO 14001, ISO 45001 and ISO/IEC 27001 credentials, frequently audited together in one integrated cycle. Service Certification and Personnel Certification contribute smaller, steady revenue.
By Service Type
| Sub-Segment | Key Trend |
|---|---|
| Testing | Equipment-intensive laboratory work facing commodity price pressure |
| Certification | Bundled audits and recurring surveillance contracts |
Testing leads on revenue because each product, batch or design change requires fresh samples and laboratory time. Certification grows faster since multi-standard audit bundles lock in multi-year surveillance fees and raise switching costs for clients. Specialist testing in 5G EMC and battery thermal runaway still commands premium pricing within the Testing line.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA