Certificate Testing Market Summary
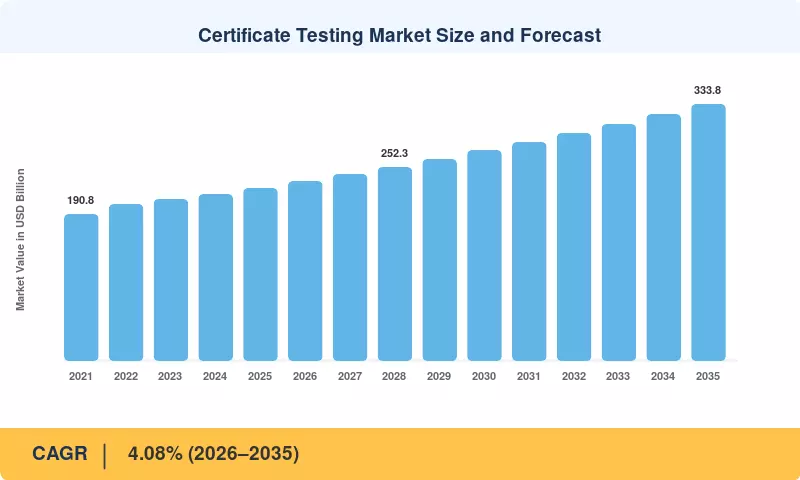
The Certificate Testing Market was valued at USD 223.8 billion in 2025. It is forecast to reach USD 232.9 billion in 2026 and USD 333.8 billion by 2035, a CAGR of 4.08% over 2026–2035. Two regulatory catalysts anchor that path. UN Regulation 155 became mandatory for every new vehicle registered in the European Union in July 2024. The EU Cyber Resilience Act, in force since December 2024, will require security assessments for connected products sold in the bloc from December 2027 [3][4]. Both rules turn voluntary checks into recurring, billable work.
Delivery models are shifting underneath the headline growth. Paper-based audits, captive factory labs and single-standard inspections are giving way to outsourced ISO/IEC 17025 networks, remote witnessing, digital certificates and integrated audits that cover several management standards in one cycle. The International Accreditation Forum's recognition arrangement now spans more than 100 economies, so one accredited conformity assessment can support access to many markets [2]. UL Solutions, listed on the New York Stock Exchange in April 2024, has prioritized battery and cybersecurity capacity in its capital spending [9].
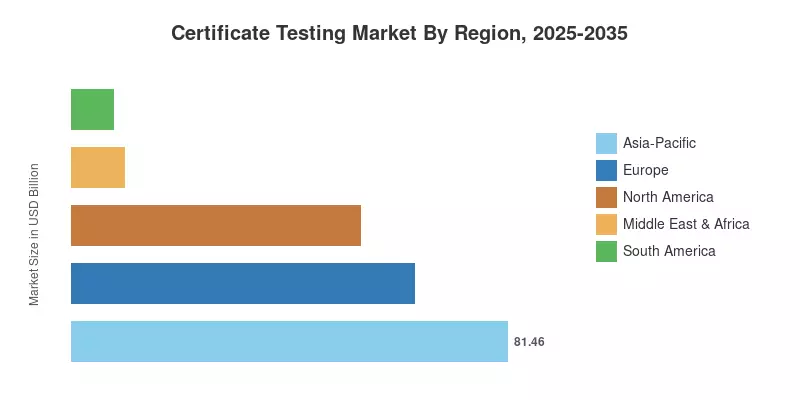
Asia-Pacific leads the Certificate Testing Market with a 36.4% share in 2025 and is also the fastest-growing region, supported by export-oriented electronics and electric vehicle manufacturing. Europe ranks second on the strength of the densest body of product legislation of any region, while North America follows on food traceability and connected-device rules. Over the next decade, regulatory digitization rather than raw production volume will decide where testing revenue concentrates.
Key Report Takeaways
The findings below summarize the most material conclusions of this report, with one headline metric per segment.
• By Sourcing Type
- Outsourced providers hold a 67.4% share across the Certificate Testing Market as manufacturers retire captive labs and convert fixed test costs into variable spend
- In-House laboratories retain a 32.6% share, concentrated in pharmaceutical and semiconductor firms protecting intellectual property
• By End-User Vertical
- Food and Healthcare leads with a 30.1% share, driven by traceability rules and recurring hygiene audits
- Transportation is the fastest-growing vertical in the Certificate Testing Market at a 5.66% CAGR as vehicle cybersecurity and battery approvals multiply
• By Testing Type
- Electrical and Electronics Testing holds a 42.6% share, reflecting mandatory safety and electromagnetic compatibility marks
- Software and Cybersecurity Testing advances at a 5.39% CAGR on vehicle and connected-product mandates
• By Certification Type
- Product Certification accounts for a 49.3% share as the gatekeeper for market entry
- Management System Certification expands at a 6.02% CAGR, supported by investor-driven ISO credential demand
• By Service Type
- Testing captures a 55.8% share owing to its equipment-intensive, sample-based workload
- Certification grows at a 5.02% CAGR as bundled multi-standard audits deepen client retention
• By Region
- Asia-Pacific commands a 36.4% share on the back of electronics and battery export volumes
- Europe generates USD 64.0 B in 2025, anchored by the EU product legislation pipeline
- Middle East & Africa grows at a 4.4% CAGR as Gulf conformity schemes and infrastructure programs expand
Market Size and Forecast (2021–2035)
Market Research Future sized the Certificate Testing Market bottom-up from the reported revenues of listed testing, inspection and certification providers, adjusted for the share of each company's portfolio tied to certification and testing, and top-down from accreditation-body registries and management system certificate counts [1][18]. Private-provider revenue was estimated from laboratory capacity and headcount benchmarks. Forecasts combine regulatory calendars with industrial production outlooks and were validated through interviews with laboratory managers and procurement leads.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



