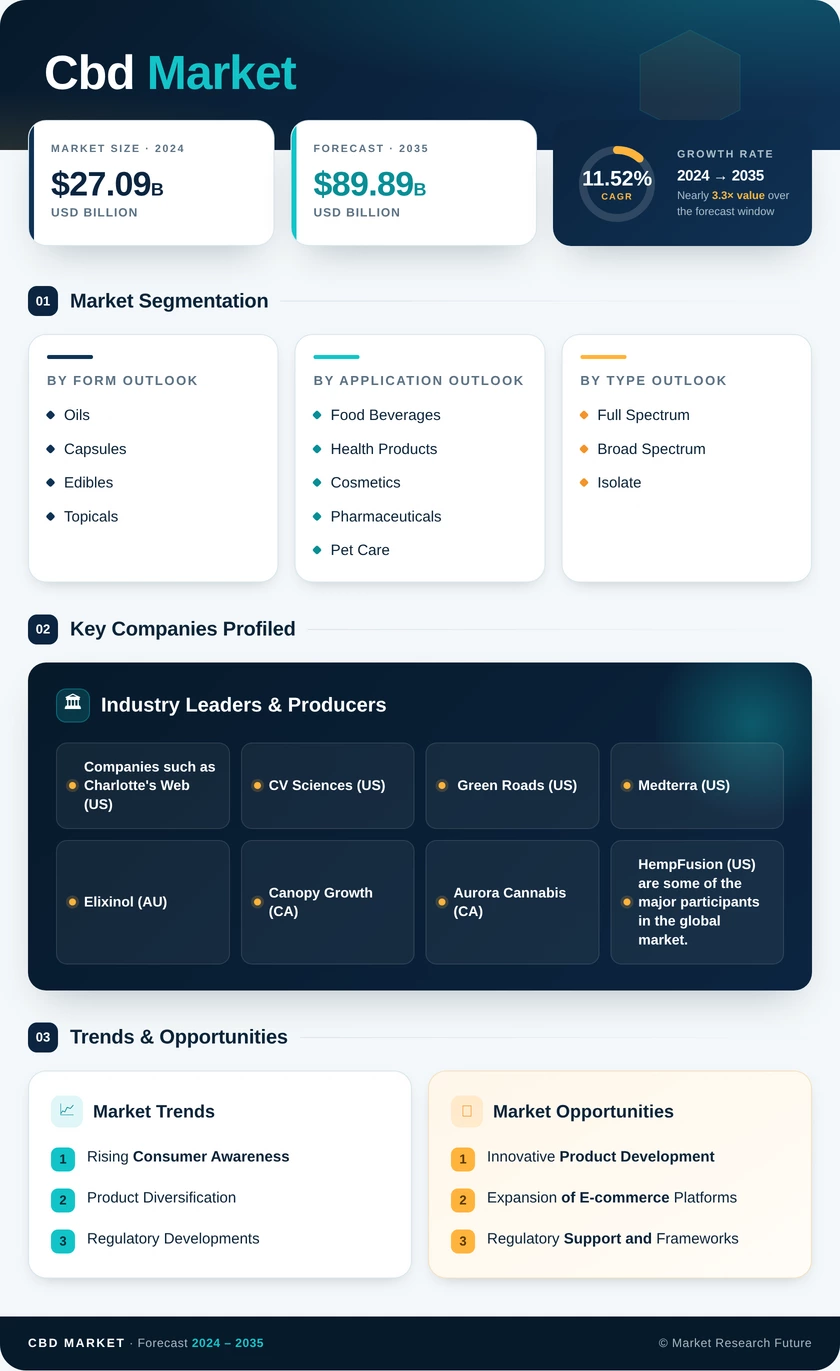
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Source | Hemp; Marijuana | Hemp | Marijuana |
| By End Use | Pharmaceuticals; Wellness & Personal Use; Food & Beverages; Pet Care; Others | Pharmaceuticals | Pet Care |
| By Product Form | Oils & Tinctures; Capsules & Softgels; Gummies & Confectionery; Topicals & Cosmetics; Beverages; Others | Oils & Tinctures | Gummies & Confectionery |
| By Distribution Channel | Hospital & Specialty Pharmacies; Retail Stores; E-commerce; Others | Retail Stores | E-commerce |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Source
| Sub-Segment | Key Trend |
| Hemp | Cross-border movement under industrial commodity rules sustains volume leadership. |
| Marijuana | Full-spectrum preference in adult-use states drives premium pricing and faster growth. |
Source choice is now a market-access decision rather than a formulation one. Producers increasingly run parallel hemp and marijuana supply chains so a single brand can serve export-eligible and domestic-premium channels without reformulating.
By End Use
| Sub-Segment | Key Trend |
| Pharmaceuticals | Reimbursed indications and prescriber confidence anchor value leadership |
| Wellness & Personal Use | Sleep, stress and recovery claims dominate consumer positioning. |
| Food & Beverages | Fast-onset emulsions convert occasional buyers into repeat purchasers. |
| Pet Care | Highest growth rate of any end use, with strong repeat-purchase behaviour |
| Others | Research and industrial applications remain small but stable. |
End-use economics are diverging sharply. Pharmaceutical and veterinary channels reward clinical investment and prescriber relationships, while consumer wellness increasingly competes on brand and format innovation rather than cannabinoid content.
By Product Form
| Sub-Segment | Key Trend |
| Oils & Tinctures | Share erodes gradually as newer buyers reject dosing friction |
| Capsules & Softgels | Familiar supplement format retains older demographic loyalty. |
| Gummies & Confectionery | Highest new-user conversion rate across all formats |
| Topicals & Cosmetics | Lighter regulatory burden speeds market entry across jurisdictions. |
| Beverages | Nanoemulsion onset gains unlock alternative-to-alcohol positioning. |
| Others | Inhalables and transdermals serve niche therapeutic needs. |
Format is where margin now lives. As input costs fall, brands defending price do so through delivery performance and sensory experience rather than raw cannabinoid concentration.
By Distribution Channel
| Sub-Segment | Key Trend |
| Hospital & Specialty Pharmacies | Positioned to expand sharply if rescheduling finalises |
| Retail Stores | Largest share but rising private-label pressure on margin |
| E-commerce | Subscription models lift order values and lifetime revenue. |
| Others | Practitioner and wholesale routes serve professional buyers. |
Channel strategy increasingly determines which brands survive consolidation. Operators with owned digital audiences sidestep advertising restrictions, while those dependent on third-party retail face both shelf-fee inflation and private-label substitution.
By Geography
| Sub-Segment | Key Trend |
| North America | Rescheduling outcome reshapes pharmacy access and tax economics |
| Europe | Novel food authorisations gate ingestible category expansion |
| Asia-Pacific | Statutory reform in Japan and Thailand opens new demand pools. |
| South America | Export-grade cultivation and expanding prescription registries |
| Middle East & Africa | Pharmaceutical-only frameworks concentrate value in registered products. |
Geographic strategy follows regulatory calendars, not consumer surveys. Firms that register dossiers ahead of statutory implementation consistently capture distribution positions that later entrants must acquire at a premium.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA