Camera Lens Market (2026 - 2035)

Camera Lens Market Size, Share and Research Report By Type (Digital Camera Lenses, Smartphone Camera Lenses, Action Camera Lenses, Mirrorless Camera Lenses), By Material (Glass, Plastic, Composite), By Focal Length (Wide Angle, Standard, Telephoto, Macro), By Mount Type (Interchangeable, Fixed) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast Till 2035
ID: MRFR/SEM/41369-HCR 200 Pages Nirmit Biswas, Garvit Vyas Last Updated: September 11, 2026
Camera Lens Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.85%
2025 Market SizeUSD 6.80 Billion
2035 Market SizeUSD 13.13 Billion
Key Players
Sunny Optical Technology
Largan Precision
Canon Inc.
Sony Group Corporation
Nikon Corporation
Fujifilm Holdings
Opportunities
  • Automotive Sensor Cleaning and Heated Optics
  • India and Southeast Asia as a Second Optical Cluster
  • Optics-as-a-Specification for Machine Vision Integrators

Camera Lens Market Summary

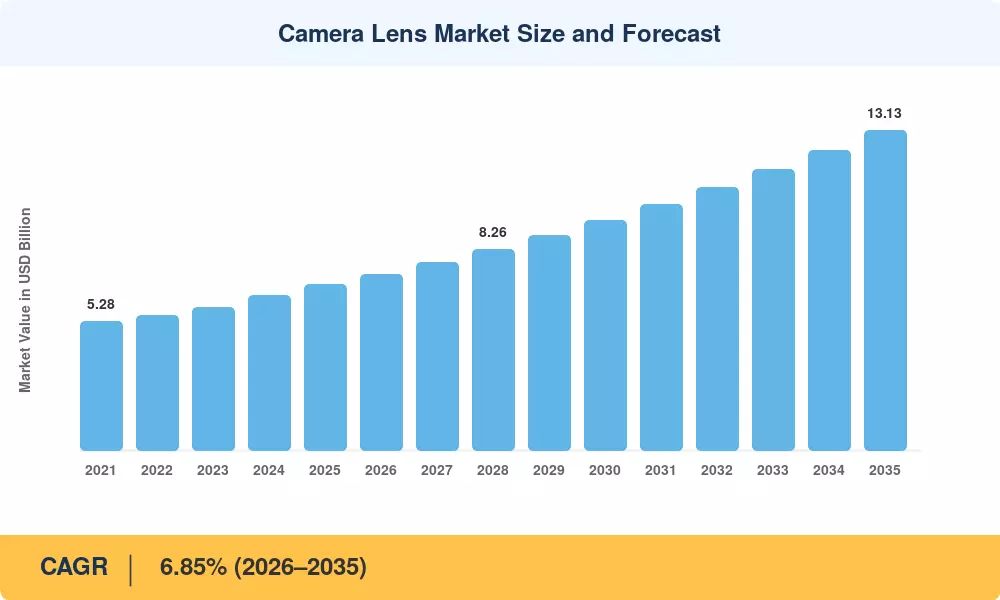
The Camera Lens Market was valued at USD 6.80 billion in 2025 and is projected to open the forecast window at USD 7.23 billion in 2026, reaching USD 13.13 billion by 2035 at a 6.85% CAGR. Two catalysts anchor that trajectory. India's Electronics Component Manufacturing Scheme, notified in April 2025 with an INR 22,919 crore outlay, explicitly names camera module sub-assemblies as a priority category — the first tranche of seven approvals in October 2025 committed INR 5,532 crore [1][2]. Alongside it, the European Union's General Safety Regulation (EU) 2019/2144 became binding on all new vehicle registrations from 7 July 2024, hard-wiring multi-camera perception into every passenger car sold in the bloc [3].

Optical design is where the transformation is sharpest. Fixed-aperture, spherical-element assemblies are giving way to folded periscope stacks, moulded aspheric arrays, and liquid-crystal variable apertures. Sunny Optical shipped more than 100 million vehicle lens sets in 2024 — a first for any supplier — and holds above 30% of that niche globally [4]. The Camera Lens Market is also absorbing a quiet materials shift toward high-refractive-index glass and hybrid glass-plastic barrels that hold modulation transfer function at wider apertures.

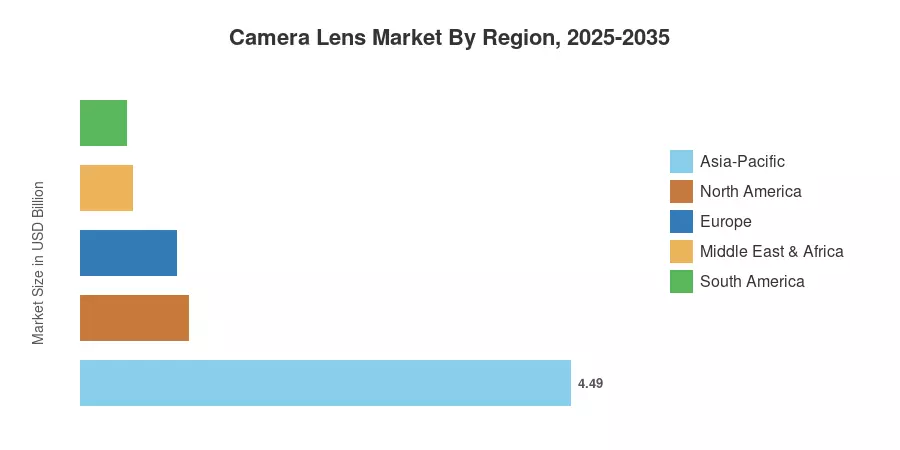
Geographically, Asia-Pacific commands roughly 66.0% of 2025 revenue and grows fastest at 8.15% CAGR, powered by handset module clusters in Guangdong, Vietnam, and Tamil Nadu. North America follows at USD 0.99 billion, sustained by machine vision and defence optics procurement. Europe holds close to 13.0%, where regulatory-driven automotive imaging outweighs consumer demand. The next decade in the Camera Lens Market will be decided less by megapixel counts than by who controls precision moulding capacity.


Key Report Takeaways

• By Lens Type


  • Standard and prime lenses retained a 52.0% share of the Camera Lens Market in 2025, reflecting entrenched kit-lens attach rates.
  • Periscope (folded optics) lenses are advancing at a 12.1% CAGR through 2035, the fastest of any lens type.


• By Application


  • Consumer electronics generated USD 4.22 billion in 2025 within the Camera Lens Market.
  • Industrial and machine vision applications are expanding at an 11.0% CAGR to 2035


• By Region

  • Asia-Pacific held 66.0% of global revenue in 2025
  • North America is projected to grow at 4.9% CAGR across the forecast window
  • Middle East & Africa contributed USD 0.22 billion to the Camera Lens Market in 2025


Market Size and Forecast (2021–2035)

Figures below reconcile three inputs: association-level shipment statistics from the Camera & Imaging Products Association, audited component revenue disclosures from listed optical suppliers, and bottom-up ASP modelling across five lens architectures. Historical values are anchored to reported unit shipments and blended average selling prices; forecast values apply segment-weighted growth rather than a single blanket rate. The Camera Lens Market series is expressed in USD billion throughout.
Camera Lens Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
ADAS regulatory mandates 1.55 Europe, North America, China Short-term (≤2 yr)
Multi-camera handset architectures 1.40 Asia-Pacific Short-term (≤2 yr)
Industrial machine vision deployment 1.10 Global Medium-term (2–4 yr)
Government component manufacturing incentives 0.85 India, Vietnam, Mexico Medium-term (2–4 yr)
Mirrorless system upgrade cycle 0.75 Japan, US, Europe Short-term (≤2 yr)
AR/MR and smart eyewear optics 0.65 Asia-Pacific, North America Long-term (≥4 yr)
Surveillance and public safety infrastructure 0.55 MEA, Asia-Pacific Long-term (≥4 yr)


Regulatory Mandates Are Making Cameras Non-Optional

Regulation now sets the floor for automotive optics demand. Regulation (EU) 2019/2144 applied to all newly registered vehicles from 7 July 2024, requiring reversing detection, driver drowsiness warning, and intelligent speed assistance — capabilities that in practice demand three to eight camera positions per vehicle [3]. In the United States, FMVSS 111 has required rear visibility systems on all light vehicles under 10,000 lbs since May 2018 [11]. Each mandated position carries a lens assembly rated for AEC-Q102 thermal cycling, which raises unit content well above consumer averages and gives the Camera Lens Market an unusually stable regulatory floor.

Handset Content Growth Outruns Handset Volume

Smartphone unit shipments have flattened, yet optical content per device keeps climbing. Sunny Optical's premium six-plastic-element-and-above lens shipments grew 11.5% year-on-year in 2024, and periscope plus large-image-size modules rose 27.5% to roughly 24 million units [12]. Folded optics let vendors deliver 5x optical reach inside an 8.5 mm chassis, and the tetraprism approach adopted at the flagship tier in late 2023 has since cascaded into upper mid-range devices across Chinese OEM portfolios.

Machine Vision Moves From Rules to Inference

Factory inspection is shifting from deterministic rule engines to embedded neural inference, and that changes optical specifications. Inference models degrade sharply on chromatic aberration and edge softness, so integrators now specify low-distortion telecentric and fixed-focal designs rated above 12 megapixels where 5 megapixels once sufficed. Global industrial robot installations have held above 500,000 units annually since 2021, and each vision-guided cell typically carries two to six lens assemblies [8].

Sovereign Manufacturing Incentives Reshape Supply

India's Electronics Component Manufacturing Scheme carries a INR 22,919 crore outlay over six years and had attracted investment commitments near INR 1.15 lakh crore by December 2025 — roughly double the original INR 59,350 crore target [1][2]. Camera module sub-assemblies sit inside the scheme's priority list, and approved projects already span optical devices. Similar capex-linked programmes in Vietnam and Mexico are pulling second-source capacity out of coastal China.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Optical-grade glass and rare-earth input volatility -0.85 Global Medium-term (2–4 yr)
DSLR installed-base decline -0.70 Japan, Europe, North America Short-term (≤2 yr)
Computational imaging substitution -0.60 Asia-Pacific Long-term (≥4 yr)
Export controls and entity-list restrictions -0.50 China, US Short-term (≤2 yr)
Precision moulding capacity bottlenecks -0.45 Asia-Pacific Medium-term (2–4 yr)


The DSLR Tail Is Shorter Than It Looks

In 2025, DSLR shipments dropped by 31% YoY, marking the sixth consecutive year of declines and representing just 7.3% of overall camera shipments [7]. F-mount and EF-mount catalogs are burdened with hundreds of legacy SKUs, so the revenue unwind is out of proportion to unit share. Discontinued tooling cannot be amortized further, and channel inventory clears at discount. Suppliers that do not have a viable mirrorless roadmap will have a reduced transition window.


Input Cost Volatility Squeezes the Middle Tier

High refractive index optical glass depends on the oxides of lanthanum, gadolinium and niobium, which are concentrated in a restricted supply base. If the price of these oxides moves more than 20%, the cost of the premium elements jumps, and the mid-tier lens houses don’t have the volume to hedge. To compound this, the supply of cyclo-olefin polymer for molded plastic items is dominated by two Japanese producers, leaving little space for negotiation [13].


Software Is Quietly Absorbing Optical Value

Computational processes now recover detail that used to need physical glass, with multi-frame stacking, learning deblurring and semantic upscaling reducing the marginal return on an extra element. This doesn’t remove the demand for lenses. Still, it does limit ASP growth in the mass consumer tier and pushes optical difference to the extremes: ultra-wide apertures, ultra-long reach, ultra-compact form factors.


Camera Lens Market Opportunities

Automotive Sensor Cleaning and Heated Optics

Reliability of perception in snow, fog and road spray is a functional safety necessity, not a luxury element. Integrated heating components, hydrophobic surface treatments and ultrasonic cleaning constitute a premium sub-segment of the Camera Lens Market where content value can be three to four times that of a regular external lens. Suppliers with defogging active in volume have a considerable head start [4].


India and Southeast Asia as a Second Optical Cluster

Scheme-backed capacity in India is real rather than announced: seven ECMS projects worth INR 5,532 crore were cleared in October 2025, with camera module sub-assemblies among the approved categories [2]. Vietnam has absorbed parallel module investment. For buyers, this opens a genuine dual-sourcing option outside the Pearl River Delta for the first time in a decade.

Optics-as-a-Specification for Machine Vision Integrators

Vision system integrators increasingly want validated lens-sensor-illumination bundles rather than components. Suppliers who publish MTF curves, distortion maps, and thermal drift data as machine-readable specifications capture design-in earlier and defend against commodity substitution. This is a business-model shift — recurring calibration and validation services attached to hardware sales.

Surveillance Refresh in Gulf Infrastructure Programmes

Large-scale urban programmes across Saudi Arabia and the UAE embed perimeter and traffic monitoring at design stage. Varifocal lenses for security cameras dominate these tenders because a single SKU covers multiple mounting geometries, cutting installation cost. The Camera Lens Market gains an unusually specification-driven demand pool here, less price-sensitive than consumer channels.

Smart Eyewear and Pass-Through Optics

Lightweight AR devices demand freeform and pancake optical elements at thicknesses conventional grinding cannot reach. Wafer-level and nano-imprint processes are approaching cost parity, and suppliers investing in those lines now position for volumes that arrive after 2030 [9].


Camera Lens Market Future Outlook

Inference at the Edge Rewrites Optical Requirements

Edge neural processing changes what "good enough" optics means. Models trained on clean imagery degrade unpredictably when fed soft-cornered or aberrated frames, so system architects are specifying tighter MTF thresholds even as sensor sizes shrink. Over the forecast decade, the Camera Lens Market will bifurcate between commodity assemblies and inference-grade optics carrying published, traceable optical performance data.

Platform Economics Reach Optical Mounts

Mount ecosystems behave like software platforms. Opening a mount to third-party designers expands the lens catalogue without capital outlay and locks bodies into the ecosystem — a dynamic already visible as major manufacturers license their mirrorless mounts to independent optical houses. Expect further licensing through 2030, with royalty structures becoming a disclosed revenue line.

The Automotive Content Supercycle

Per-vehicle camera counts rise from roughly five today toward eleven in Level 3-capable architectures. Because each exterior position requires environmental sealing, thermal stability, and functional safety documentation, automotive lens ASPs hold far better than consumer equivalents. Sunny Optical's automotive order book alone stood near RMB 15 billion in 2025, indicating multi-year visibility [12].

Circularity and Optical Glass Stewardship

Rare-earth-bearing optical glass faces tightening scrutiny under EU circular economy rules and extended producer responsibility regimes. Reclaiming lanthanum from cullet is technically viable but commercially immature. Suppliers who establish closed-loop glass recovery in this decade convert a compliance cost into a raw material hedge — an underrated strategic move.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America USD 0.99 Billion Machine vision, defence optics, medical endoscopy
Europe 13.0% share Regulatory ADAS, industrial inspection, cine optics
Asia-Pacific 66.0% share Handset modules, automotive lens sets, XR optics
South America 6.2% CAGR Surveillance, agricultural machine vision
Middle East & Africa 7.0% CAGR Smart city surveillance, oil and gas inspection
Total USD 6.80 Billion

Regional distribution in the Camera Lens Market is more concentrated than most electronics categories because optical component manufacturing clusters tightly around precision moulding and coating capacity.


North America

Country Metric Key Driver
US 78.0% of region Machine vision and defence procurement
Canada 5.1% CAGR Industrial automation retrofits
Mexico USD 0.13 Billion Automotive module assembly nearshoring


Demand here is specification-led rather than volume-led. Federal restrictions on certain Chinese video surveillance equipment have redirected procurement toward domestic and allied optical suppliers, lifting ASPs across the security channel [10]. Mexico's role has shifted from assembly to sub-assembly as automotive OEMs localise camera module production near final vehicle plants.

Europe

Country Metric Key Driver
Germany 24.0% of region Automotive ADAS and industrial inspection
UK USD 0.13 Billion Broadcast and cine optics
France 4.6% CAGR Aerospace and defence imaging
Italy 9.0% of region Machine vision in packaging lines
Spain USD 0.06 Billion Surveillance infrastructure
Nordic Countries 5.4% CAGR Thermal and low-light imaging
Russia 5.0% of region Industrial and security applications
Rest of Europe USD 0.17 Billion Distributed manufacturing demand


European demand is regulation-shaped. The General Safety Regulation's full application from July 2024 lifted per-vehicle camera counts across every segment, and Euro NCAP's rating protocols push manufacturers beyond the legal minimum to protect star ratings [3]. Germany's Mittelstand machine builders form a second, quieter demand base for high-precision fixed-focal optics.

Asia-Pacific

Country Metric Key Driver
China 47.0% of region Handset and automotive module manufacturing
Japan USD 0.76 Billion Interchangeable lens design and optical glass
South Korea 13.0% of region Flagship handset optical content
India 9.8% CAGR ECMS-backed component localisation
ASEAN USD 0.40 Billion Assembly capacity diversification
Rest of Asia-Pacific 5.0% of region Regional distribution demand


Asia-Pacific dominance in the Camera Lens Market rests on vertical integration that no other region matches. Sunny Optical's 2025 revenue reached RMB 43.23 billion with vehicle lens sets holding global first position [14], while Japanese optical houses retain effective control of high-index glass melts. India's entry changes the map: ECMS commitments approaching INR 1.15 lakh crore by end-2025 signal a durable second cluster rather than a temporary tariff arbitrage [1].

South America

Country Metric Key Driver
Brazil 58.0% of region Surveillance and agricultural vision
Argentina USD 0.04 Billion Industrial inspection retrofits
Rest of South America 5.8% CAGR Public safety deployments


Growth here tracks public security budgets more closely than consumer electronics cycles. Brazilian municipal camera programmes have standardised on varifocal designs to reduce SKU complexity across mixed urban geometries, and agricultural equipment makers are adding vision-guided spraying systems that carry two to four lens assemblies per machine.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 26.0% of region Giga-project perimeter surveillance
UAE USD 0.05 Billion Smart city and traffic monitoring
South Africa 19.0% of region Mining and industrial inspection
Egypt 7.6% CAGR New administrative capital infrastructure
Rest of MEA 21.0% of region Distributed security demand


Procurement in this region is tender-driven and front-loaded, which produces lumpy revenue recognition for suppliers. Gulf infrastructure programmes specify imaging at masterplan stage, meaning lens selection is locked years before installation — an advantage for suppliers with early specification-influence capability and a barrier for late entrants.


Camera Lens Market By Region, 2025-2035

Camera Lens Market Segmentation

Segmentation in the Camera Lens Market cuts across five dimensions, each with distinct growth mechanics.

By Application

Application structure in the Camera Lens Market remains consumer-weighted, but the growth is elsewhere.

Segment Metric Primary Demand Driver
Consumer Electronics 62.0% share Multi-camera handset architectures
Automotive USD 1.09 Billion ADAS regulatory mandates
Security & Surveillance 11.0% share Public safety infrastructure
Industrial & Machine Vision 11.0% CAGR Inference-based inspection
Medical & Scientific 8.4% CAGR Endoscopy and diagnostic imaging
Others 1.0% share Broadcast, aerial, specialty


Consumer electronics generates the volume but not the margin trajectory. Handset optical content rose faster than handset units through 2024–2025, with premium element counts and folded designs carrying ASPs upward even as device shipments flattened [12]. Industrial and machine vision, by contrast, compounds at 11.0% because each new inference-based inspection cell displaces two to three legacy rule-based stations and specifies higher-resolution optics.

By Lens Type

Lens architecture within the Camera Lens Market is diversifying faster than at any point since autofocus arrived.

Segment Metric Primary Demand Driver
Standard & Prime 52.0% share Kit attach rates and portrait use
Wide-Angle & Ultra-Wide USD 1.22 Billion Multi-camera arrays and ADAS
Telephoto & Super-Telephoto 7.9% CAGR Sports, wildlife, surveillance reach
Periscope (Folded Optics) 12.1% CAGR Thin-device optical zoom
Macro 5.0% share Product imaging and inspection
Fisheye & Specialty 3.0% share Surround-view and immersive capture


Periscope designs are the structural story. By folding the optical path across a prism, manufacturers deliver 5x native reach without increasing chassis thickness — the constraint that capped optical zoom for a decade. Standard and prime lenses hold half the revenue base largely through bundled kit sales, but their share erodes roughly 60 basis points annually as buyers add specialised second and third optics.

By Mount and Compatibility

Mount economics in the Camera Lens Market determine who captures aftermarket value.

Segment Metric Primary Demand Driver
Mirrorless Mount 57.6% share System migration from reflex bodies
DSLR Mount 22.4% share Installed base servicing
Fixed / Integrated Mount USD 0.97 Billion Compact camera resurgence
Cinema / PL Mount 6.8% CAGR Streaming production volume
Industrial (C/CS/F) Mount 9.9% CAGR Machine vision deployments


Mirrorless mounts now anchor the category. Interchangeable mirrorless camera lenses drove the 2024 recovery, with total interchangeable lens shipments reaching 10.31 million units at 107.0% of the prior year and sub-35mm-format mirrorless optics growing 108.1% [5]. DSLR mounts remain revenue-relevant through the installed base, but no major manufacturer is investing in new reflex-mount optical designs.

By End-User

Segment Metric Primary Demand Driver
Professional 47.0% share Commercial and editorial production
Consumer / Enthusiast USD 1.90 Billion Content creation and travel imaging
OEM & Module Suppliers 12.6% CAGR Handset and automotive integration
Institutional / Government 8.0% share Surveillance and research procurement


Professional end-users remain the dominant segment within the Camera Lens Market, fueled by continuous demand for high-end commercial and editorial production optics. OEM and module suppliers stand out as the fastest-growing segment, propelled by rapid handset optical content expansion and mandatory automotive integration standards.

By Focal Length

Segment Metric Primary Demand Driver
Ultra-Wide (<16 mm) 11.2% CAGR Surround-view and architectural capture
Wide (16–35 mm) 38.5% share Default handset and kit focal range
Standard (36–70 mm) USD 1.80 Billion Portrait and general-purpose use
Telephoto (71–300 mm) 16.0% share Sports, events, surveillance
Super-Telephoto (>300 mm) 6.7% CAGR Wildlife and long-range monitoring


Wide lenses remain the dominant focal length segment within the Camera Lens Market, fueled by their widespread adoption as the default focal range for consumer smartphones and standard camera kit lenses. Ultra-wide lenses stand out as the fastest-growing segment, propelled by increasing automotive surround-view requirements and architectural capture applications.


Competitive Benchmarking

Concentration in the Camera Lens Market is high by electronics standards. Top-five suppliers control an estimated 52–58% of global revenue, and the Herfindahl-Hirschman Index sits near 900–1,050 — moderately concentrated, with the caveat that concentration is far tighter within individual sub-segments. Handset lens sets are effectively a duopoly-plus structure; interchangeable optics are dominated by three Japanese vertically integrated houses; machine vision remains genuinely fragmented across a dozen credible specialists. Differentiation increasingly rests on moulding tolerance and coating chemistry rather than optical formula, since patents on core designs have largely expired.

Company Est. Revenue Share Range Key Offerings for Camera Lens Market Strategic Positioning
Sunny Optical Technology (Group) ~14–18% Vehicle lens sets, handset lens sets, glass aspheric elements, XR optics Global No.1 in vehicle lens sets with over 30% segment share [4]
Largan Precision ~10–13% High-element-count plastic handset lens assemblies, periscope modules Premium handset optics leader; tightly held moulding IP
Canon Inc. ~9–12% RF and EF mount interchangeable optics, broadcast and industrial lenses Fully integrated glass-to-body manufacturer
Sony Group Corporation ~7–10% E-mount G Master optics, sensor-matched module designs Sensor-lens co-design advantage
Nikon Corporation ~5–8% Z-mount and F-mount optics, industrial metrology lenses Cine and broadcast expansion post-RED integration
Fujifilm Holdings ~4–7% Fujinon broadcast, cine, machine vision and X/GFX optics Strongest breadth across professional imaging tiers
Zhejiang Crystal-Optech ~3–5% Optical filters, handset and automotive lens components Cost-competitive Chinese supply-chain integrator
Carl Zeiss AG ~3–5% Cine optics, industrial metrology and inspection lenses Premium specification-led positioning
Panasonic Holdings ~2–4% L-mount optics, security and industrial lens assemblies Alliance-based mount ecosystem strategy
Sigma Corporation ~2–4% Multi-mount third-party optics across mirrorless systems Independent designer with cross-platform reach
Tamron Co., Ltd. ~2–3% Third-party zooms, automotive and surveillance optics Dual consumer and OEM channel model
HOYA Corporation ~2–3% Optical glass, moulded aspheric blanks, endoscopy optics Upstream materials control


Recent News & Developments

  • Nikon Corporation (April 2024): Completed its acquisition of RED.com, adding cinema camera and lens system capability and signalling a strategic pivot toward professional motion imaging [15].


  • European Commission (July 2024): Regulation (EU) 2019/2144 became mandatory for all newly registered vehicles, embedding multi-camera advanced driver assistance across the EU fleet and lifting per-vehicle optical content [3].
  • Camera & Imaging Products Association (February 2025): Reported 2024 interchangeable lens shipments of 10,312,728 units at 107.0% year-on-year, with sub-35mm mirrorless optics up 108.1% — confirming the category's return to growth [5].
  • MeitY (October 2025): Approved the first ECMS tranche of seven projects worth INR 5,532 crore, spanning camera module sub-assemblies, multi-layer PCBs and laminates [2].
  • Sunny Optical Technology (March 2025): Disclosed that vehicle lens set shipments passed 100 million units in 2024 for the first time, retaining global first position with over 30% share [4].
  • Camera & Imaging Products Association (February 2026): Confirmed 2025 digital camera shipments of 9.44 million units — a second consecutive annual increase, the first such run since 2007 — with lens shipments near 10.6 million units [7].
  • Sunny Optical Technology (March 2026): Reported FY2025 revenue of approximately RMB 43.23 billion with gross margin at 19.7%, citing rising automotive optics revenue share [14].


Camera Lens Market Report Scope

Parameter Detail
Market Scope Global Camera Lens Market across application, lens type, mount and compatibility, end-user, focal length and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.85% (2026–2035)
Market Size Checkpoints USD 6.80 Billion (2025); USD 7.23 Billion (2026); USD 13.13 Billion (2035)
Fastest Growing Segments Periscope lenses (12.1% CAGR); OEM & module suppliers (12.6% CAGR); Industrial & machine vision (11.0% CAGR)
Companies Profiled 12 leading suppliers including Sunny Optical, Largan Precision, Canon, Sony, Nikon, Fujifilm, Zeiss, HOYA
Valuation Currency USD Billion

FAQs

What procurement terms should buyers negotiate when sourcing optics in the Camera Lens Market?
Lock tooling ownership and MTF acceptance criteria into the purchase agreement, not a side annex. Precision moulds carry 18–24 month lead times, so tooling title determines whether you can switch suppliers at all [12].
How do automotive lens qualification requirements differ from consumer optics?
Automotive assemblies require AEC-Q102 thermal cycling, IP69K sealing, and ISO 26262 functional safety documentation. Qualification typically adds 12–18 months and materially raises unit cost, which is why automotive optics resist the ASP erosion seen in the consumer Camera Lens Market [3].
Is dual-sourcing outside China realistic yet for the Camera Lens Market?
Partially. India and Vietnam now handle module sub-assembly credibly, but high-index glass melting and premium aspheric moulding remain concentrated in Japan and China [1].
What does a supplier's coating capability actually signal?
Multi-layer anti-reflective and hydrophobic coatings are where flare control and environmental durability are won. Suppliers running in-house sputtering lines control quality and lead time; those outsourcing coating carry hidden schedule risk [13].
Which certifications matter most for surveillance tenders in the Camera Lens Market?
IEC 62676 conformance and, for Western public procurement, absence from restricted-equipment lists. Both are increasingly gating criteria rather than tie-breakers [10].
How should integrators evaluate telecentric versus standard lenses for inspection?
Telecentric designs eliminate perspective error, making them essential for dimensional gauging. Standard fixed-focal optics suffice for presence-absence and surface defect detection at roughly one-third the cost, and remain the volume choice across the Camera Lens Market [8].
What is the realistic replacement cycle for installed automotive camera optics?
Exterior assemblies are designed for vehicle lifetime, typically 12–15 years. Aftermarket replacement demand comes almost entirely from collision repair rather than wear, which keeps the segment small but predictable [3].      
Author
Author Author Profile Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author Co-Author Profile Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.