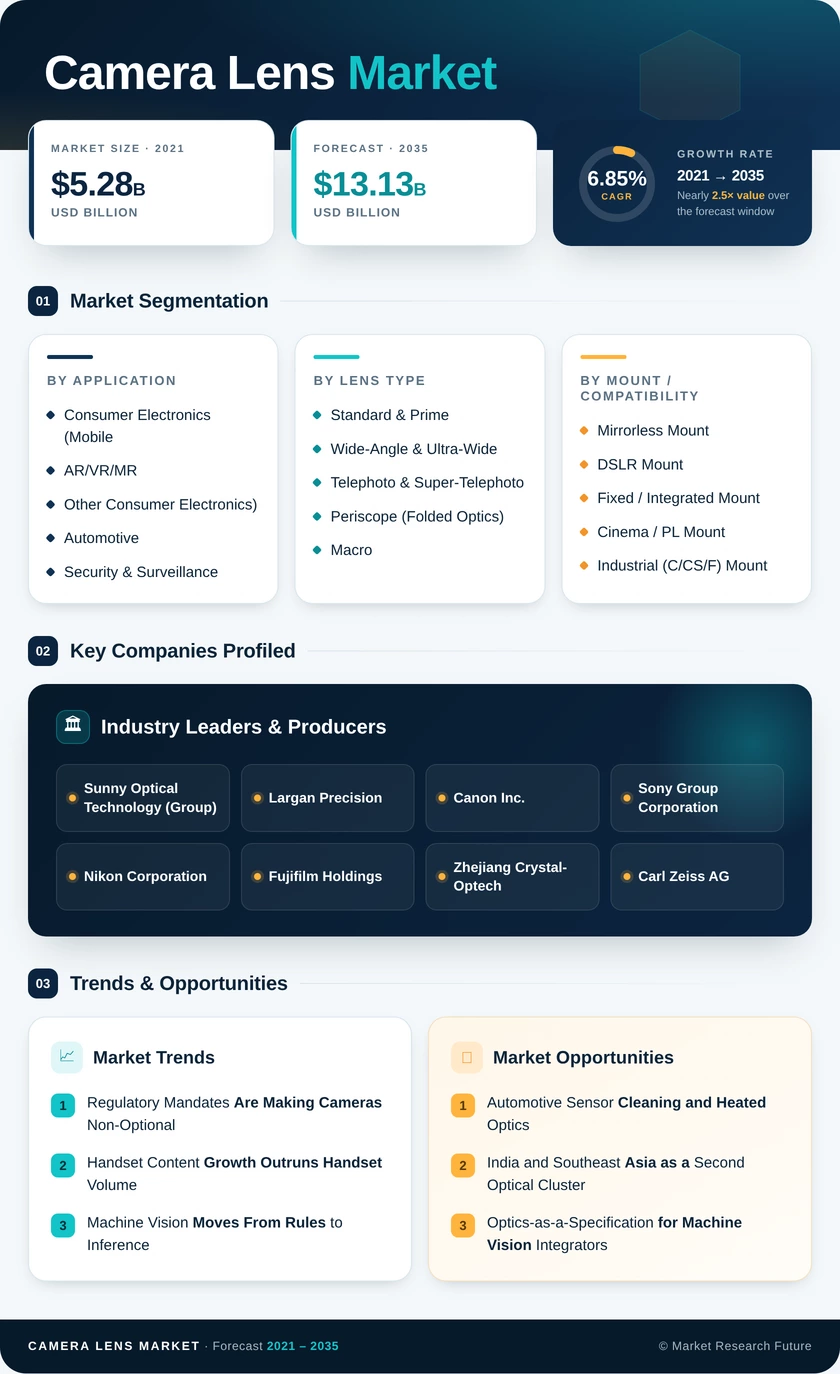
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| Application | Consumer Electronics (Mobile, AR/VR/MR, Other Consumer Electronics), Automotive, Security & Surveillance, Industrial & Machine Vision, Medical & Scientific, Others | Consumer Electronics | Industrial & Machine Vision |
| Lens Type | Standard & Prime, Wide-Angle & Ultra-Wide, Telephoto & Super-Telephoto, Periscope (Folded Optics), Macro, Fisheye & Specialty | Standard & Prime | Periscope (Folded Optics) |
| Mount / Compatibility | Mirrorless Mount, DSLR Mount, Fixed / Integrated Mount, Cinema / PL Mount, Industrial (C/CS/F) Mount | Mirrorless Mount | Industrial (C/CS/F) Mount |
| End-User | Professional, Consumer / Enthusiast, OEM & Module Suppliers, Institutional / Government | Professional | OEM & Module Suppliers |
| Focal Length | Ultra-Wide (<16 mm), Wide (16–35 mm), Standard (36–70 mm), Telephoto (71–300 mm), Super-Telephoto (>300 mm) | Wide (16–35 mm) | Ultra-Wide (<16 mm) |
| Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Application
| Sub-Segment | Key Trend |
| Consumer Electronics – Mobile | Multi-camera arrays push optical content per device above unit growth |
| Consumer Electronics – AR/VR/MR | Pass-through and pancake optics enter early volume production |
| Consumer Electronics – Other | Compact camera resurgence revives fixed-lens demand |
| Automotive | Regulatory mandates lift exterior and in-cabin camera positions per vehicle |
| Security & Surveillance | Single-SKU variable focal designs reduce installation complexity |
| Industrial & Machine Vision | Inference-based inspection raises resolution and distortion specifications |
| Medical & Scientific | Disposable endoscope optics create a recurring consumption model |
| Others | Broadcast, aerial and specialty imaging sustain niche premium demand |
Application demand is splitting along a value line. Consumer electronics still carries the volume, but automotive and industrial applications increasingly set the technical agenda — thermal stability, functional safety documentation, and traceable optical performance data are becoming table stakes in those channels and gradually migrating back into consumer specifications.
By Lens Type
| Sub-Segment | Key Trend |
| Standard & Prime | Kit attach rates hold volume but share erodes annually |
| Wide-Angle & Ultra-Wide | Surround-view and multi-camera arrays drive unit expansion |
| Telephoto & Super-Telephoto | Reach demand strengthens across sports, wildlife and monitoring |
| Periscope (Folded Optics) | Prism-folded designs cascade from flagship into mid-tier devices |
| Macro | Product imaging and close-range inspection sustain steady demand |
| Fisheye & Specialty | Immersive capture and 360-degree vehicle views expand niche volume |
Architecture is now the primary differentiator. Folded optical paths solved the thickness constraint that capped zoom performance for a decade, and the manufacturing know-how required — prism alignment tolerance in particular — creates a genuine barrier that protects incumbent suppliers.
By Mount and Compatibility
| Sub-Segment | Key Trend |
| Mirrorless Mount | Shorter flange distance enables optical designs impossible on reflex bodies |
| DSLR Mount | Installed base sustains servicing revenue without new design investment |
| Fixed / Integrated Mount | Premium compact revival lifts integrated optical assemblies |
| Cinema / PL Mount | Streaming production volume expands professional optics demand |
| Industrial (C/CS/F) Mount | Machine vision standardisation drives modular lens interchangeability |
Mount strategy has become platform strategy. Manufacturers licensing their mirrorless mounts to independent designers expand catalogue breadth without capital outlay, and that catalogue breadth is what locks users into a system for a decade or more.
By End-User
| Sub-Segment | Key Trend |
| Professional | Hybrid stills-video workflows drive demand for parfocal, breathing-corrected designs |
| Consumer / Enthusiast | Content creation and travel imaging sustain mid-tier zoom demand |
| OEM & Module Suppliers | Integration-led procurement shifts value toward component specification |
| Institutional / Government | Tender-driven surveillance and research procurement with long specification cycles |
Buyer sophistication varies enormously across these groups, and so does price sensitivity. OEM and module suppliers negotiate on cost-per-element and yield, while professional buyers pay for optical character — two entirely different sales motions from the same factory.
By Focal Length
| Sub-Segment | Key Trend |
| Ultra-Wide (<16 mm) | Surround-view automotive and architectural capture drive fastest expansion |
| Wide (16–35 mm) | Default handset and kit range retains the largest revenue base |
| Standard (36–70 mm) | Portrait and general-purpose use sustains stable demand |
| Telephoto (71–300 mm) | Sports, events and monitoring applications support premium pricing |
| Super-Telephoto (>300 mm) | Diffractive and fluorite elements reduce weight, widening the addressable base |
Focal length distribution reveals where optical engineering effort concentrates. The extremes — ultra-wide and super-telephoto — grow fastest because they are hardest to replicate computationally, while the middle of the range faces the steepest substitution pressure from software-based processing.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA