Blood Screening Market (2026 - 2035)

Blood Screening Market Research Report By Technology (Nucleic Acid Amplification Test, Enzyme-Linked Immunosorbent Assay, Next-Generation Sequencing), Product and Services (Reagents, Instruments) and End User (Hospitals and Clinics) - Forecast till 2035
ID: MRFR/MED/5434-HCR 85 Pages Rahul Gotadki, Kinjoll Dey Last Updated: September 15, 2026
Blood Screening Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)9.0%
2026 Market SizeUSD 3.77 Billion
2035 Market SizeUSD 8.19 Billion
Key Players
Grifols S.A.
F. Hoffmann-La Roche AG
Abbott Laboratories
Bio-Rad Laboratories
Ortho Clinical Diagnostics
Immucor
Opportunities
  • Point-of-Care Molecular Screening for Remote Collection Sites
  • AI-Powered Predictive Inventory and Release Systems
  • Pathogen-Reduction as a Screening Complement

Blood Screening Market Summary

The Blood Screening Market size was valued at USD 3.46 Billion in 2025, and the market is projected to grow from USD 3.77 Billion in 2026 to USD 8.19 Billion by 2035, registering a CAGR of 9.0% during the forecast period 2026–2035. This expansion is anchored in tightening regulatory mandates that now prioritize individual donor risk assessment over blanket deferral policies, a shift that compels blood centers worldwide to upgrade testing infrastructure. The WHO's Action Framework for Blood Safety 2024–2030 has accelerated adoption of integrated screening platforms across low- and middle-income countries, channeling an estimated USD 1.2 Billion in multilateral funding toward pathogen detection modernization [1].

A technology transformation is reshaping how blood products are tested before release. Legacy serological assays — once the backbone of donor screening — are giving way to multiplex molecular platforms capable of detecting HIV, HBV, HCV, and emerging pathogens in a single run. The U.S. FDA's 2024 guidance on pathogen-reduction technology interoperability has pushed manufacturers to develop systems that pair screening with inactivation, reducing the overall window period for transfusion risk [2]. Automation rates at large blood centers now exceed 85% in North America and Western Europe, up from roughly 60% a decade ago.

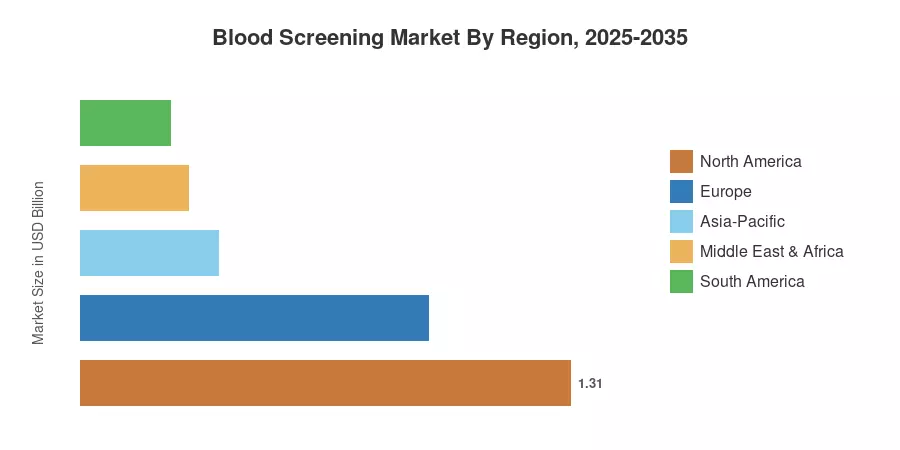
North America commands approximately 38% of the global Blood Screening Market, driven by stringent AABB standards and robust voluntary donation infrastructure. Asia-Pacific stands as the fastest-growing region with a projected CAGR of 10.7%, propelled by government-led centralization of blood banking in India and China. Europe holds the second-largest share at around 27%, underpinned by the EU Blood Directive revisions requiring expanded pathogen panels [3]. The Blood Screening Market is poised for sustained double-digit regional gains as universal screening mandates extend across sub-Saharan Africa and Southeast Asia.


Key Report Takeaways

• By Product

  • Reagents and kits captured roughly 51% of the Blood Screening Market in 2025, reflecting high consumable intensity in routine donor testing.
  • Instruments are projected to register the fastest segment CAGR of 10.6% through 2035, as blood centers replace aging analyzers with fully automated platforms.

• By Technology

  • Nucleic acid amplification testing (NAT) accounted for approximately 45% of revenue in 2025.
  • Next-generation sequencing is forecast to advance at an 11.9% CAGR through 2035, driven by its ability to identify novel or variant pathogens.

• By Screening Target

  • Infectious disease panels dominated the Blood Screening Market with around a 53% share in 2025.

• By End-User

  • Blood banks represented approximately 63% of end-user demand in 2025.
  • Clinical laboratories are expected to post the highest end-user CAGR of 11.0% through 2035.

• By Region

  • North America led the Blood Screening Market with a 38% share in 2025.
  • Asia-Pacific is projected to grow at a 10.7% CAGR through 2035, outpacing all other regions.


Market Size and Forecast (2021–2035)

Market Research Future employs a triangulated approach combining primary interviews with blood bank directors, procurement data from hospital group-purchasing organizations, and regulatory filings from the FDA, EMA, and national health authorities. Historical figures (2021–2024) reflect actual reported revenues; the base year (2025) is estimated from trailing-twelve-month company disclosures; and the forecast period (2026–2035) applies a calibrated compound growth rate of 9.0%.
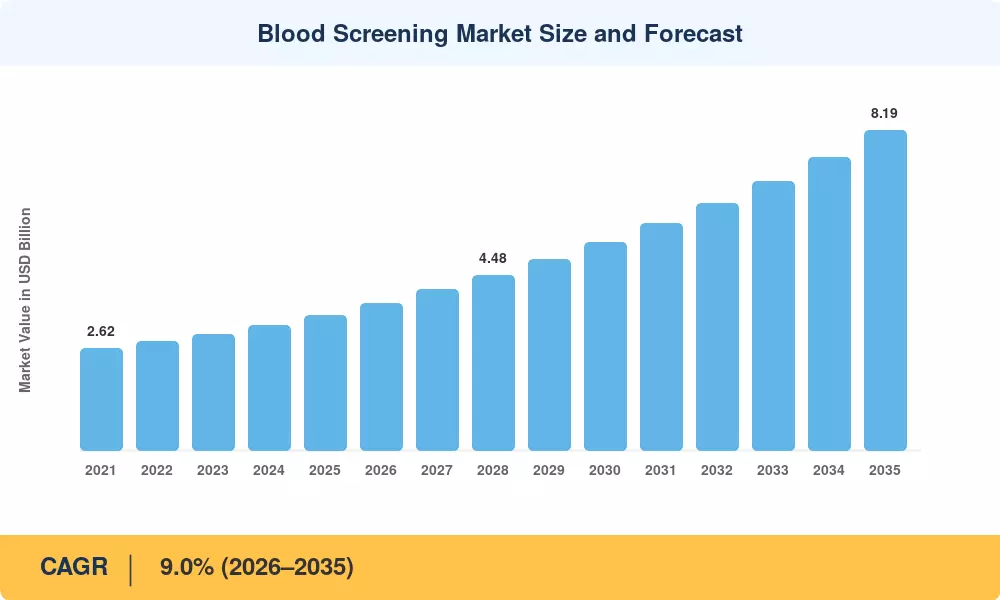
Blood Screening Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Regulatory mandates for individual donor risk assessment ~18% Global Short-term (≤2 yr)
Automation and integrated screening platforms ~16% North America, Europe Medium-term (2–4 yr)
Rising global blood donation volumes ~14% Asia-Pacific, Africa Long-term (≥4 yr)
Multiplex NAT panel expansion ~13% North America, Europe Short-term (≤2 yr)
Pathogen-reduction technology integration ~12% Europe, Asia-Pacific Medium-term (2–4 yr)
Point-of-care molecular platforms ~10% Emerging markets Long-term (≥4 yr)
AI-driven inventory and release algorithms ~8% North America, Japan Medium-term (2–4 yr)


Regulatory Mandates for Individual Donor Risk Assessment

The U.S. donor pool was altered by the FDA's 2023 final guidance, which substituted individualized risk-based questions for blanket MSM deferral, adding a projected 3–5% more eligible donors each year [2]. The market for addressable reagents and instruments will directly grow as a result of this policy change, which calls for more thorough screening of each donation unit. Similar changes in Australia and the UK (FAIR policy, 2022) have sparked a coordinated global movement toward behavioral-risk questionnaires combined with improved molecular testing, guaranteeing that the blood screening market will be able to meet the growing demand from both increased donor volumes and more stringent testing procedures per unit.


Automation and Integrated Screening Platforms

Semi-automated operations are being replaced by fully integrated platforms that incorporate sample loading, NAT amplification, and result interpretation in a closed system in large-volume blood centers that process more than 500,000 donations annually. Labor expenses are now reduced by about 30% thanks to Grifols' Panther system and Roche's Cobas 6800/8800, which can manage throughput surpassing 1,000 samples per eight-hour shift [8]. There will be a focused wave of instrument procurement for the blood screening market between 2026 and 2030 as the capital investment cycle, which is normally a 7–10 year replacement window, enters a major refresh phase across North American and European centers.


Rising Global Blood Donation Volumes

WHO data indicates that global blood collection reached 118 million units in 2023, up from 108 million in 2018, with low- and middle-income countries accounting for the majority of incremental growth [1]. India's National Blood Transfusion Council targets a 25% increase in voluntary donations by 2028 through mobile collection camps in tier-2 and tier-3 cities [6]. Each additional donation unit requires a full screening panel, directly translating collection volume gains into reagent consumption growth for the Blood Screening Market.

Multiplex NAT Panel Expansion

The evolution from single-analyte to multiplex NAT panels — now covering HIV-1/2, HBV, HCV, and increasingly Zika, Babesia, and West Nile Virus in a single cartridge — raises the revenue per test while reducing turnaround time [9]. The FDA's 2024 approval of expanded Babesia screening nationwide (previously limited to endemic states) added an entirely new line item to the U.S. Blood Screening Market, estimated at USD 120 Million in annual incremental reagent spend across the American Red Cross and Vitalant networks.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
High upfront capital costs for integrated platforms ~–6% Emerging markets Medium-term (2–4 yr)
Evolving LDT regulatory compliance burden ~–5% United States Short-term (≤2 yr)
Declining paid-donor models reducing testing volumes ~–4% South America, parts of Asia Long-term (≥4 yr)
Supply chain concentration for critical reagents ~–3% Global Short-term (≤2 yr)
Reimbursement pressure on per-unit test costs ~–3% Europe Medium-term (2–4 yr)


High Upfront Capital Costs for Integrated Platforms

Many regional blood centers in sub-Saharan Africa and Southeast Asia cannot afford these systems since a fully automated screening line, comprising instruments, IT middleware, and verified reagent contracts, can cost more than USD 2.5 million per installation [13]. Reagent-rental methods reduce capital barriers to some extent, but they also bind facilities to long-term supply contracts that restrict competitive switching and potentially raise test costs over the course of the contract, which hinders the wider penetration of the blood screening market in price-sensitive areas.


Evolving LDT Regulatory Compliance Burden

The FDA's 2024 proposed rule to bring laboratory-developed tests under formal premarket review has introduced significant compliance uncertainty for hospital-based and reference laboratories that developed proprietary screening assays [14]. Estimated compliance costs of USD 30,000–50,000 per assay per year could push smaller labs toward commercial kit adoption — a net positive for kit manufacturers but a near-term drag on testing volumes as labs pause development pipelines and reassess their screening menus.

Supply Chain Concentration for Critical Reagents

Three production facilities in the US and Switzerland provide more than 70% of the world's supply of specific lyophilized NAT reagent components [15]. A single-site outage can result in 8–12 week backorders, forcing blood facilities to switch to less sensitive immunoassay backup techniques, as the COVID-era interruptions showed. Procurement trust in the blood screening market is still hampered by this concentration risk, especially among national health systems that require continuous testing capabilities.


Blood Screening Market Opportunities

Point-of-Care Molecular Screening for Remote Collection Sites

Mobile blood drives in rural areas across India, Nigeria, and Indonesia currently rely on rapid immunochromatographic tests that offer lower sensitivity than centralized NAT . The emergence of cartridge-based, battery-operated molecular platforms — such as those adapted from GeneXpert's tuberculosis architecture — could enable near-patient NAT-equivalent screening at collection points. This would unlock an estimated 15–20 million additional safe donation units annually, significantly expanding the addressable Blood Screening Market in regions where cold-chain logistics currently limit centralized testing.

AI-Powered Predictive Inventory and Release Systems

Blood centers managing perishable inventories (red cells have a 42-day shelf life) are investing in machine-learning algorithms that predict demand by blood type, season, and trauma incidence . These systems integrate screening turnaround data to optimize release timing, reducing wastage rates from the current 5–8% benchmark to below 3%. As algorithms require real-time integration with screening platforms, they create a new software-services revenue layer adjacent to the traditional Blood Screening Market instrument-and-reagent model.

Pathogen-Reduction as a Screening Complement

Pathogen-reduction technologies (PRT) — which use UV light or chemical agents to inactivate residual pathogens in plasma and platelets — are gaining traction as a complementary layer to conventional screening [10]. While PRT does not replace infectious-disease testing, it enables streamlined panel decisions for platelet concentrates. European adoption of Cerus' Intercept system across France and Belgium has already altered procurement dynamics, creating integration opportunities for screening vendors who can co-package testing and inactivation workflows.

Expansion into Emerging-Market National Blood Programs

Sub-Saharan Africa processes approximately 8 million donation units annually but screens fewer than 60% with WHO-recommended testing protocols [1]. The African Union's Agenda 2063 health targets and PEPFAR's continued HIV testing mandates are converging to create procurement pipelines worth an estimated USD 300–400 Million through 2030 for the Blood Screening Market. Manufacturers that establish local reagent distribution and cold-chain infrastructure stand to capture first-mover advantages in these high-growth, underserved corridors.

Data Monetization Through Epidemiological Surveillance Platforms

Screening data from millions of donor samples per year represents a rich epidemiological dataset for public-health surveillance. Companies that offer anonymized, aggregated pathogen-prevalence dashboards — layered onto existing screening contracts — can unlock subscription-based revenue streams from national health agencies and research institutions. The CDC's collaboration with blood-center networks on Zika and SARS-CoV-2 seroprevalence demonstrated the commercial and public-health value of this data layer.


Blood Screening Market Future Outlook

AI and Machine-Learning Integration in Screening Workflows

Artificial intelligence will move beyond inventory optimization into active screening-result interpretation by 2028–2030. Deep-learning algorithms trained on millions of donor-sample results are demonstrating the ability to flag indeterminate NAT signals with 95%+ concordance to expert manual review, potentially reducing confirmatory testing turnaround from 48 hours to under 6 hours . For the Blood Screening Market, this translates into faster product release, lower discard rates, and a new software-licensing revenue model layered atop existing instrument placements.

Next-Generation Sequencing for Variant Surveillance

NGS-based metagenomic screening — capable of detecting any pathogen without a priori knowledge of the target — is expected to transition from research-use-only to clinical deployment between 2030 and 2033 [7]. The technology addresses a critical gap: conventional NAT panels are blind to novel or engineered pathogens. WHO's International Blood Safety Working Group has identified metagenomic surveillance as a strategic priority, and early pilots at the New York Blood Center and Sanquin (Netherlands) are generating performance data that regulators will use to frame approval pathways for the Blood Screening Market.

Sustainability and Green Blood-Banking Practices

Environmental sustainability is entering the blood-banking agenda as healthcare systems face decarbonization targets. Single-use plastics from screening consumables — estimated at 12,000 metric tons annually across global blood centers — are drawing scrutiny . Manufacturers developing recyclable cartridge housings and reduced-reagent-volume platforms will gain procurement preference under emerging EU green public procurement criteria. The Blood Screening Market will increasingly reward companies that can demonstrate lifecycle carbon-footprint reductions alongside diagnostic performance.

Decentralized and Mobile Screening Architectures

The traditional hub-and-spoke model, where collected units are shipped to a central lab for screening, is being challenged by portable molecular platforms that bring NAT-equivalent testing to the collection point. By 2035, an estimated 20–25% of screening in low-resource settings could occur at mobile or satellite sites rather than centralized laboratories . This architectural shift will restructure the competitive landscape of the Blood Screening Market, favoring companies that offer compact, connectivity-enabled, and cold-chain-independent solutions over those optimized solely for high-throughput centralized operations.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 38% share (2025) Automation refresh cycle; expanded Babesia/bacteria panels
Europe 27% share (2025) EU Blood Directive compliance; PRT integration
Asia-Pacific 10.7% CAGR (2026–2035) National centralization programs; voluntary donor expansion
South America USD 0.24 Billion (2025) PAHO procurement frameworks; paid-to-voluntary transition
Middle East & Africa 8.5% CAGR (2026–2035) PEPFAR-funded HIV screening; cold-chain modernization
Total USD 3.46 Billion (2025) —

The Blood Screening Market exhibits a clear geographic hierarchy, with mature markets in North America and Europe accounting for the majority of revenue, while Asia-Pacific's rapid infrastructure build-out positions it as the principal growth engine through 2035.


North America

Country Key Metric Key Driver
United States 78% of regional share FDA-mandated Babesia and bacterial screening expansion
Canada 14% of regional share Canadian Blood Services automation upgrade
Mexico USD 0.11 Billion (2025) COFEPRIS regulatory alignment with FDA standards


The United States remains the single largest national Blood Screening Market, anchored by the American Red Cross and Vitalant, which collectively process over 13 million donations annually. The 2024 nationwide Babesia screening mandate and the FDA's draft guidance on bacterial testing for platelets have created step-function demand increases for expanded NAT panels. Canada's blood system, centralized under Canadian Blood Services and Héma-Québec, is midway through a CAD 180 Million instrument modernization program expected to conclude by 2028 [17].

Europe

Country Key Metric Key Driver
Germany 9.2% CAGR (2026–2035) Paul-Ehrlich-Institut quality mandates
United Kingdom 22% of regional share NHSBT pathogen-reduction rollout
France USD 0.19 Billion (2025) EFS centralized NAT procurement
Italy 8.8% CAGR (2026–2035) National Blood Centre modernization
Spain USD 0.09 Billion (2025) Regional blood-center consolidation
Nordic Countries 7% of regional share Joint Scandinavian procurement tenders
Russia 8.3% CAGR (2026–2035) Federal blood-service digitization initiative
Rest of Europe USD 0.12 Billion (2025) EU-funded cross-border blood-safety programs


The revised EU Blood, Tissues and Cells Regulation (adopted 2025) mandates expanded viral panels including hepatitis E for all member states, creating a synchronized procurement wave across the Blood Screening Market in Europe [5]. The UK's NHSBT is piloting pathogen-reduction for all platelet concentrates, which is expected to reshape screening-panel economics by allowing selective test de-escalation for PRT-treated components.

Asia-Pacific

Country Key Metric Key Driver
China 32% of regional share CNBG centralized procurement and NAT mandate
India 11.8% CAGR (2026–2035) NBTC voluntary donor expansion and mobile NAT units
Japan USD 0.14 Billion (2025) Japanese Red Cross Society high-throughput screening
South Korea 10.3% CAGR (2026–2035) KFDA enhanced quality-control requirements
ASEAN USD 0.08 Billion (2025) WHO-supported regional screening harmonization
Rest of Asia-Pacific 9.5% CAGR (2026–2035) Bilateral development bank funding for blood safety


Asia-Pacific represents the fastest-growing region in the Blood Screening Market, driven by China's mandate that all blood centers with annual collections exceeding 100,000 units adopt NAT by 2026, and India's National Blood Transfusion Council initiative to establish 300 new model blood banks by 2029 [6]. Japan's mature but highly quality-conscious market continues to invest in advanced automation, with the Japanese Red Cross operating one of the world's most centralized and technology-intensive screening networks.

South America

Country Key Metric Key Driver
Brazil 58% of regional share ANVISA quality enforcement and Hemobras procurement
Argentina 9.1% CAGR (2026–2035) Plan Nacional de Sangre modernization
Rest of South America USD 0.04 Billion (2025) PAHO technical assistance programs


Brazil dominates the South American Blood Screening Market through Hemobras and a network of public hemocenters that processed approximately 3.6 million donations in 2024. ANVISA's progressive alignment with FDA-equivalent quality standards is driving a transition from rapid tests to NAT for first-time donors, while PAHO procurement agreements are making reagent costs more accessible for smaller Andean and Caribbean blood services.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 28% of regional share Vision 2030 healthcare infrastructure investment
UAE USD 0.03 Billion (2025) Dubai Health Authority quality accreditation
South Africa 9.0% CAGR (2026–2035) SANBS and Western Province Blood Service capacity expansion
Egypt 8.7% CAGR (2026–2035) National Blood Transfusion Services centralization
Rest of MEA USD 0.05 Billion (2025) PEPFAR and Global Fund screening procurement [18]


The Middle East & Africa region presents a bifurcated Blood Screening Market: Gulf Cooperation Council states operate sophisticated, well-funded blood centers comparable to European facilities, while sub-Saharan African nations still rely heavily on rapid immunoassays for donor screening. PEPFAR's continued commitment of approximately USD 200 Million annually to HIV testing infrastructure across 15 focus countries sustains baseline demand, and the Global Fund's 2024–2026 allocation cycle includes dedicated transfusion-safety components for the first time [18].


Blood Screening Market By Region, 2025-2035

Blood Screening Market Segmentation

By Product

Segment Key Metric Primary Demand Driver
Reagents and Kits 51% share (2025) High consumable intensity per donation unit
Instruments 10.6% CAGR (2026–2035) Automation refresh cycle at large blood centers
Software and Services USD 0.21 Billion (2025) LIMS integration and data-analytics adoption


Reagents and kits remain the revenue backbone of the Blood Screening Market, reflecting the consumable-driven business model where each of the estimated 120 million global donation units requires a full panel of NAT and immunoassay reagents. Closed-system reagent contracts — where instrument placement is tied to exclusive reagent purchase — ensure high recurring revenue for manufacturers like Grifols, Roche, and Abbott.

The instruments segment is gaining momentum as blood centers enter a synchronized replacement cycle. Systems installed during the 2012–2016 NAT adoption wave are now approaching end-of-life, creating a concentrated procurement window. Next-generation platforms emphasize walk-away automation, reduced sample-volume requirements, and built-in connectivity for real-time result reporting to national hemovigilance databases.

By Technology

Segment Key Metric Primary Demand Driver
Nucleic Acid Amplification Testing (NAT) 45% share (2025) Regulatory mandate for molecular-level pathogen detection
Immunoassay USD 0.92 Billion (2025) Cost-effective high-volume serology screening
Rapid Tests 7.8% CAGR (2026–2035) Point-of-collection use in low-resource settings
Next-Generation Sequencing 11.9% CAGR (2026–2035) Emerging-pathogen surveillance and variant detection


NAT dominates the technology landscape of the Blood Screening Market because regulatory agencies in over 80 countries now require molecular testing for HIV and hepatitis viruses in donated blood. The technology's ability to detect viral nucleic acids during the pre-seroconversion window period — typically 5–10 days for HIV and 20–25 days for HCV — makes it indispensable for closing the residual-risk gap that immunoassays alone cannot address.

Immunoassay platforms continue to serve a complementary role, particularly for blood-group serology and confirmatory antibody testing. Rapid tests, while limited in sensitivity, remain the primary screening modality in countries where centralized NAT infrastructure has not yet been established, serving an essential function in approximately 40 WHO member states across Africa and Southeast Asia.

By Screening Target

Segment Key Metric Primary Demand Driver
Infectious Disease Panels 53% share (2025) Mandatory HIV, HBV, HCV screening across all jurisdictions
Blood Group Typing USD 0.72 Billion (2025) Pre-transfusion compatibility and Rh-D determination
Other Screening Targets 9.4% CAGR (2026–2035) Sickle-cell trait, CMV, malaria parasite detection


Infectious disease panels represent the largest screening-target category in the Blood Screening Market, driven by universal regulatory requirements for HIV, HBV, and HCV testing across virtually every jurisdiction with an organized blood supply. Panel scope continues to expand — Babesia, hepatitis E, and dengue are the most recently added analytes in developed markets, while Chagas disease testing remains mandatory throughout Latin America.

By End-User

Segment Key Metric Primary Demand Driver
Blood Banks 63% share (2025) Centralized high-volume donor screening operations
Hospitals USD 0.48 Billion (2025) In-house transfusion services and emergency screening
Clinical Laboratories 11.0% CAGR (2026–2035) Reference testing and confirmatory assay demand


Blood banks — including national blood services, Red Cross/Red Crescent societies, and independent community blood centers — process the vast majority of donations and therefore represent the dominant end-user segment in the Blood Screening Market. Their procurement patterns are characterized by long-term reagent-rental contracts, centralized tender processes, and high sensitivity to per-test cost optimization.

Clinical laboratories are the fastest-growing end-user segment as reference labs expand their transfusion-medicine testing portfolios and hospital systems increasingly outsource confirmatory and supplemental testing to specialized facilities.


Competitive Benchmarking

The Blood Screening Market exhibits medium market concentration, with the top five players commanding an estimated 60–68% combined revenue share. The Herfindahl-Hirschman Index (HHI) is estimated at approximately 1,200–1,400, indicating a moderately concentrated competitive structure. Competition centers on closed-system reagent-instrument contracts, regulatory approval breadth, and installed-base lock-in at major blood centers.

Company Est. Revenue Share Range Key Offerings for Blood Screening Market Strategic Positioning
Grifols S.A. ~15–19% Procleix Panther system; TMA-based NAT assays Dominant in plasma-center screening; global installed base
F. Hoffmann-La Roche AG ~12–16% cobas 6800/8800; multiplex NAT panels High-throughput centralized screening; broad menu
Abbott Laboratories ~10–14% Alinity s; Architect immunoassay platform Integrated immunoassay and NAT; emerging-market reach
Bio-Rad Laboratories ~7–10% IH-500 system; gel-card blood typing Blood-group typing and immunohematology leader
Ortho Clinical Diagnostics ~5–8% Ortho Vision analyzer; VITROS immunodiagnostics Transfusion medicine and blood-bank automation
Immucor (Werfen) ~4–7% NEO Iris; Echo Lumena; PreciseType HEA Molecular immunohematology and reference testing
Hologic Inc. ~3–6% Panther Fusion; Aptima assays NAT for blood screening through Grifols partnership
Quotient Limited ~2–4% MosaiQ system; microarray-based typing Next-gen multiplexed donor testing platform
Beckman Coulter (Danaher) ~2–4% DxH series; immunoassay analyzers Hospital-based transfusion screening
Siemens Healthineers ~2–3% Atellica; ADVIA Centaur immunoassay Broad diagnostics portfolio; hospital integration


Recent News & Developments

  • May 2025: Roche unveiled the Elecsys PRO-C3 test, a quick test that reduces reliance on invasive biopsies by identifying liver fibrosis in 18 minutes.The first human trial of artificial blood based on hemoglobin vesicles, which preserve for two years at room temperature without blood-group matching, started in Japan in March 2025.
  • February 2025: The Tina-quant Lp(a) Gen.2 test, the first blood test in the United States to report Lp(a) in molar units, received FDA 510(k) clearance in February 2025.
  • January 2025: SpinChip Diagnostics, a portable immunoassay platform that provides whole-blood results in ten minutes, was acquired by bioMérieux.


Blood Screening Market Report Scope

Parameter Details
Market Scope Global Blood Screening Market covering products, technologies, screening targets, end-users, and regions
Study Period 2021–2035
CAGR (Forecast Period) 9.0% (2026–2035)
Base Year 2025 — USD 3.46 Billion
2026 Estimate USD 3.77 Billion
2035 Projection USD 8.19 Billion
Fastest Growing Region Asia-Pacific (10.7% CAGR)
Fastest Growing End-User Clinical Laboratories (11.0% CAGR)
Companies Profiled 10 (Grifols, Roche, Abbott, Bio-Rad, Ortho Clinical Diagnostics, Immucor, Hologic, Quotient, Beckman Coulter, Siemens Healthineers)
Valuation Currency USD Billion

FAQs

How do reagent-rental contracts affect competitive switching for blood centers?
Reagent-rental agreements typically lock blood centers into 5–7-year exclusive supply terms tied to instrument placement. Breaking these contracts early incurs penalties that often exceed 30% of remaining contract value, making mid-cycle vendor switches rare [23].
What validation requirements apply when a blood center transitions from immunoassay to NAT screening?
Regulatory agencies require parallel testing of 1,000–5,000 donor samples on both old and new platforms before full cutover. This validation phase typically spans 3–6 months and costs USD 150,000–300,000 per analyte [9].
How does pathogen-reduction technology change the screening panel economics for platelet concentrates?
PRT-treated platelets may qualify for reduced bacterial testing under certain regulatory frameworks. This can lower per-unit screening costs by 10–15%, partially offsetting the USD 20–30 per-unit PRT processing expense [10].
What role does the Blood Screening Market play in pandemic preparedness infrastructure?
Screening platforms serve as sentinel surveillance networks, detecting emerging pathogens in asymptomatic donors before clinical cases surface. This dual-use capability attracted federal biosurveillance funding exceeding USD 80 Million in the U.S. during 2023–2024 [4].
How are blood centers in the Blood Screening Market addressing cybersecurity risks in connected screening platforms?
Connected instruments transmitting results to centralized databases face HIPAA and GDPR compliance mandates. Most large centers now require ISO 27001–certified middleware and encrypted data pipelines for all screening-platform integrations [24].
What procurement strategies optimize per-test costs in the Blood Screening Market for mid-sized blood centers?
Group-purchasing organizations and regional consortia negotiate volume-tiered pricing that can reduce reagent costs by 15–25% versus individual contracts. Joint tenders among 3–5 centers typically reach the volume thresholds needed for tier-one pricing [16].
How do emerging Babesia and hepatitis E screening requirements expand the addressable Blood Screening Market?
Each new mandated analyte adds USD 2–5 per donation unit in incremental reagent spend. Nationwide Babesia screening alone created an estimated USD 120 Million annual revenue increment in the United States starting in 2024 [2].    
What is the current size of the blood screening market?
The blood screening market reached USD 3.46 billion in 2025 and is projected to reach USD 8.19 billion by 2035.
What is the CAGR of the blood screening market?
The blood screening market is projected to grow at a CAGR of 9.0% during the forecast period 2026–2035.
Which region leads the blood screening market?
North America holds the largest share at 38%, while Asia-Pacific is the fastest-growing region at 10.7% CAGR.
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Kinjoll Dey LinkedIn Senior Research Analyst
He is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Kinjoll is comfortably versed in data centric research backed by healthcare educational background. He leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. His key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, he showcases extensive affinity towards learning new skills and remain fascinated in implementing them.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical and transfusion medicine journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Biologics Evaluation and Research (CBER), European Medicines Agency (EMA), World Health Organization (WHO) Blood Safety and Availability Programme, US Centers for Disease Control and Prevention (CDC) Division of Healthcare Quality Promotion, Clinical Laboratory Improvement Amendments (CLIA) database, American Association of Blood Banks (AABB), International Society of Blood Transfusion (ISBT), America's Blood Centers, European Centre for Disease Prevention and Control (ECDC), National Institutes of Health (NIH), National Center for Biotechnology Information (NCBI/PubMed), and national blood service reports from key markets.

These sources were employed to gather data on the prevalence of infectious diseases (HIV, HBV, HCV, and syphilis), regulatory approval data for nucleic acid amplification tests (NAT) and enzyme-linked immunosorbent assay (ELISA) platforms, clinical safety studies, transfusion-transmitted infection (TTI) screening protocols, and market landscape analysis for reagents, kits, and automated screening instruments. Additionally, blood donation statistics were utilized.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. In-vitro diagnostic (IVD) manufacturers, blood screening platform developers, and reagent producers were among the supply-side sources, which included CEOs, VPs of Research & Development, global regulatory affairs managers, and commercial directors. Blood bank medical directors, hospital transfusion service managers, hematologists, clinical laboratory directors, infectious disease specialists, and procurement leads from independent blood centers, hospital-based blood banks, and diagnostic laboratories comprised demand-side sources. Market segmentation was validated across NAT, ELISA, and next-generation sequencing technologies; product pipeline timelines for multiplex screening assays were confirmed; and insights on blood donation screening volumes, reimbursement dynamics for transfusion medicine, and adoption patterns of automated molecular platforms were gathered through primary research.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

• By Region: North America (32%), Europe (25%), Asia-Pacific (33%), Rest of World (10%)


Market Size Estimation

The revenue mapping and screening procedure volume analysis across blood banks and transfusion centers were used to derive the global market valuation. The methodology comprised the following:

• Identification of over 50 main manufacturers in North America, Europe, Asia-Pacific, and Latin America who specialize in blood screening technologies

• Product mapping across nucleic acid amplification tests (NAT), enzyme-linked immunosorbent assays (ELISA), next-generation sequencing (NGS), rapid tests, and western blot technologies

• Segment-specific analysis of reagents and kits (recurring revenue) and instruments (capital equipment) in hospital blood banks, independent blood centers, and clinical laboratories

• Examination of the annual revenues that have been reported and modeled for the blood screening and transfusion safety portfolios

• In 2024, the coverage of manufacturers will account for 75-80% of the global market share.

• Segment-specific valuations for infectious disease screening (HIV, HBV, HCV, Zika, syphilis), blood typing, and immunohistochemistry applications are derived through extrapolation using bottom-up (blood donation screening volume × average selling price by country/region) and top-down (manufacturer revenue validation) approaches.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















