Automotive Smart Display Market (2026 - 2035)

Automotive Smart Display Market Research Report By Display Technology (TFT-LCD, OLED, Head-Up Display Units, Micro-LED and Emerging, MiniLED / MicroLED), By Application (Center Stack Display, Digital Instrument Cluster, Head-Up Display, Rear-Seat Entertainment, Digital Mirror Display, By Product Type, Center Stack Display, Instrument Cluster Display, Head-Up Display, Rear-Seat Entertainment Display), By Display Size (Less than or Equal to 5-Inch, 6 to 10 Inch, Above 10 Inches), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), By Sales Channel (OEM, Aftermarket) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
ID: MRFR/AT/2590-HCR 110 Pages Shubham Munde, Sejal Akre Last Updated: October 16, 2026
Automotive Smart Display Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)10.3%
2025 Market SizeUSD 10.40 Billion
2035 Market SizeUSD 27.6 billion
Key Players
Continental AG
LG Display
Panasonic Automotive
DENSO Corporation
Robert Bosch GmbH
Visteon Corporation
Opportunities
  • Projection-Based Forward Vision Systems
  • In-Cabin Commerce and Data Monetization
  • Emerging-Market Cost-Down Architectures

Automotive Smart Display Market Summary

The Automotive Smart Display Market closed 2025 at roughly USD 10.4 billion and enters 2026 at approximately USD 11.5 billion, on track to reach USD 27.6 billion by 2035 at a 10.3% CAGR across the forecast window. Two catalysts anchor that trajectory. Euro NCAP's 2026 protocol revision, which ties occupant-monitoring and driver-attention scoring to cabin display architecture, has forced a rethink of instrument panels across every European nameplate [1]. Separately, capital is arriving in volume: global automotive cockpit electronics capex crossed USD 22 billion in 2024, with display modules absorbing close to a fifth of that spend.

Analog gauges and single-function 7-inch center stacks are disappearing fast. Replacing them are pillar-to-pillar glass assemblies, digital clusters running configurable graphics layers, and windshield projection units that place navigation cues in the driver's forward view. China's MIIT intelligent connected vehicle roadmap alone earmarked CNY 15 billion in supporting funds through 2027 for cockpit and perception electronics [3]. The Automotive Smart Display Market is, in effect, migrating from a components business to a software-defined platform business.

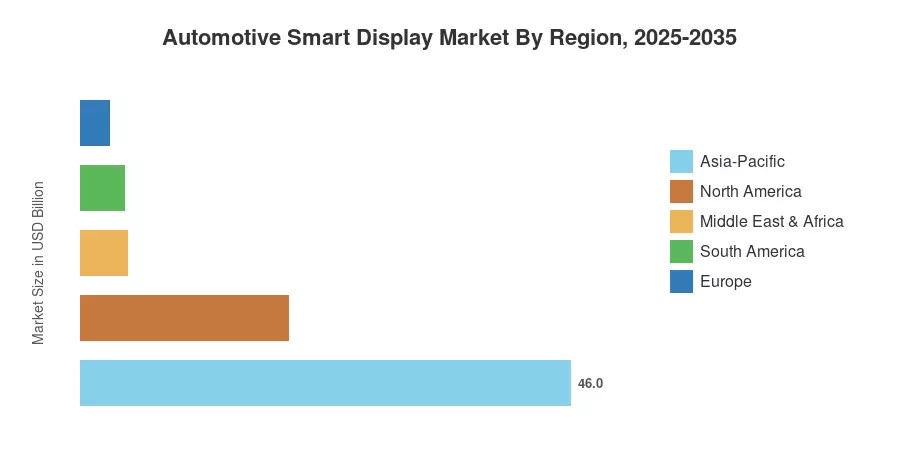
Asia-Pacific dominates with roughly 46% of 2025 revenue and is simultaneously the fastest-growing region at 12.1% CAGR — an unusual combination that reflects both panel manufacturing concentration and domestic EV adoption. Europe holds second position at about 26%, propelled by premium-segment differentiation and regulatory pressure. Expect the gap between Asia-Pacific and everyone else to widen through 2030 within the Automotive Smart Display Market.


Key Report Takeaways

• By Display Technology

  • TFT-LCD panels retained approximately 61% of 2025 revenue in the Automotive Smart Display Market, sustained by cost advantage in mid-tier vehicles
  • OLED display modules are expanding at a 17.4% CAGR, the fastest technology growth path tracked in this study


• By Product Type


  • Head-up display units generated close to USD 2.1 billion in 2025 shipments
  • Center-stack applications delivered roughly USD 4.3 billion in 2025


• By Vehicle Type

  • Passenger cars accounted for nearly 84% of Automotive Smart Display Market revenue in the base year
  • Commercial vehicle display demand is compounding at 9.6% annually as fleet telematics consolidates onto in-cab screens


• By Region

  • Asia-Pacific commanded about 46% share in 2025
  • North America is growing at 9.4% CAGR through 2035
  • Europe contributed approximately USD 2.7 billion in base-year revenue


Market Size and Forecast (2021–2035)

Figures below blend tier-one supplier disclosures, panel-maker shipment data, OEM production forecasts, and bottom-up per-vehicle content modelling. Historical years reconcile against reported segment revenue from major display suppliers; forecast years apply vehicle-production baselines multiplied by content-per-vehicle escalation curves differentiated by region and price tier.
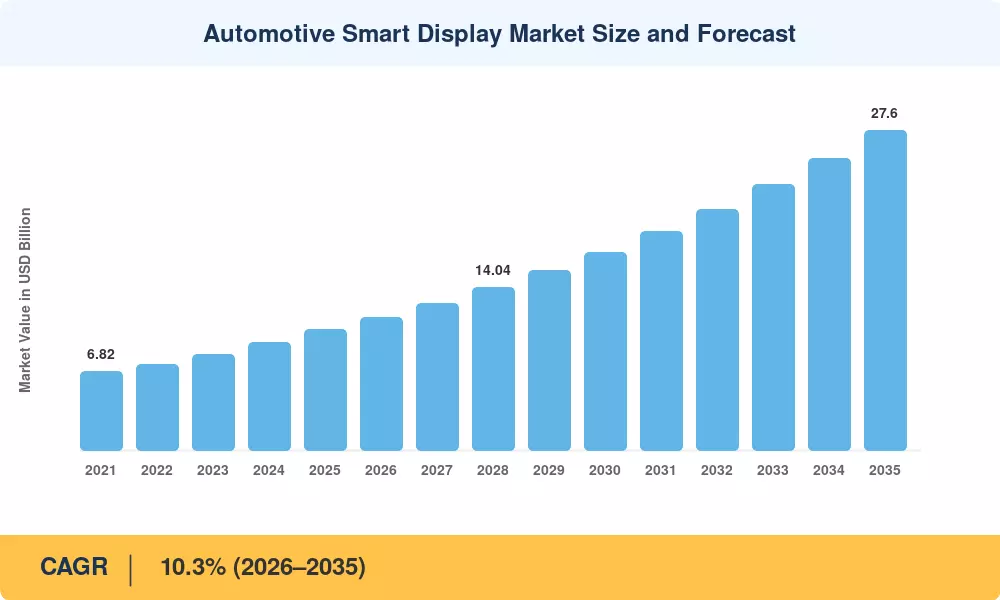
Automotive Smart Display Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
EV platform proliferation 2.6 Global Medium-term (2–4 yr)
Safety and driver-monitoring regulation 1.9 Europe, North America Short-term (≤2 yr)
Software-defined vehicle architectures 1.7 Global Long-term (≥4 yr)
Display content-per-vehicle escalation 1.5 Asia-Pacific Medium-term (2–4 yr)
Premium-segment cabin differentiation 1.1 Europe, Middle East Short-term (≤2 yr)
Panel manufacturing cost decline 0.9 Asia-Pacific Long-term (≥4 yr)
Fleet and commercial telematics integration 0.6 North America Medium-term (2–4 yr)


EV Platform Proliferation

OEMs have used glass to replace the void left by the lack of a conventional powertrain gauge set in battery-electric designs. In 2024, the International Energy Agency estimated that 17 million electric cars were sold worldwide, accounting for more than one in five new automobile sales [5]. Because range, charging state, and energy flow visualization require screen real estate that mechanical instruments cannot supply, each of those vehicles has display content that is, on average, 38% more valuable than a comparable combustion model.


Safety and Driver-Monitoring Regulation

Here, Regulation is taking a unique approach by attempting to lessen distraction while also increasing the number of screens. The EU General Safety Regulation (2019/2144) requires sophisticated distraction recognition starting in July 2026 and driver sleepiness and attention warning systems on all new type approvals starting in July 2024 [1]. OEMs are forced by compliance to switch from hidden menu items to cluster-integrated alert surfaces and forward-projection warnings. Safety-critical features concealed behind touchscreen submenus are now penalized by Euro NCAP's scoring, which is subtly changing how the Automotive Smart Display Market distributes pixels between cluster and center stack.


Software-Defined Vehicle Architectures

Zonal computing consolidates what used to be a dozen ECUs into two or three domain controllers, and the display becomes the primary human-facing output of that consolidation. Roughly 43% of vehicles produced in 2025 supported some form of remote software update, up from 12% in 2021. That capability changes the commercial logic entirely: a screen shipped in 2026 can receive new interface layers in 2029, which justifies specifying more capable hardware at the factory gate.

Display Content-Per-Vehicle Escalation

Average display area per vehicle reached 0.31 square metres globally in 2025, against 0.18 in 2021. Chinese domestic brands drove the sharpest increase, with several mid-priced NEV models now shipping three or four screens as standard equipment. That escalation is not confined to premium tiers, which is what separates this cycle from earlier infotainment booms.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Driver distraction regulatory backlash −1.4 Europe Medium-term (2–4 yr)
Automotive-grade qualification cost −1.0 Global Long-term (≥4 yr)
Display panel supply concentration −0.8 Global Short-term (≤2 yr)
Cybersecurity and update liability −0.6 Europe, North America Medium-term (2–4 yr)
Entry-segment price sensitivity −0.5 South America, Africa Long-term (≥4 yr)


Driver Distraction Regulatory Backlash

A few regulators have started to oppose screen maximalism. According to Euro NCAP, starting in 2026, physical controls for indicators, wipers, hazard lights, and horns—functions that a number of OEMs have moved to touch interfaces—will be rewarded in its scoring system [10]. In 2024, automakers including Hyundai and Volkswagen publicly changed their minds about all-touch interiors. Although it hasn't hindered the increase of display area for secondary tasks, the short-term impact is a ceiling on screen substitution for principal controls.


Automotive-Grade Qualification Cost

Thermal cycling from −40°C to 105°C, 10-year sun exposure testing, and AEC-Q100 and AEC-Q200 qualifying increase display module costs by about 20–30% when compared to consumer equivalents [6]. Cycles of qualification last between eighteen and twenty-four months. This delay is significant for new technologies. For example, a panel technology that is commercially viable in smartphones in 2024 is usually not able to enter volume vehicle production before 2027.


Display Panel Supply Concentration

Fewer than eight fabs worldwide supply the majority of automotive-qualified panels, and most sit in three countries [11]. That concentration produced allocation problems during 2021–2022 and remains a structural exposure. OEMs have responded with dual-sourcing mandates and longer inventory buffers, both of which raise working capital requirements across the supply chain.


Automotive Smart Display Market Opportunities

Projection-Based Forward Vision Systems

Windshield projection with depth-correct overlays remains under 6% attach rate globally, yet commands per-unit pricing four to six times a comparable cluster panel. HUD augmented reality smart display units are moving from flagship sedans into mid-tier SUVs as optical engine costs fall, and the addressable gap between current attach rates and premium-segment saturation represents several billion dollars of incremental content.

In-Cabin Commerce and Data Monetization

Screens are becoming transaction surfaces. Charging payments, parking reservations, drive-through ordering, and subscription feature unlocks all route through the center stack, and OEMs are negotiating revenue-share arrangements with service providers. Stellantis has publicly targeted EUR 20 billion in annual software-enabled revenue by 2030 [14], a figure that presumes the display becomes a storefront rather than a control panel.

Emerging-Market Cost-Down Architectures

India, Brazil, Indonesia, and Vietnam together will add roughly 9 million annual vehicle sales by 2032, mostly in price bands below USD 20,000 [13]. Suppliers who can deliver a qualified 10-inch cluster-and-stack pair below USD 90 will capture volume that premium-focused competitors cannot reach. India's PLI scheme for automotive components, worth INR 259 billion, directly subsidises localised display module assembly [15].

Aftermarket and Retrofit Channels

Roughly 280 million vehicles on European and North American roads carry pre-2018 infotainment [16]. Retrofit display units with modern connectivity address a replacement pool that OEM channels ignore entirely, and margins in this channel typically run 8–12 points above OE supply.

Commercial Fleet Cockpit Standardisation

Logistics operators are consolidating fragmented telematics hardware onto single certified in-cab displays. The FMCSA electronic logging device mandate created the installed base; fleet management software consolidation is now driving replacement toward larger, multi-application screens [9].


Automotive Smart Display Market Future Outlook

Generative Interfaces and In-Cabin AI

Voice and conversational agents will restructure what screens display. Rather than menu hierarchies, expect context-surfaced cards — the display shows what the assistant inferred you need. Automotive AI software spending is projected to triple between 2025 and 2032, and interface hardware specifications are already being written to accommodate persistent inference workloads.

Platform Economics and Feature Licensing

Hardware margins compress; software margins do not. OEMs are provisioning display and compute capability at build time and charging for activation later. This inverts traditional supplier relationships, where display makers must now support feature sets their customers have not yet monetised.

Electrification Supercycle

IEA projections place electric vehicles at over 40% of global sales by 2030 under stated policies [5]. Because electric platforms carry structurally higher display content, electrification alone would grow the Automotive Smart Display Market even with flat total vehicle production. That decoupling from unit volumes is the single most important structural feature of this decade.

Circularity and Material Disclosure

The EU End-of-Life Vehicles Regulation revision proposes recycled content thresholds and dismantling requirements that reach into electronics assemblies [18]. Bonded glass laminates and rare-earth backlight components complicate compliance. Suppliers who solve for disassembly early will hold a procurement advantage by 2030.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
Asia-Pacific 46.0% share Panel fabs, NEV cockpit content, domestic tier-one scale-up
Europe USD 2.70 B Regulatory compliance, premium differentiation
North America 19.5% share Pickup and SUV large-format screens, fleet telematics
South America 4.1% share Localisation, entry-tier infotainment
Middle East & Africa 4.4% CAGR premium skew Luxury imports, smart-city vehicle programmes
Total 100% / USD 10.40 B —


Asia-Pacific

Country Metric Key Driver
China 58% of regional revenue NEV cockpit content escalation
Japan USD 0.71 B Tier-one supplier export base
South Korea 13.8% CAGR OLED panel manufacturing leadership
India 7.2% of regional revenue PLI-backed local assembly
Rest of Asia-Pacific USD 0.34 B ASEAN production expansion


China's position rests on vertical integration that no other market matches — panel fabrication, module assembly, and vehicle production sit within a few hundred kilometres of each other. MIIT's intelligent connected vehicle pilot programme designated 20 cities for coordinated deployment in 2024 [3], and domestic NEV brands now treat screen count as a marketing specification. South Korea contributes disproportionately through panel supply rather than vehicle volume.

Europe

Country Metric Key Driver
Germany 34% of regional revenue Premium OEM cabin programmes
France USD 0.36 B Tier-one systems integration
United Kingdom 8.9% CAGR Luxury and performance segments
Italy 9.5% of regional revenue Design-led interior differentiation
Rest of Europe USD 0.51 B Central European assembly base


Regulation shapes European demand more than consumer preference does. The General Safety Regulation timeline through July 2026 compels attention-monitoring integration [1], while Euro NCAP's physical-control scoring change pulls in the opposite direction [10]. German premium OEMs have resolved the tension with hybrid layouts — wide glass surfaces paired with retained hard switches for safety-critical functions.

North America

Country Metric Key Driver
United States 87% of regional revenue Full-size pickup and SUV screen inflation
Canada USD 0.16 B Cross-border assembly integration
Mexico 11.2% CAGR Tier-one module manufacturing growth


Screen size in North America tracks vehicle size. Full-size pickups — over 2.4 million units annually — now routinely carry 13-inch or larger center displays, and this segment alone contributes more display area than several European countries combined. Mexico's role is manufacturing rather than consumption, with USMCA regional content rules encouraging module assembly relocation.

South America

Country Metric Key Driver
Brazil 71% of regional revenue Flex-fuel model refresh cycles
Argentina USD 0.05 B Regional assembly agreements
Rest of South America 8.1% CAGR Import liberalisation


Brazil's Mover programme, which conditions tax incentives on technology content and emissions performance, has nudged domestic assemblers toward digital cockpits in models that previously shipped with analog clusters [13]. Price sensitivity keeps average display size well below global norms, but attach rates are climbing quickly from a low base.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 32% of regional revenue Vision 2030 mobility programmes
United Arab Emirates USD 0.09 B Luxury import concentration
South Africa 10.4% CAGR Local assembly for export
Rest of MEA 21% of regional revenue Fleet and commercial demand


Gulf demand skews heavily premium. Saudi Arabia's PIF-backed Ceer venture targets domestic EV production from 2026 with cockpit specifications benchmarked against Chinese NEV standards rather than legacy regional norms [17]. South Africa's automotive production incentive programme supports export-oriented assembly, which imports European specification levels into local supply chains.


Automotive Smart Display Market By Region, 2025-2035

Automotive Smart Display Market Segmentation

By Display Technology

Segment Metric (2025) Primary Demand Driver
TFT-LCD 61.0% share Cost efficiency at volume
OLED 17.4% CAGR Premium contrast and form factor
Head-Up Display Units USD 2.10 B Safety and eyes-forward regulation
Micro-LED and Emerging 21.6% CAGR Brightness and longevity in harsh cabins


TFT-LCD remains the volume backbone of the Automotive Smart Display Market, and reports of its displacement are premature — automotive qualification cycles and cost structures favour incumbency. What is changing is TFT sophistication: local dimming, higher pixel density, and curved lamination now appear in panels that would have been flat 8-inch units five years ago.

OLED is winning where design matters more than cost. Flexible substrates allow wrap-around dashboard geometries that rigid glass cannot achieve, and premium OEMs have accepted the burn-in mitigation engineering required for automotive duty cycles. Growth here is share-shift rather than category expansion.

By Application

Segment Metric (2025) Primary Demand Driver
Center Stack Display USD 4.30 B Infotainment and connectivity convergence
Digital Instrument Cluster 29.0% share EV powertrain visualisation needs
Head-Up Display 14.9% CAGR ADAS alert surfacing
Rear-Seat Entertainment 8.0% share Premium and ride-hailing fitment
Digital Mirror Display 15.8% CAGR Aerodynamic and regulatory approval spread


Center stack applications dominate the Automotive Smart Display Market by absolute revenue and will continue to, though growth rates now lag the cluster and projection categories. Digital clusters are the more interesting story: they are becoming mandatory rather than optional, since electric powertrains offer nothing meaningful for an analog needle to indicate.

By Vehicle Type

Segment Metric (2025) Primary Demand Driver
Passenger Cars 84.0% share Mass-market digital cockpit standardisation
Light Commercial Vehicles 9.6% CAGR Last-mile fleet telematics
Heavy Commercial Vehicles USD 0.72 B Driver retention and cabin comfort investment


Passenger Cars remain the dominant segment of the Automotive Smart Display Market because high production volumes and increasing display content per vehicle continue to support widespread adoption of digital clusters, center displays, and integrated infotainment systems. Light Commercial Vehicles represent the fastest-growing segment, supported by rising fleet electrification, connected-vehicle adoption, and growing demand for larger driver-information and telematics displays. Heavy Commercial Vehicles maintain steady demand as fleet operators increasingly adopt advanced cockpit systems, navigation, safety alerts, and productivity-focused displays.


By Sales Channel

Segment Metric (2025) Primary Demand Driver
OEM 91.0% share Factory-integrated architecture requirements
Aftermarket 11.3% CAGR Retrofit of pre-2018 vehicle parc


OEM remains the dominant segment of the Automotive Smart Display Market because factory-installed displays are increasingly integrated into vehicle architectures, supporting digital instrument clusters, infotainment systems, connectivity, and advanced driver-assistance functions. Aftermarket is the fastest-growing segment, driven by demand for retrofit displays, smartphone connectivity, navigation upgrades, and modern infotainment features across the large installed base of older vehicles. As consumers seek connected functionality without replacing their vehicles, aftermarket solutions are gaining traction alongside continued OEM integration.


Competitive Benchmarking

The Automotive Smart Display Market is moderately concentrated. Estimated HHI sits near 950, with the top five suppliers holding a combined 42–48% of global revenue. Below that tier, competition fragments sharply across regional module assemblers and panel specialists, and Chinese domestic tier-ones have compressed pricing in the mid-range since 2023. Vertical integration is the defining strategic divide — suppliers who control panel fabrication behave very differently from those who assemble purchased glass.

Company Est. Revenue Share Range Key Offerings for Automotive Smart Display Market Strategic Positioning
Continental AG ~9–12% Curved clusters, projection HUD, integrated cockpit domains Full-stack cockpit integrator
LG Display ~8–11% Automotive OLED and LTPS panel supply Panel technology leader
Panasonic Automotive ~7–9% Cockpit domain controllers, center stack systems Software-hardware convergence
DENSO Corporation ~6–9% Instrument clusters, HUD optical engines Japanese OEM incumbency
Robert Bosch GmbH ~6–8% Curved displays, haptic touch surfaces Systems engineering depth
Visteon Corporation ~5–7% SmartCore cockpit domain, digital clusters Independent cockpit specialist
Samsung Display ~4–6% Automotive OLED, flexible substrates Advanced panel manufacturing
BOE Technology ~4–6% Automotive TFT and mini-LED panels Cost-competitive volume supply
Nippon Seiki ~3–5% HUD units, combination meters Projection optics specialist
Desay SV Automotive ~3–5% Integrated cockpit modules for NEV platforms Chinese domestic scale


Recent News & Developments

  • LG Display (March 2024): Announced expanded automotive OLED capacity at its Paju facility, targeting tandem-structure panels with improved lifetime for cabin duty cycles — a direct response to burn-in objections from European OEMs [19].
  • European Commission (July 2024): Driver drowsiness and attention warning requirements took effect for all new EU vehicle registrations under GSR 2019/2144, embedding monitoring output into cluster design [1].
  • Continental and Ambarella (January 2024): Partnered on assisted-driving software integrated with cockpit display output, linking perception stacks directly to driver-facing surfaces [20].
  • Euro NCAP (March 2024): Confirmed that 2026 protocols will reward physical controls for five core functions, prompting several OEMs to revise 2026–2027 interior programmes [10].
  • BOE Technology (September 2024): Commissioned an automotive-dedicated module line in Chengdu aimed at large-format curved assemblies for domestic NEV customers [21].
  • Visteon (May 2025): Reported cockpit domain controller wins with two North American OEMs, extending its independent-supplier position against vertically integrated rivals [22].
  • Bosch (October 2024): Unveiled a haptic-feedback touch surface intended to satisfy tactile-confirmation requirements without reverting to mechanical switches [23].
  • Ministry of Industry and Information Technology, China (June 2024): Designated 20 cities for intelligent connected vehicle pilot deployment, with cockpit electronics named among supported technology categories [3].


Automotive Smart Display Market Report Scope

Report Attribute/Metric Details
Market Scope Global automotive display hardware and integrated cockpit display modules across OEM and aftermarket channels
Study Period 2021-2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 10.40 Billion
Market Size in 2035 USD 27.6 billion
CAGR (2026–2035) 10.3%
Fastest Growing Segments Micro-LED and emerging technologies; digital mirror displays; aftermarket channel
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled Continental, LG Display, Panasonic Automotive, DENSO, Bosch, Visteon, Samsung Display, BOE, Nippon Seiki, Desay SV
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

What warranty terms should procurement teams expect when sourcing for the Automotive Smart Display Market?
Standard OEM display warranties run 5 years or 100,000 kilometres, with pixel-defect thresholds specified separately from module failure. Negotiate optical bonding delamination coverage explicitly — it is the most common exclusion [6].
How do integration timelines differ between cluster and projection systems?
Projection units require 6–9 months of additional windshield co-development because the glass wedge angle must be tuned per model. Clusters integrate on standard 18-month component timelines [23].
Which cybersecurity certifications matter for display suppliers?
UNECE R155 compliance is mandatory for vehicle type approval in over 60 markets, and OEMs increasingly flow the requirement down to display module suppliers [12]. ISO/SAE 21434 process certification is the practical evidence buyers request.
Is vertical panel integration a durable advantage in the Automotive Smart Display Market?
It secures allocation during shortages but locks capital into specific technologies. Independent integrators switch panel sources faster when a technology shifts, which has proven valuable during the LCD-to-OLED transition [22].
What sunlight readability specification should buyers insist on?
Demand 1,000 nits minimum for center stacks and 1,500 nits for projection systems measured post-lamination, not at panel level [6]. Panel-level figures routinely overstate delivered brightness by 20–30%.
How does the Automotive Smart Display Market handle end-of-production spare part supply?
Suppliers typically commit to 10–15 years of service parts after production ends. Confirm whether that covers the display controller silicon, which often reaches end-of-life earlier than the panel [21].
Do digital mirror systems face different approval requirements?
Yes. UNECE Regulation 46 governs camera monitor systems separately from interior displays, with specific latency and field-of-view requirements [25]. Approval is not automatic in all markets, notably parts of North America.    
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, technical standards publications, peer-reviewed automotive engineering journals, industry white papers, and authoritative transportation and technology organizations. Key sources included the US Department of Transportation (DOT), National Highway Traffic Safety Administration (NHTSA), European Commission Mobility and Transport Directorate, Japan Ministry of Land, Infrastructure, Transport and Tourism (MLIT), China Ministry of Industry and Information Technology (MIIT), International Organization for Standardization (ISO) for automotive standards, Society of Automotive Engineers (SAE International), Consumer Technology Association (CTA), International Energy Agency (IEA) for EV adoption data, OICA (International Organization of Motor Vehicle Manufacturers) for vehicle production statistics, IHS Markit (MRFR Mobility) for automotive forecasts, Eurostat Transport Database, US Bureau of Transportation Statistics, and national automotive industry associations from Germany (VDA), Japan (JAMA), South Korea (KAMA), and China (CAAM). These sources were used to collect vehicle production data, ADAS regulatory frameworks, display technology standards, connected car adoption trends, and market landscape analysis for LCD, OLED, MicroLED, and Digital Light Processing technologies across instrument clusters, center stack displays, head-up displays, and rear seat entertainment systems.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Product Development, heads of automotive electronics divisions, sales directors from tier-1 automotive display manufacturers, HUD experts, and semiconductor suppliers were examples of supply-side sources. Chief engineers, heads of cockpit development, procurement leaders, and HMI (human-machine interface) directors from OEMs (original equipment manufacturers), tier-1 suppliers, EV startups, and commercial vehicle manufacturers were examples of demand-side sources. In addition to gathering information on platform adoption trends, pricing tactics, and supply chain dynamics, primary research verified technological roadmap dates and validated market segmentation.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (33%), Others (39%)

By Region: North America (32%), Europe (30%), Asia-Pacific (35%), Rest of World (3%)


Market Size Estimation

Global market valuation was derived through revenue mapping and vehicle unit analysis. The methodology included:

Identification of 50+ key manufacturers and tier-1 suppliers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across Liquid Crystal Display (LCD), Organic Light Emitting Diode (OLED), MicroLED, and Digital Light Processing (DLP) technologies

Analysis of reported and modeled annual revenues specific to automotive smart display portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (vehicle production volume × display units per vehicle × ASP by region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for instrument clusters, center stack displays, head-up displays, and rear seat entertainment systems across passenger cars, light commercial vehicles, heavy commercial vehicles, and electric vehicles

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















