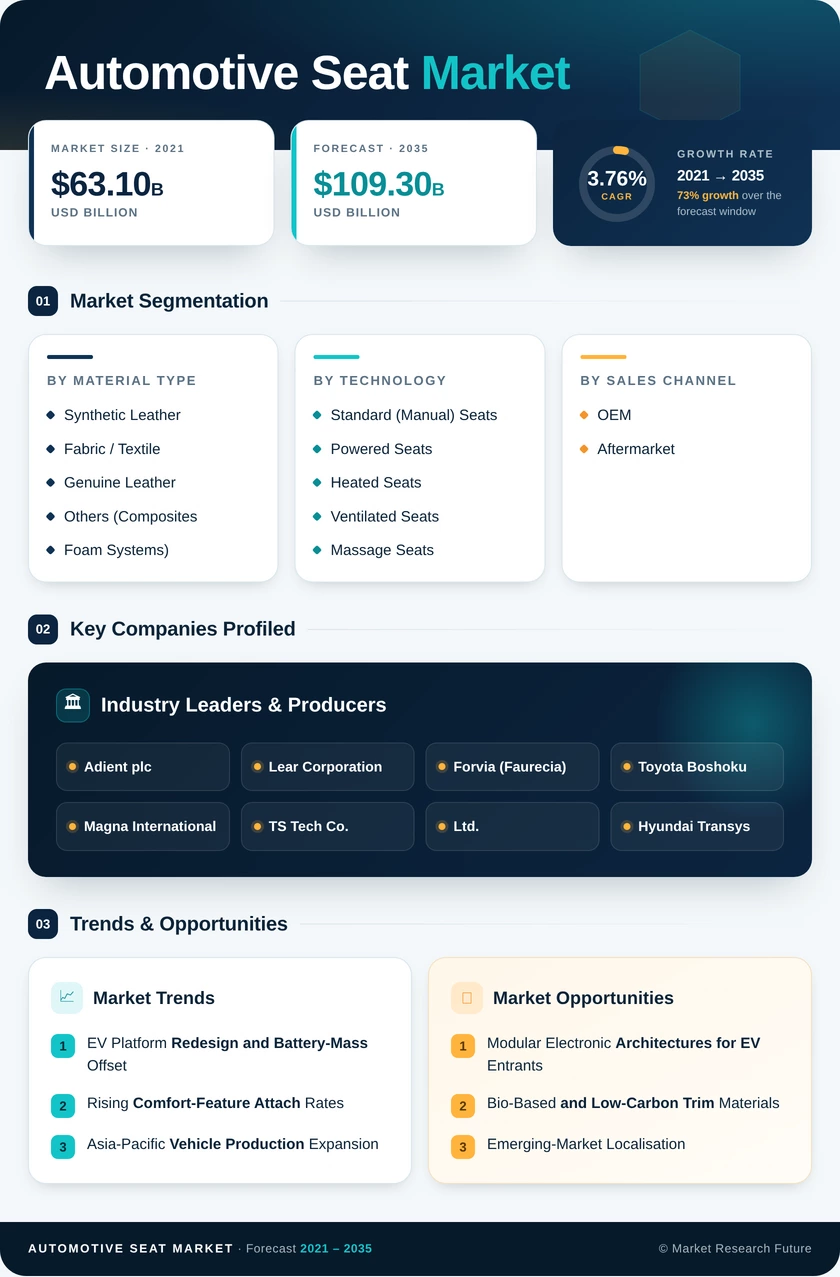
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Material Type | Synthetic Leather; Fabric / Textile; Genuine Leather; Others (Composites, Foam Systems) | Synthetic Leather | Genuine Leather |
| By Technology | Standard (Manual) Seats; Powered Seats; Heated Seats; Ventilated Seats; Massage Seats; Memory Seats | Standard (Manual) Seats | Ventilated Seats |
| By Sales Channel | OEM; Aftermarket | OEM | Aftermarket |
| By Vehicle Type | Passenger Cars; Light Commercial Vehicles; Heavy Commercial Vehicles | Passenger Cars | Heavy Commercial Vehicles |
| By Seat Type | Bench & Split-Bench; Bucket Seats; Split Seats | Bench & Split-Bench | Bucket Seats |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Material Type
| Sub-Segment | Key Trend |
| Synthetic Leather | Grain and hand-feel now approach genuine hide, closing the perception gap at mid-tier pricing |
| Fabric / Textile | Recycled-content yarns gain share as lifecycle disclosure requirements approach |
| Genuine Leather | Confined to premium and luxury trims; growth driven by SUV upgrade cycles |
| Others (Composites, Foam Systems) | Natural-fibre composites and bio-polyol foams replace conventional substrates |
Material choice increasingly serves two masters at once — appearance and compliance. Synthetic surfaces retain the volume position because they satisfy both without a cost penalty, while composite substrates carry the lightweighting agenda beneath the visible trim.
By Technology
| Sub-Segment | Key Trend |
| Standard (Manual) Seats | Volume anchor in entry trims and commercial fleets across emerging markets |
| Powered Seats | Becoming default specification at mid-tier price points in mature markets |
| Heated Seats | Efficient cabin warming preserves electric range better than cabin-air heating |
| Ventilated Seats | Fastest-growing technology as thermal comfort cascades below luxury tiers |
| Massage Seats | Luxury differentiator; expanding into long-haul commercial driver seats |
| Memory Seats | Multi-driver households and shared fleets drive personalisation demand |
Technology mix, not unit volume, drives revenue growth this decade. Comfort electronics add several hundred dollars per vehicle at manufacturer level, and attach rates are climbing faster than global vehicle production.
By Sales Channel
| Sub-Segment | Key Trend |
| OEM | Just-in-sequence delivery locks in regional supply and limits channel competition |
| Aftermarket | Ageing vehicle parc and ride-hailing fleet cycles lift replacement demand |
Channel economics diverge sharply. OEM contracts deliver scale and program visibility at thin margins, while aftermarket volumes are smaller but materially more profitable per unit.
By Vehicle Type
| Sub-Segment | Key Trend |
| Passenger Cars | Largest revenue block; widest range of comfort and material specification |
| Light Commercial Vehicles | Last-mile delivery expansion drives durable, serviceable seating demand |
| Heavy Commercial Vehicles | Air-suspended ergonomic seating supports driver retention strategies |
Commercial categories punch above their unit share on content value. Suspension seating, extended durability specifications, and long service-parts tails make them structurally attractive despite lower volumes.
By Seat Type
| Sub-Segment | Key Trend |
| Bench & Split-Bench | Sustained by full-size pickup and van platforms, especially in North America |
| Bucket Seats | Crossover and SUV mix shift lifts demand across every major region |
| Split Seats | Cargo flexibility keeps 60/40 configurations standard in compact segments |
Format demand follows body-style mix almost mechanically. As crossovers displace sedans and pickups retain their North American position, bucket and bench formats grow in parallel rather than at each other's expense.
By Region
| Sub-Segment | Key Trend |
| North America | Nearshoring under USMCA content rules; highest comfort-feature attach rates |
| Europe | Lightweighting and circularity regulation reshape material specification |
| Asia-Pacific | NEV platform volume and localisation incentives sustain leadership |
| South America | Entry-segment recovery and aftermarket formalisation |
| Middle East & Africa | Assembly localisation and climate-durable trim requirements |
Region determines both scale and technical priority. Asia-Pacific supplies the volume and increasingly the technology, while European regulation sets the material agenda that eventually propagates to other regions.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA