Automatic Mounter Wafer Equipment Market (2026 โ€“ 2035)

Automatic Mounter Wafer Equipment Market Size, Share and Research Report By Wafer Size (300 mm, 200 mm, 150 mm), By End-User (Foundries, Inter-level Dielectric Material, Memory) and By Regional (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Industry Forecast to 2035.
ID: MRFR/SEM/41129-HCR 200 Pages Nirmit Biswas, Garvit Vyas Last Updated: September 24, 2026
Automatic Mounter Wafer Equipment Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)10.8%
2025 Market SizeUSD 386.4 Million
2035 Market SizeUSD 1,077.6 Million
Key Players
Nitto Denko Corporation
LINTEC Corporation
DISCO Corporation
Takatori Corporation
Teikoku Taping System
Ultron Systems Inc.
Opportunities
  • Back-End Build-Out in India and Southeast Asia
  • Equipment Data Monetization and Service-Based Models
  • Ultra-Thin Wafer and Panel-Level Mounting

Automatic Mounter Wafer Equipment Market Summary

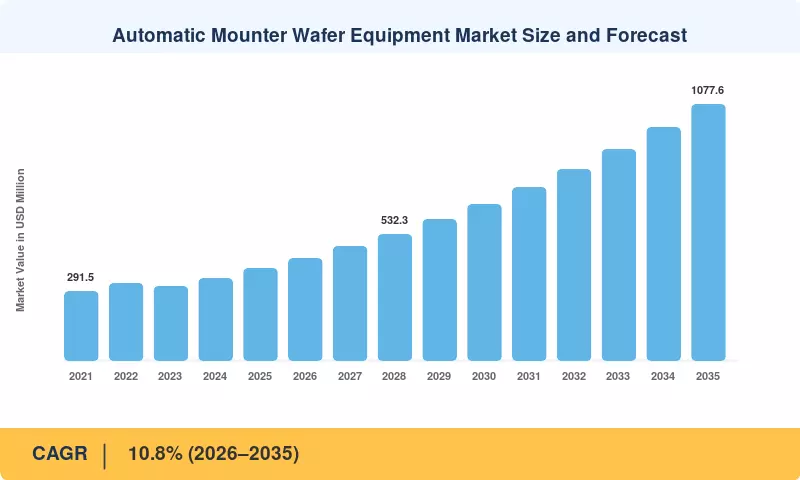
The Automatic Mounter Wafer Equipment Market was valued at USD 386.4 million in 2025 and is projected to reach USD 428.1 million in 2026. It will climb to USD 1,077.6 million by 2035, a CAGR of 10.8% over 2026โ€“2035. Two catalysts anchor that trajectory. The US CHIPS and Science Act committed USD 52.7 billion to domestic chipmaking [4], and SEMI tracks 18 new fab construction projects starting in 2025 alone [2]. Every wafer those fabs produce must be taped to a frame before dicing, so mounter demand scales directly with wafer starts.

Back-end lines are retiring semi-automatic, operator-loaded tape applicators in favor of fully automatic, cassette-to-cassette mounters with UV curing, frame ID tracking and inline inspection. Thinner wafers force the change. HBM stacks and chiplet dies now routinely fall below 50 ยตm, a thickness at which manual semiconductor wafer handling breaks yield. Chipmakers are funding the shift at scale: TSMC guided 2025 capital spending of USD 38โ€“42 billion, with a rising portion directed to advanced packaging [12].

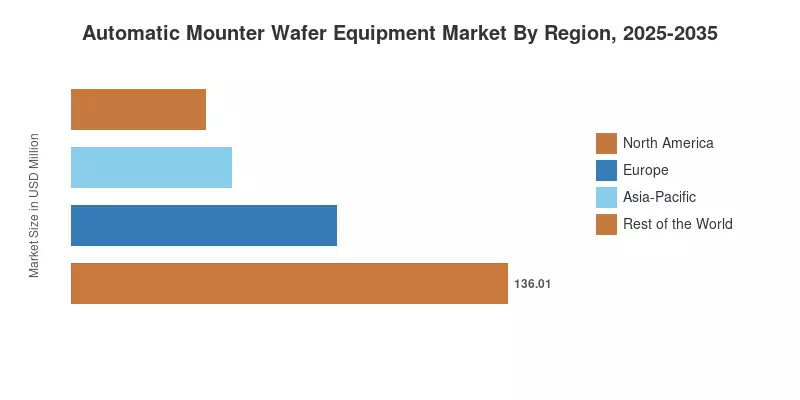
North America holds the largest position in the Automatic Mounter Wafer Equipment Market with a 35.2% share in 2025, supported by CHIPS-funded fab and packaging projects in Arizona, Texas, New York and Indiana. Asia-Pacific, a close second by value, is the fastest-growing region at a 12.9% CAGR, driven by China's Big Fund III, India's semiconductor mission and Korean HBM expansion. Europe ranks third, anchored by power semiconductor lines in Germany and Austria. On current trajectories, Asia-Pacific is positioned to overtake North America in absolute value before 2030.

Key Report Takeaways

โ€ข By Wafer Size

  • The 300 mm segment leads the Automatic Mounter Wafer Equipment Market with a 58.4% share in 2025, reflecting logic and memory volume concentrated on the largest substrates.
  • 200 mm is the fastest-growing wafer size at a 12.4% CAGR, lifted by silicon carbide and analog capacity migrating to 200 mm lines.
  • 150 mm generated USD 47.5 million in 2025, sustained by compound semiconductor, MEMS and legacy discrete production.

โ€ข By End-User

  • Foundries account for 47.6% of the Automatic Mounter Wafer Equipment Market, the largest end-user position.
  • Memory is the fastest-growing end user at an 11.9% CAGR as HBM stacking multiplies thin-wafer mounting steps.
  • Inter-level Dielectric Material applications were worth USD 59.9 million in 2025, supported by low-k film processing.

โ€ข By Region

Market Size and Forecast (2021โ€“2035)

Market Research Future built this series bottom-up from installed-base estimates of automatic mounters by wafer size, cross-checked against supplier segment revenues, SEMI equipment billings and wafer shipment data [3][24]. Historical values reflect reported shipments and average selling prices, while forecast years apply announced fab schedules and packaging investment plans to a seven-to-nine-year replacement cycle. Two years stand out in the Automatic Mounter Wafer Equipment Market record: 2021 spiked on shortage-driven capacity orders, and 2023 contracted as memory makers cut utilization.
Automatic Mounter Wafer Equipment Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
National chip programs accelerating fab construction +2.4% North America, Europe, Japan, India Medium-term
Growth in 300 mm wafer volumes +2.0% Asia-Pacific core, North America Long-term
HBM and thin-wafer memory stacking +1.7% South Korea, US, Taiwan Short-term
Advanced packaging and chiplet adoption +1.5% Taiwan, US, Japan Medium-term
Power semiconductors and 200 mm SiC transition +1.1% Europe, China, Japan Medium-term
Yield pressure and labor constraints favoring automation +0.9% Global Short-term
Expanding consumer electronics and mobile penetration +0.7% Asia-Pacific, emerging economies Long-term

ย 

National Chip Programs Accelerating Fab Construction

Government incentives have converted fab announcements into equipment orders. The CHIPS and Science Act allocated USD 39 billion to manufacturing incentives [4], the European Chips Act targets more than EUR 43 billion in public and private investment [5], and Japan had committed more than JPY 1.7 trillion to Rapidus by March 2025 [6]. Each greenfield fab and its adjacent packaging site requires multiple automatic mounters, typically ordered 12โ€“18 months before volume ramp, which pulls demand into 2026โ€“2029.

Growth in 300 mm Wafer Volumes

SEMI expects global 300 mm fab equipment spending to reach a record of about USD 400 billion across 2025โ€“2027 [10]. Larger substrates carry more dies per wafer and higher value per mounting step, so tape-frame handling for 300 mm has shifted almost entirely to automatic platforms with robotic transfer and warpage compensation. Logic nodes below 5 nm and 3D NAND beyond 200 layers both concentrate on this format, keeping it at the center of equipment procurement.

HBM and Thin-Wafer Memory Stacking

High-bandwidth memory is the sharpest near-term driver. SK hynix is investing USD 3.87 billion in an Indiana HBM packaging plant [13], and Micron secured up to USD 6.1 billion in CHIPS funding for its Idaho and New York fabs [14]. HBM dies are thinned to roughly 30โ€“50 ยตm and stacked 12 or more high. That requires stress-free mounting, precise tape tension and bubble-free lamination, which only automatic tools deliver at production yields.

Advanced Packaging and Chiplet Adoption

Chiplet architectures split one large die into several smaller ones, raising the number of dicing and mounting operations per finished device. Yole Group projects advanced packaging revenue approaching USD 80 billion by 2029 [15], and TSMC has roughly doubled CoWoS capacity year on year since 2023 [12]. OSATs and foundries building 2.5D and 3D lines now specify automatic mounters that handle glass carriers, reconstituted wafers and frame formats beyond standard 300 mm.

Power Semiconductors and the 200 mm Silicon Carbide Transition

SEMI projects 200 mm fab capacity rising 14% between 2023 and 2026 to a record 7.7 million wafers per month [11], with power and compound semiconductors leading additions. Infineon's EUR 5 billion Dresden Smart Power Fab and its Villach expansion [16] illustrate the build-out. Silicon carbide wafers are brittle and costly, so producers moving from 150 mm to 200 mm substrates are replacing older semi-automatic mounters with fully automatic units to protect yield.

Yield Pressure and Labor Constraints Favoring Automation

Back-end yield losses concentrate at handling steps, and automatic mounters cut particle contamination, wafer breakage and tape voids relative to manual lamination. Labor shortages add a second push: an SIA and study estimates that 67,000 of the 115,000 new US semiconductor jobs expected by 2030 risk going unfilled [17]. Automated tape-frame lines let fabs run with fewer operators per shift and generate traceable process data for every wafer.

Expanding Consumer Electronics and Mobile Penetration

Smartphones, wearables and PCs still absorb the largest volume of chips. Global semiconductor sales reached USD 627.6 billion in 2024 [1], and GSMA counts 5.8 billion unique mobile subscribers, heading toward 6.5 billion by 2030 [19]. Rising device content in emerging economies sustains high-volume mounting of discrete, power management and RF dies, much of it on 200 mm and 150 mm lines operated by OSATs across Southeast Asia.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High capital cost of fully automatic mounters -1.2% Emerging markets, small OSATs Short-term
Semiconductor cyclicality and memory downturns -1.0% Global Short-term
Export controls and trade restrictions -0.9% China, US, Japan Medium-term
Concentrated supply of dicing tapes and consumables -0.6% Global Medium-term
Skilled technician shortages and integration complexity -0.5% North America, Europe Long-term

ย 

High Capital Cost of Fully Automatic Mounters

A fully automatic 300 mm mounter with UV curing and inline inspection costs several times more than a semi-automatic table unit, and integration with sorters and dicing saws adds expense. For small OSATs and university labs, that price gap delays upgrades. The pressure is sharpest in emerging markets, where India's โ‚น76,000 crore incentive scheme prioritizes fabs and large ATMP sites over smaller assembly houses [7].

Semiconductor Cyclicality and Memory Downturns

Equipment orders track chipmaker capital budgets, which swing sharply. SEMI data show silicon wafer area shipments fell 14.3% in 2023 as memory makers cut utilization [24]. Back-end tools such as mounters are often the first line item deferred when inventory builds, so revenue can fall faster than wafer output in a downturn and recover later in an upturn.

Export Controls and Trade Restrictions

In December 2024, the US broadened restrictions on semiconductor manufacturing equipment and HBM shipments to China [23], after Japan added 23 equipment categories to its own control list in July 2023. Most control thresholds are higher for mounters. But compliance screening, end-user checks and client uncertainties extend sales timelines for Japanese and US vendors selling to Chinese fabs.

ย 

Concentrated Supply of Dicing Tapes and Consumables

Automatic mounters run on UV-curable and non-UV dicing tapes supplied largely by a handful of Japanese producers, led by Nitto Denko and LINTEC [20][21]. Because tape and tool are usually qualified together, any disruption in adhesive film supply can idle mounting lines. Buyers also face lock-in, as switching tape suppliers typically requires requalification lasting several months.

Skilled Technician Shortages and Integration Complexity

SECS/GEM interfaces are needed for automatic mounters to communicate with grinders, dicing saws, die sorters, and factory host systems. Greenfield sites in the US and Europe are having difficulty filling these integration and maintenance positions, and the SIA workforce analysis puts technicians at the center of the predicted 67,000-worker shortfall [17]. Longer commissioning periods delay the translation of orders into revenue.

ย 

Automatic Mounter Wafer Equipment Market Opportunities

Back-End Build-Out in India and Southeast Asia

In addition to Micronโ€™s USD 2.75 billion Sanand ATMP facility [7][25], Indiaโ€™s cabinet approved three semiconductor units, including the Tataโ€“PSMC fab in Dholera and OSAT factories in Assam and Sanand, in February 2024 [7][25]. Malaysia, Vietnam and Thailand are increasing assembly capacity as clients seek to diversify away from single-country supply. These greenfield sites will acquire complete back-end lines at a time and give suppliers a shot at locking up multi-year tool and tape agreements.

ย 

Equipment Data Monetization and Service-Based Models

Modern mounters record data for every wafer on tape tension, lamination pressure, bubble detection and frame ID. Suppliers can bundle this into subscription analytics, predictive maintenance and yield-correlation services, transferring some of the revenue from one-off tool sales to ongoing contracts. Pay-per-wafer and uptime-guaranteed leasing will further reduce the entrance barrier for smaller OSATs that are held back by capital expense.

ย 

Ultra-Thin Wafer and Panel-Level Mounting

HBM4 stacks of up to 16 dies and hybrid-bonded chiplets push wafer thickness toward 30 ยตm and below, while panel-level packaging introduces rectangular substrates exceeding 600 mm [15]. Few existing mounters handle both. Suppliers that develop low-stress lamination, carrier-bonded wafer support and large-format frames can capture premium pricing from memory makers and advanced packaging lines.

Retrofit and Upgrade Demand in 200 mm Fabs

Hundreds of 200 mm lines still run semi-automatic mounters installed a decade or more ago. SEMI's forecast of 7.7 million wafers per month of 200 mm capacity by 2026 [11] implies a large installed base in need of automation. Upgrade kits adding UV curing, auto-cassette loading and MES connectivity give suppliers a lower-cost entry into fabs that cannot justify full line replacement.

New Semiconductor Hubs in the Middle East

Saudi Arabia launched its National Semiconductor Hub in 2024, targeting 50 chip design companies by 2030, and the UAE is courting packaging investment tied to AI data centers. These programs start with design and assembly rather than front-end fabs, which places mounting and dicing tools among the first equipment purchased. Early-entry suppliers can help shape local process standards.

Automatic Mounter Wafer Equipment Market Future Outlook

Four themes will shape the Automatic Mounter Wafer Equipment Market through 2035, each changing what buyers expect a mounter to do.

AI-Driven Process Control and Lights-Out Back-End Lines

By the early 2030s, leading OSATs expect back-end lines to run with minimal operator intervention. Mounters will feed lamination data into machine-learning models that flag chipping and die-crack risk before a wafer reaches the saw. Demand for the chips these lines produce looks durable: the IEA projects data center electricity use more than doubling to about 945 TWh by 2030 [18], a proxy for sustained AI accelerator output.

Heterogeneous Integration Redefining Tool Specifications

Hybrid bonding, glass-core substrates and wafer-to-wafer stacking will change what a mounter must handle. Tools will need to process bonded wafer stacks, temporary carriers and non-round panels, and to coordinate with laser and plasma singulation as wafer dicing technology moves beyond blade saws. SEMI's projection of record 300 mm spending through 2027 [10] gives suppliers the order flow to fund this development.

Supply Chain Regionalization

Chipmakers are building parallel capacity in the US, Europe, Japan and India to reduce concentration risk. Global equipment sales reached USD 117.1 billion in 2024 [3], and a growing portion now flows to new geographies. That shift favors suppliers with local service networks and multi-region manufacturing, and it opens room for Korean, Chinese and Indian equipment makers in their home markets.

Sustainability and Consumable Reduction

Customer carbon targets are extending into supplier scorecards, and back-end consumables are an easy target. Dicing tape is single-use, and mercury UV lamps draw continuous power. Tape producers already publish emission and waste reduction goals [20]. Mounters that minimize tape overhang, support frame reuse and switch to LED UV curing will gain an edge in procurement decisions.

Regional Market Share Analysis

Region Disclosed Metric Primary Investment Themes
North America 35.2% share CHIPS-funded fabs, HBM and advanced packaging plants
Europe USD 82.7 Million Power semiconductors, SiC, Chips Act pilot lines
Asia-Pacific 12.9% CAGR Mature-node localization, HBM, OSAT expansion
Rest of the World 10.8% share Specialty fabs, emerging assembly hubs
Total USD 386.4 Million 2025 global market value

Regional demand in the Automatic Mounter Wafer Equipment Market follows where wafers are thinned, diced and packaged. North America leads on the strength of subsidized fab and packaging construction, while Asia-Pacific grows fastest as China, South Korea, India and Taiwan expand back-end capacity.

ย 

North America

Country Disclosed Metric Key Driver
US 84.1% share of region CHIPS-funded fabs and HBM packaging
Canada USD 12.4 Million Photonics and MEMS foundries
Mexico 11.6% CAGR Nearshored automotive chip assembly

CHIPS Act awards to Intel, TSMC Arizona, Samsung Taylor, Micron and Amkor's USD 2 billion Peoria packaging campus [4] are converting into tool orders from 2025 onward. TSMC's March 2025 pledge of an additional USD 100 billion, including two advanced packaging facilities [12], adds mounter demand tied to CoWoS-class production. The US accounts for most regional purchasing, while Mexico is emerging as a back-end assembly location for automotive and industrial chips.

ย 

Europe

Country Disclosed Metric Key Driver
Germany 31.4% share of region Dresden power and logic fab cluster
UK USD 8.9 Million Compound semiconductor clusters in Wales
France 9.4% CAGR FD-SOI and power device capacity
Italy 9.6% share of region SiC and power discrete production
Spain USD 3.1 Million PERTE Chip design and packaging program
Nordic Countries 10.1% CAGR SiC substrates and MEMS
Russia 3.1% share of region Domestic mature-node substitution
Rest of Europe 20.8% share of region Austria, Netherlands and Ireland fab activity

German sites anchor European demand, led by Infineon's Dresden expansion [16], Bosch's Dresden 300 mm fab and GlobalFoundries' Dresden operations. The European Chips Act [5] supports pilot lines and first-of-a-kind facilities, and ESMC, the TSMC, Bosch, Infineon and NXP joint venture, began construction in Dresden in August 2024. Power device production in Austria, Italy and the Nordic countries keeps 200 mm and 150 mm mounter demand steady.

ย 

Asia-Pacific

Country Disclosed Metric Key Driver
China 38.7% share of region Big Fund III and mature-node localization
Japan USD 27.1 Million Rapidus and TSMC Kumamoto fabs
South Korea 13.4% CAGR HBM stacking at memory majors
India 17.8% CAGR Greenfield fabs and ATMP sites
ASEAN USD 9.6 Million OSAT expansion in Malaysia and Vietnam
Rest of Asia-Pacific 21.3% share of region Taiwan advanced packaging capacity

China is the largest national buyer, backed by the RMB 344 billion Big Fund III launched in May 2024 [9] and aggressive localization of mature-node and 200 mm capacity. South Korea's KRW 26 trillion support package [8] and the SK hynix HBM ramp lift memory-driven demand, while Rapidus and TSMC Kumamoto [6] revive Japanese purchasing. Taiwan, reported under Rest of Asia-Pacific, remains the global center of advanced packaging.

ย 

Rest of the World

Country Disclosed Metric Key Driver
Brazil 13.9% share of region PADIS-supported chip assembly
Argentina USD 0.9 Million Electronics assembly in Tierra del Fuego
Rest of South America 7.2% CAGR Small-scale discrete assembly
Saudi Arabia 14.6% CAGR National Semiconductor Hub
UAE USD 2.2 Million AI-linked packaging investment
South Africa 3.1% share of region University and specialty device labs
Egypt 8.3% CAGR Chip design and electronics incentives
Rest of MEA 65.7% share of region Israeli logic and specialty fabs

Demand here is small but concentrated. Israel, reported within Rest of MEA, hosts Intel's Kiryat Gat fab and Tower Semiconductor's Migdal HaEmek lines, which account for most regional mounter purchases. Saudi Arabia and the UAE represent the fastest-growing pockets as national semiconductor programs take shape. In contrast, Brazil's PADIS incentive program supports a modest back-end assembly base serving domestic electronics.

ย 

Automatic Mounter Wafer Equipment Market By Region, 2025-2035

Automatic Mounter Wafer Equipment Market Segmentation

By Wafer Size

Within the Automatic Mounter Wafer Equipment Market, 300 mm holds a 58.4% share because advanced logic, DRAM and 3D NAND run almost exclusively on this format, and each 300 mm tool commands a higher selling price. 200 mm is the fastest-growing size at a 12.4% CAGR as silicon carbide, analog and MEMS makers expand 200 mm capacity in China and Europe. 150 mm contributes USD 47.5 million, sustained by compound semiconductor and legacy discrete lines, though its growth trails both larger formats.

Segment Disclosed Metric Primary Demand Driver
300 mm 58.4% share Advanced logic, DRAM, 3D NAND and HBM
200 mm 12.4% CAGR SiC power devices, analog and MEMS
150 mm USD 47.5 Million Compound semiconductors, LEDs and discretes

ย 

By End-User

Foundries represent 47.6% of the Automatic Mounter Wafer Equipment Market, led by TSMC, Samsung Foundry, GlobalFoundries and SMIC, whose integrated packaging services increasingly perform mounting in-house. Memory is the fastest-growing end user at an 11.9% CAGR, driven by HBM stacking at SK hynix, Samsung and Micron. Inter-level Dielectric Material applications, valued at USD 59.9 million, cover wafers carrying low-k and specialty dielectric films, where fragile layers demand low-stress lamination.

Segment Disclosed Metric Primary Demand Driver
Foundries 47.6% share Logic volume and in-house advanced packaging
Inter-level Dielectric Material USD 59.9 Million Low-k films requiring gentle lamination
Memory 11.9% CAGR HBM stacking and thin DRAM wafers

ย 

Competitive Benchmarking

The Automatic Mounter Wafer Equipment Market is concentrated at the top. The five largest suppliers hold an estimated 57โ€“63% of revenue, and the estimated HHI sits around 950โ€“1,100, with a long tail of regional specialists below the leaders. Japanese vendors dominate the premium segment because they pair mounters with proprietary dicing tapes and integrate them into grinding and dicing lines [20][21][22]. Smaller US and European firms compete on price, customization and service for R&D fabs and specialty producers.

Company Est. Revenue Share Range Key Offerings for Automatic Mounter Wafer Equipment Market Strategic Positioning
Nitto Denko Corporation ~17โ€“21% Fully automatic wafer mounters and laminators paired with UV and non-UV dicing tapes Tool-plus-tape bundling across Japan, Taiwan and Korea
LINTEC Corporation ~14โ€“18% RAD-series mounters, UV curing units and Adwill tapes Integrated tape and equipment for thin-wafer processes
DISCO Corporation ~11โ€“14% Mounters integrated with dicing saws, grinders and DBG lines Process-level integration across the back end
Takatori Corporation ~7โ€“10% Automatic mounters, tape laminators and tape removers Tape-handling specialist for thin wafers
Teikoku Taping System ~4โ€“6% Wafer mounters, laminators and peelers Customized tools for Japanese fabs
Ultron Systems Inc. ~4โ€“6% Semi-automatic and automatic mounters, UV curing systems Cost-competitive supplier to US fabs and labs
Advanced Dicing Technologies ~3โ€“5% Mounters, dicing saws and blades Strong in LED, discrete and specialty devices
Powatec GmbH ~2โ€“4% Tape mounters, frame cleaners and UV curers European supplier to power and MEMS fabs
Semiconductor Equipment Corporation ~2โ€“4% Wafer tape mounters and die ejectors Flexible, lower-cost US platforms
Syagrus Systems ~1โ€“3% Automatic tape mounters and UV curing systems Niche US supplier for R&D and pilot lines

ย 

Recent News & Developments

  • Micron Technology (June 2023): Announced its Sanand, Gujarat ATMP facility with total investment of up to USD 2.75 billion, creating India's first large-scale memory back-end site and a new source of mounter demand. [7]
  • India Cabinet (February 2024): Approved the Tataโ€“PSMC Dholera fab and two OSAT units in Assam and Sanand, adding greenfield capacity that will need complete mounting and dicing lines. [25]
  • SK hynix (April 2024): Selected West Lafayette, Indiana, for a USD 3.87 billion HBM advanced packaging plant targeting production in 2028, anchoring US thin-wafer mounting demand. [13]
  • China Integrated Circuit Industry Investment Fund (May 2024): Launched Phase III with registered capital of RMB 344 billion, supporting domestic equipment and mature-node capacity. [9]
  • US Department of Commerce (December 2024): Finalized a CHIPS award of up to USD 6.1 billion to Micron for memory fabs in Idaho and New York. [14]
  • US Bureau of Industry and Security (December 2024): Expanded controls on manufacturing equipment and HBM exports to China and added 140 entities to the Entity List, tightening supplier compliance requirements. [23]
  • TSMC (March 2025): Announced an additional USD 100 billion US investment, including two advanced packaging facilities in Arizona. [12]
  • Japan METI (March 2025): Approved up to JPY 802.5 billion in additional Rapidus support, lifting cumulative commitments above JPY 1.7 trillion. [6]

Automatic Mounter Wafer Equipment Market Report Scope

Parameter Details
Market Scope Semi-automatic-to-fully-automatic and inline wafer mounters, including integrated UV curing and frame handling modules; excludes standalone dicing tapes and dicing saws
Study Period 2021โ€“2035 (Historical: 2021โ€“2024; Base Year: 2025; Forecast: 2026โ€“2035)
CAGR 10.8% (2026โ€“2035)
Market Size checkpoints USD 386.4 Million (2025); USD 428.1 Million (2026); USD 657.0 Million (2030); USD 1,077.6 Million (2035)
Fastest Growing Segments 200 mm (By Wafer Size); Memory (By End-User); Asia-Pacific (By Region)
Companies Profiled Nitto Denko, LINTEC, DISCO, Takatori, Teikoku Taping System, Ultron Systems, Advanced Dicing Technologies, Powatec, Semiconductor Equipment Corporation, Syagrus Systems
Valuation Currency USD Million

FAQs

How do buyers justify replacing semi-automatic mounters with fully automatic tools?
Payback usually comes from yield rather than labor savings. Automatic lamination sharply reduces tape voids and edge chipping on wafers thinner than 100 ยตm, where one broken 300 mm wafer can cost thousands of dollars [17].
Which tape choice matters most for buyers in the Automatic Mounter Wafer Equipment Market?
UV-curable tape suits thin, small dies because adhesion drops after curing, easing pick-up. Non-UV tape costs less and fits thicker discrete wafers. Confirm the mounter's UV module matches the tape supplier's curing specification [20].
How does dicing-before-grinding change mounter requirements?
Wafers are half-cut first, then thinned until dies separate on backgrinding tape. The mounter must transfer that pre-singulated wafer to a dicing frame without shifting dies, requiring inline tape peeling and precise tension control [22].
Are refurbished tools viable in the Automatic Mounter Wafer Equipment Market?
Yes, for 150 mm and 200 mm lines. Refurbished units often sell at 40โ€“60% of new-tool prices and suit mature-node, discrete and MEMS production. HBM and chiplet work generally requires current-generation thin-wafer platforms.
What lead times should procurement teams plan for?
Standard automatic mounters typically ship within four to six months, while customized 300 mm systems with inline inspection can take eight months or longer. Ordering alongside grinders and dicing saws keeps qualification schedules aligned.
How do export controls affect Automatic Mounter Wafer Equipment Market suppliers selling to China?
Most mounters fall outside controlled equipment lists, so direct licensing is rarely required. The practical impact comes from end-user screening, because shipments to Entity List companies still need US authorization [23].
Which factory integration standards should a new mounter support?
Specify SECS/GEM and GEM300 for host communication, plus SEMI E84 for automated cassette handoff. These standards let the tool report wafer IDs and process data to the MES, enabling traceability from mounting through die sort.
Author
Author Author Profile Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author Co-Author Profile Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.