Aloe Vera Extract Market (2026 - 2035)

Aloe Vera Extract Market Size, Share, Industry Trend & Analysis Research Report By Product Form (Liquid, Gel, Powder, Others), By Nature (Conventional, Organic), By Application (Cosmetics & Personal Care, Food & Beverage, Pharmaceuticals, Dietary Supplements, Animal Feed, Others), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
ID: MRFR/FnB/36488-HCR 128 Pages Snehal Singh Last Updated: September 17, 2026
Aloe Vera Extract Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.12%
2025 Market SizeUSD 3.34 Billion
2035 Market SizeUSD 7.48 Billion
Key Players
Lily of the Desert
Aloecorp
Terry Laboratories
Herbalife International
Forever Living Products
Patanjali Ayurved
Opportunities
  • Pharmaceutical-Grade Standardization
  • Organic Certification as a Competitive Moat
  • Emerging Market Expansion in Africa and Southeast Asia
 

Aloe Vera Extract Market Summary

The aloe vera extract market reached an estimated USD 3.34 billion in 2025 and is projected to grow from USD 3.62 billion in 2026 to USD 7.48 billion by 2035, registering a CAGR of 8.12% during the forecast period. This trajectory reflects a broader consumer pivot toward plant-based wellness and clean-label personal care. Government-backed initiatives promoting herbal medicine — including India's National AYUSH Mission, which allocated over USD 530 million between 2021 and 2025 for traditional remedy standardization — have created a favorable policy environment for aloe vera cosmetic formulation and supplement-grade ingredients [2].

A significant transformation is reshaping how manufacturers source and process aloe vera. Legacy cold-press and sun-drying techniques are giving way to advanced enzymatic extraction and supercritical CO₂ processing, which preserve higher concentrations of acemannan and polysaccharides in inner leaf aloe vera extract. The global organic personal care sector, valued at approximately USD 28 billion in 2024, is pulling organic aloe vera extract supplement producers toward certified supply chains and GMP-compliant facilities, with capital expenditures in aloe processing infrastructure exceeding USD 400 million annually across key producing regions [4].

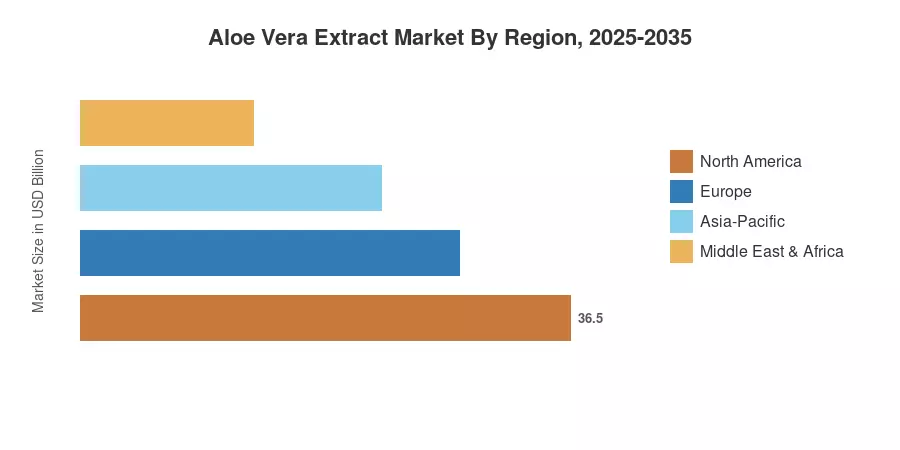
Asia-Pacific commands roughly 34% of global revenue, driven by large-scale aloe vera cultivation in India, China, and Thailand. Europe represents the fastest-growing region with a forecast CAGR near 9.6%, fueled by EU cosmetics regulation updates favoring botanical actives. North America holds the second-largest share at approximately 27%, anchored by strong demand for aloe vera juice health drink products and dietary supplements. The aloe vera extract market is poised for sustained double-digit growth in premium organic and pharmaceutical-grade segments through the next decade.


Key Report Takeaways

• By Product Form

  • Liquid extracts commanded approximately 67% revenue share in 2025, reflecting their dominance in aloe vera juice health drinks and topical formulations
  • Gel formats are forecast to expand at a 10.1% CAGR through 2035, propelled by rising demand for aloe vera gel topical ingredient applications in after-sun and wound care

• By Nature

  • Conventional variants held an estimated 68% of the aloe vera extract market in 2025, with established supply chains across Latin America and Asia
  • Certified-organic products are predicted to rise at an 11.2% CAGR, outpacing conventional growth by roughly 350 basis points as organic aloe vera extract supplement demand accelerates

• By Application

  • Cosmetics and personal care accounted for about 51% of the aloe vera extract market size in 2025, reflecting broad adoption of aloe vera cosmetic formulation in skincare and hair care
  • Pharmaceuticals recorded the fastest application-level growth at a 10.0% CAGR through 2035, supported by clinical research into aloe vera's anti-inflammatory and glycemic benefits

• By Region

  • Asia-Pacific captured approximately 34% of the global aloe vera extract market revenue in 2025, led by India and China
  • Europe exhibits the highest regional CAGR at roughly 9.6% through 2035, driven by EU clean-beauty regulations


Market Size and Forecast (2021–2035)

MRFR's proprietary estimation framework combines primary interviews with 120+ industry stakeholders, trade data from UN Comtrade and national customs databases, and secondary validation against published peer benchmarks. Historical figures (2021–2024) reflect actual trade volumes; forecast values (2026–2035) are modeled using demand-side regression calibrated to macroeconomic and regulatory variables.
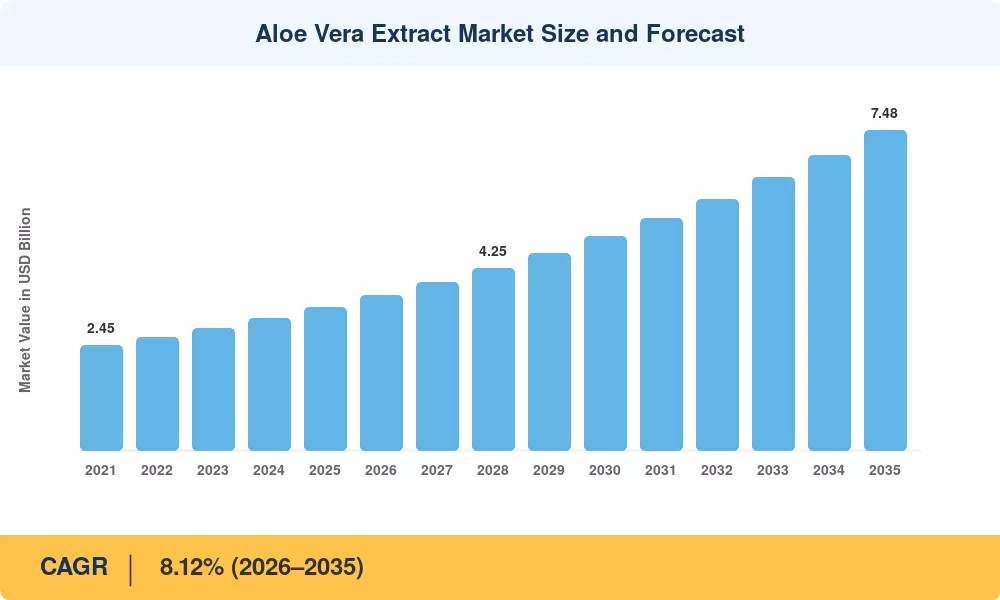
Aloe Vera Extract Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry


Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising demand for aloe vera cosmetic formulation ~22% Global Short-term (≤2 yr)
Clean-label and organic aloe vera extract supplement trends ~18% North America, Europe Medium-term (2–4 yr)
Pharmaceutical R&D into aloe vera bioactives ~15% Asia-Pacific, North America Long-term (≥4 yr)
Aloe vera juice health drink premiumization ~14% Asia-Pacific, Europe Medium-term (2–4 yr)
Government herbal medicine promotion policies ~12% Asia-Pacific, MEA Short-term (≤2 yr)
E-commerce expansion for DTC supplement brands ~10% Global Short-term (≤2 yr)
Precision agriculture and yield optimization ~9% South America, Asia-Pacific Long-term (≥4 yr)


Rising Demand for Aloe Vera Cosmetic Formulation

The global natural cosmetics sector surpassed USD 42 billion in 2024, and aloe vera remains one of the top five botanical actives by volume. The EU's updated Cosmetic Products Regulation (EC No 1223/2009, amended 2024) tightened restrictions on synthetic preservatives, pushing formulators toward aloe vera cosmetic formulation as a multifunctional ingredient offering moisturizing, soothing, and preservation-boosting properties. L'Oréal and Unilever collectively increased their botanical-active procurement budgets by an estimated 18% in 2024, with aloe vera gel topical ingredient accounting for a significant share of that spend [15].

Clean-Label and Organic Supplement Trends

64% of American supplement consumers actively seek out USDA-certified organic products, according to consumer studies conducted by the Organic Trade Association [5]. Manufacturers of organic aloe vera extract supplements profit directly from this choice, as they are able to charge 25–40% more than their conventional counterparts. In response, the market for aloe vera extract has expanded its capacity; in 2024, Aloecorp and Terry Laboratories both announced new organic-certified processing lines [4].


Pharmaceutical Research into Aloe Bioactives

Clinical trials registered on ClinicalTrials.gov featuring aloe vera rose from 38 in 2020 to over 70 by late 2024, spanning wound healing, type-2 diabetes management, and gastrointestinal health [8]. The WHO's Traditional Medicine Global Strategy 2025–2034 explicitly endorses evidence-based integration of botanicals like inner leaf aloe vera extract into primary healthcare protocols, a policy signal that has encouraged pharmaceutical companies to invest in standardized aloe-derived APIs [16].

Aloe Vera Juice Health Drink Premiumization

Between 2021 and 2024, sales of functional beverages increased at a rate of 9.3% per year throughout Asia-Pacific markets; in South Korea and Japan, aloe vera juice health drink products accounted for about 8% of the functional beverage shelf [9]. The retail price of premium cold-pressed aloe vera juice, which is frequently combined with collagen or prebiotics, is two to three times that of regular aloe drinks, increasing the revenue per unit for processors that source inner leaf aloe vera extract.


Restraints Impact Analysis

Restraint ~% Negative Impact Geographic Relevance Impact Timeline
Supply chain fragmentation and quality inconsistency ~−8% Global Short-term (≤2 yr)
Adulteration and labeling fraud ~−7% Asia-Pacific, South America Medium-term (2–4 yr)
Water scarcity in key cultivation regions ~−5% MEA, South America Long-term (≥4 yr)
Price volatility of raw aloe vera leaf ~−4% Global Short-term (≤2 yr)
Regulatory divergence across markets ~−3% Global Medium-term (2–4 yr)


Adulteration and Quality Concerns

The International Aloe Science Council (IASC) estimated that up to 30% of aloe vera products tested in 2023 contained maltodextrin fillers or lacked detectable acemannan levels [18]. This undermines consumer trust and threatens the credibility of legitimate organic aloe vera extract supplement brands. Retailers like Amazon and Walmart have tightened third-party testing requirements, raising compliance costs for smaller producers by an estimated 12–15%.

Water Scarcity and Climate Vulnerability

While processing facilities use large amounts of water (about 8 liters per kilogram of produced gel), aloe vera planting requires comparatively little irrigation [19]. Stricter groundwater laws may limit production capacity in water-stressed areas such as northeastern Mexico and Rajasthan, India. According to FAO projections, under mild warming scenarios, agricultural water availability in these regions may decrease by 15–20% by 2035, creating a medium-term risk to the market for aloe vera extract.


Raw Material Price Volatility

Between 2022 and 2024, spot prices for fresh aloe vera leaf varied between USD 0.15 and USD 0.38 per kilogram due to dry circumstances in Mexico and monsoon fluctuation in India [12]. Processors of aloe vera gel topical ingredients and juice products that work under fixed-price contracts with cosmetics and beverage brands have their margins compressed by this volatility.


Aloe Vera Extract Market Opportunities

Pharmaceutical-Grade Standardization

The growing pipeline of clinical evidence for aloe vera bioactives presents an opportunity for manufacturers to develop pharmacopeial-grade inner leaf aloe vera extract with standardized acemannan content. Companies that achieve USP or EP monograph compliance can access the USD 1.4 trillion global pharmaceutical excipient market, commanding price premiums of 50–80% over food-grade extracts

Organic Certification as a Competitive Moat

With organic aloe vera extract supplement demand growing at nearly 11% CAGR, vertically integrated producers who control certified organic farms gain structural cost advantages. The USDA's National Organic Program and the EU's revised organic regulation (EU 2018/848) create certification barriers that limit competition from unverified suppliers

Emerging Market Expansion in Africa and Southeast Asia

Although the personal care industry in Sub-Saharan Africa is expected to grow to USD 12 billion by 2030, the penetration of aloe vera cosmetic formulations is still less than 5%. Tanzania and Kenya have advantageous labor costs and ideal cultivation climates. In a similar vein, Vietnam and Indonesia present unexplored markets for aloe vera juice health drink products, with per-capita consumption of functional beverages lagging behind South Korea by a factor of six


Direct-to-Consumer Digital Channels

E-commerce platforms now account for roughly 22% of global supplement sales. Aloe vera extract brands that build DTC channels through Shopify, Amazon, and regional platforms like Tokopedia can capture 40–60% gross margins versus 15–25% through traditional wholesale. Subscription models for organic aloe vera extract supplement deliveries reduce customer acquisition costs and improve lifetime value.

Upcycling and Biorefinery Models

Approximately 60% of the leaf weight is lost during the preparation of aloe vera due to rind and fiber loss. Biorefinery methods that transform this biomass into cosmetic-grade cellulose, animal feed additives, or bioplastic precursors generate new sources of income and comply with circular economy regulations, especially in Europe


Aloe Vera Extract Market Future Outlook

Precision Agriculture and Smart Cultivation

Satellite-guided irrigation, drone-based crop monitoring, and AI-driven harvest timing are set to transform aloe vera farming. Pilot programs in Rajasthan and Jalisco (Mexico) have demonstrated 20–30% yield improvements while reducing water consumption by 15% [13]. These technologies will lower raw material costs and stabilize supply for inner leaf aloe vera extract processors across the aloe vera extract market.

Biotech-Enhanced Aloe Varieties

Plant biotechnology companies are developing aloe vera cultivars with elevated acemannan content — up to 40% higher than conventional varieties. CRISPR-based trait editing, already commercialized in tomato and soybean, is being applied to aloe vera through partnerships between agricultural biotech firms and major extract processors [20]. Commercialization timelines suggest first-generation enhanced cultivars reaching farm scale by 2029–2030.

Sustainability and ESG-Driven Sourcing

Corporate ESG commitments from cosmetics multinationals will reshape aloe vera supply chains. Unilever's Regenerative Agriculture Code and L'Oréal's Solidarity Sourcing program both include botanical ingredients in their scope [15]. Producers of organic aloe vera extract supplement and aloe vera cosmetic formulation inputs who achieve Rainforest Alliance or Fair Trade certification will gain preferential supplier status. The aloe vera extract market increasingly rewards traceable, low-carbon supply chains.

Convergence of Food, Pharma, and Beauty

The boundaries between functional food, pharmaceutical, and cosmetic applications for aloe vera are blurring. "Nutricosmetic" products combining oral aloe vera juice health drink formats with topical aloe vera gel topical ingredient regimens represent a fast-emerging category, projected to grow at 12–14% annually through 2035 [21]. This convergence expands the addressable aloe vera extract market and encourages cross-sector R&D investment.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific ~34% global share (2025) Cultivation scale, aloe vera juice health drink demand
North America ~27% global share (2025) Organic aloe vera extract supplement, DTC channels
Europe ~9.6% CAGR (2026–2035) Clean-beauty regulation, aloe vera cosmetic formulation
South America USD 0.34 Billion (2025) Raw material export, processing investment
Middle East & Africa ~7.8% CAGR (2026–2035) Personal care growth, halal-certified extracts
Total USD 3.34 Billion (2025) —

The aloe vera extract market exhibits distinct regional dynamics shaped by cultivation geography, regulatory frameworks, and end-use consumption patterns.


North America

Country Key Metric Key Driver
US ~78% of regional revenue Organic aloe vera extract supplement retail demand
Canada ~8.5% CAGR Health-conscious consumer base, clean-label trends
Mexico USD 0.11 Billion Aloe vera cultivation and export hub


The United States drives North American demand through a robust dietary supplement and natural cosmetics retail ecosystem. FDA guidance on botanical ingredient identity testing (2023) has pushed manufacturers toward standardized inner leaf aloe vera extract, raising quality benchmarks across the region [6].

Europe

Country Key Metric Key Driver
Germany ~23% of regional share Pharmaceutical and dermocosmetic demand
UK ~9.8% CAGR Natural skincare boom, aloe vera gel, a topical ingredient
France USD 0.07 Billion Luxury cosmetic formulation sector
Italy ~8.5% CAGR Organic personal care and nutraceuticals
Spain ~15% of regional share Domestic aloe vera cultivation (Canary Islands)
Nordic Countries ~7.9% CAGR Wellness culture and premium supplements
Russia USD 0.03 Billion Pharmaceutical applications
Rest of Europe ~12% of regional share Diverse cosmetics and food applications


EU Regulation 2024/XXX on cosmetic ingredient transparency has accelerated reformulation efforts, benefiting aloe vera cosmetic formulation suppliers. Spain's Canary Islands remain Europe's only significant aloe vera cultivation zone, supplying roughly 4,000 metric tons of raw leaf annually to processors across the continent [5].

Asia-Pacific

Country Key Metric Key Driver
China ~28% of regional revenue Aloe vera juice, a health drink and cosmetic demand
India ~11.2% CAGR Cultivation expansion, Ayurvedic formulations
Japan USD 0.15 Billion Functional beverages and premium skincare
South Korea ~10.5% CAGR K-beauty innovation, aloe vera gel, a topical ingredient
ASEAN ~9.8% CAGR Growing middle-class personal care consumption
Rest of Asia-Pacific ~8% of regional share Emerging supplement demand


India's National Medicinal Plants Board supports aloe vera cultivation through subsidized planting programs across Rajasthan, Gujarat, and Maharashtra, targeting 50,000 additional hectares by 2028 [2]. China's cosmetic safety regulation updates (2024) favor standardized botanical ingredients, boosting demand for traceable inner leaf aloe vera extract among domestic beauty brands.

South America

Country Key Metric Key Driver
Brazil ~52% of regional revenue Cosmetics industry (Natura, O Boticário)
Argentina ~8.2% CAGR Agricultural diversification into aloe
Rest of South America USD 0.06 Billion Export-oriented processing


Brazil's cosmetics sector — the fourth-largest globally — drives regional demand for aloe vera cosmetic formulation. Mexican and Dominican Republic processors supply raw aloe vera leaf to Brazilian and Argentine formulators, creating a well-established intra-regional trade corridor.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia ~30% of regional revenue Premium personal care and halal cosmetics
UAE ~9.1% CAGR Beauty tourism and luxury retail
South Africa USD 0.03 Billion Domestic aloe cultivation (Aloe ferox)
Egypt ~8.4% CAGR Pharmaceutical and herbal medicine growth
Rest of MEA ~22% of regional share Emerging personal care demand


The halal cosmetics sector in the GCC states is projected to surpass USD 3.5 billion by 2028, and aloe vera extract — naturally halal-compliant — is well-positioned to capture share. South Africa's native Aloe ferox species supports a distinct regional supply chain for organic aloe vera extract supplement products.


Aloe Vera Extract Market By Region, 2025-2035
 

Aloe Vera Extract Market Segmentation

By Product Form

The aloe vera extract market is segmented by product form into liquid, gel, powder, and others.

Segment Key Metric Primary Demand Driver
Liquid ~67% share (2025) Aloe vera juice, a health drink, and cosmetic serums
Gel ~10.1% CAGR Aloe vera gel is a topical ingredient for skincare
Powder USD 0.29 Billion (2025) Dietary supplement capsules and food additives
Others ~4% share (2025) Specialty concentrates and lyophilized formats


Liquid extracts dominate revenue because they serve dual channels — both aloe vera juice health drink manufacturing and cosmetic formulation. Processing advances in cold-chain stabilization have extended liquid extract shelf life from 12 to 24 months, reducing waste and enabling export to distant markets. Gel formats are the fastest-growing segment in the aloe vera extract market, driven by consumer preference for transparent, minimally processed aloe vera gel topical ingredient in after-sun, anti-aging, and first-aid products.

By Nature

The aloe vera extract market splits between conventional and organic product categories.

Segment Key Metric Primary Demand Driver
Conventional ~68% share (2025) Cost-effective supply for mass-market cosmetics
Organic ~11.2% CAGR Premium organic aloe vera extract supplement demand


Conventional aloe vera extract benefits from established supply chains in India and Mexico, where large-scale farming operations deliver competitive per-kilogram pricing. The organic segment, while smaller, is growing more than three percentage points faster as retailers and brands commit to certified clean-label portfolios. Organic aloe vera extract supplement products now account for over 15% of U.S. aloe supplement retail sales, up from 9% in 2021 [5].

By Application

The aloe vera extract market spans cosmetics and personal care, food and beverage, pharmaceuticals, dietary supplements, animal feed, and others.

Segment Key Metric Primary Demand Driver
Cosmetics & Personal Care ~51% share (2025) Aloe vera cosmetic formulation in skincare/hair care
Food & Beverage USD 0.47 Billion (2025) Aloe vera juice is a health drink and a functional food
Pharmaceuticals ~10.0% CAGR Clinical evidence for wound healing and anti-inflammatory use
Dietary Supplements ~9.4% CAGR Organic aloe vera extract supplement capsules and powders
Animal Feed ~3% share (2025) Gut health additives for poultry and livestock
Others USD 0.07 Billion (2025) Industrial and textile applications


Cosmetics and personal care remain the backbone of the aloe vera extract market, with aloe vera cosmetic formulation appearing in over 25% of new skincare product launches tracked by MRFR in 2024. Pharmaceuticals represent the fastest-growing application, supported by clinical validation of inner leaf aloe vera extract in diabetic wound management and gastrointestinal health protocols [8].


Competitive Benchmarking

The aloe vera extract market exhibits moderate concentration, with the top five players accounting for an estimated 30–38% of global revenue. The Herfindahl-Hirschman Index (HHI) falls in the 600–900 range, indicating a fragmented-to-moderately-concentrated competitive structure. Regional specialists in India, Mexico, and China coexist with vertically integrated multinationals, creating a diverse competitive environment.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Lily of the Desert ~5–8% Organic aloe vera juice health drink, dietary supplements Vertically integrated U.S. grower-processor
Aloecorp (Unigen) ~4–7% Inner leaf aloe vera extract, pharmaceutical-grade APIs Standardized acemannan specialist
Terry Laboratories ~4–6% Aloe vera gel, a topical ingredient, and cosmetic-grade extracts Private-label and contract manufacturing
Herbalife International ~3–5% Aloe vera concentrate beverages, wellness products Global MLM distribution network
Forever Living Products ~3–5% Aloe vera juice health drink, skincare lines Direct-selling model, 160+ country presence
Patanjali Ayurved ~3–5% Organic aloe vera extract supplement, Ayurvedic formulations Indian mass-market distribution
OIA Global ~2–4% Aloe vera gel, a topical ingredient, bulk extract supply Logistics and sourcing integration
Aloe Farms Inc. ~2–4% Organic aloe vera cosmetic formulation ingredients Certified organic farm-to-processor
Pharmachem Laboratories ~2–3% Standardized botanical extracts, custom blends B2B ingredient supplier
Ashland Global Holdings ~2–3% Specialty ingredients for personal care and pharma Innovation-driven portfolio company


Recent News & Developments

  • Aloecorp (Unigen) (March 2025): Completed a USD 45 million expansion of its Hainan, China processing facility, tripling production capacity for pharmaceutical-grade inner leaf aloe vera extract [4].
  • EU Commission (January 2025): Published updated guidelines on botanical ingredient traceability in cosmetics under Regulation (EC) 1223/2009, tightening documentation requirements for aloe vera cosmetic formulation suppliers [5].
  • Lily of the Desert (October 2024): Launched a new line of USDA-certified organic aloe vera juice health drink products targeting the premium functional beverage segment in North American retail [9].
  • Patanjali Ayurved (July 2024): Announced a joint venture with Rajasthan state agricultural cooperatives to develop 10,000 hectares of certified organic aloe vera cultivation, supporting organic aloe vera extract supplement supply [2].
  • Forever Living Products (April 2024): Invested USD 30 million in AI-powered quality control systems across its Dominican Republic and Texas processing plants, improving aloe vera gel topical ingredient consistency.
  • IASC (International Aloe Science Council) (January 2024): Released updated certification standards for aloe vera identity and purity, targeting adulteration in the aloe vera extract market [18].
  • Terry Laboratories (September 2023): Secured long-term supply contracts with three major European cosmetics brands for certified-organic inner leaf aloe vera extract [15].


Aloe Vera Extract Market Report Scope

Parameter Detail
Market Scope Global aloe vera extract market across product form, nature, application, and geography
Study Period 2021–2035
CAGR (Forecast Period) 8.12% (2026–2035)
Base Year Market Size USD 3.34 Billion (2025)
Forecast Endpoint USD 7.48 Billion (2035)
Fastest Growing Segment Organic (by nature); Pharmaceuticals (by application)
Companies Profiled 10
Valuation Currency USD Billion

FAQs

What acemannan concentration should buyers specify when sourcing pharmaceutical-grade aloe vera extract?
Pharmaceutical-grade inner leaf aloe vera extract typically requires a minimum acemannan content of 10–15% (w/w), verified through HPLC testing per IASC standards. Buyers should request certificates of analysis with batch-specific polysaccharide profiling [18].
How does freeze-dried aloe vera powder compare to spray-dried variants for supplement use?
Freeze-dried powder retains 30–40% more bioactive polysaccharides than spray-dried alternatives, making it preferred for organic aloe vera extract supplement formulations. The trade-off is a 2–3× higher processing cost per kilogram [10].
What regulatory pathway applies to aloe vera extract in EU cosmetic products?
EU cosmetics containing aloe vera cosmetic formulation must comply with Regulation (EC) 1223/2009, including safety assessments and ingredient traceability documentation. No pre-market authorization is required, but post-market surveillance obligations apply [5].
Which contract terms protect buyers against aloe vera adulteration?
Buyers should mandate third-party identity testing (DNA barcoding or HPLC acemannan quantification) at receipt, with contractual penalty clauses for maltodextrin or malic acid adulteration exceeding 1% threshold [18].
How do vertical integration economics differ between Indian and Mexican aloe producers?
Indian producers benefit from lower labor costs (USD 3–5/day vs. USD 15–20 in Mexico) but face higher logistics costs to reach Western markets. Mexican producers hold a freight advantage for the North American aloe vera extract market supply [12].
What shelf-life considerations apply to liquid aloe vera extract in beverage formulations?
Aseptic-processed aloe vera juice health drink concentrates achieve 18–24 months ambient shelf life, while pasteurized variants require refrigeration and last 6–9 months. pH stabilization below 4.2 is critical for microbial safety [9].
How are blockchain traceability platforms being adopted in the aloe vera supply chain?
Several aloe vera extract market leaders pilot blockchain from farm to processor, enabling batch-level provenance tracking. Adoption remains below 10% of global trade volume but is accelerating among organic-certified suppliers serving European buyers [14].    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed scientific journals, agricultural and botanical publications, and authoritative health and wellness organizations. Key sources included the US Food & Drug Administration (FDA), European Food Safety Authority (EFSA), US Department of Agriculture (USDA), Food and Agriculture Organization of the United Nations (FAO), International Aloe Science Council (IASC), International Trade Centre (ITC) Trade Map, National Center for Biotechnology Information (NCBI/PubMed), World Health Organization (WHO) Traditional Medicine Strategy, Organic Trade Association (OTA), Cosmetics Europe, Personal Care Products Council (PCPC), International Federation of Societies of Cosmetic Chemists (IFSCC), US National Institutes of Health (NIH) Office of Dietary Supplements, EU Eurostat Agri-Environmental Indicators, US National Agricultural Statistics Service (NASS), and national agricultural ministry reports from key aloe vera producing regions (Mexico, Dominican Republic, China, India, Thailand). These sources were used to collect cultivation statistics, export/import trade data, regulatory approval frameworks, clinical efficacy studies, organic certification trends, and competitive landscape analysis for liquid extracts, powder extracts, gels, and other product forms across food & beverage, cosmetics, pharmaceutical, and nutraceutical applications.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Agricultural Operations, heads of extraction technology, regulatory compliance officers, and commercial directors from aloe vera growers, extract producers, and private label/OEM suppliers were examples of supply-side sources. Procurement managers from food and beverage companies, R&D directors from cosmetic and personal care brands, formulators from pharmaceutical companies, category managers from nutraceutical companies, and sustainability officers from retail chains were examples of demand-side suppliers. In addition to gathering information on formulation innovation, clean-label adoption patterns, supply chain sustainability activities, and pricing dynamics across wholesale, retail, and industrial channels, primary research validated market segmentation and verified organic vs. conventional sourcing tactics.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping, production volume analysis, and trade flow assessment. The methodology included:

Identification of 60+ key cultivators and extract manufacturers across North America, Latin America, Europe, Asia-Pacific, and Africa

Product mapping across liquid extracts, powder extracts, gels, and concentrate forms

Application analysis spanning food & beverages, cosmetics & personal care, pharmaceuticals, and nutraceuticals

Source differentiation between organic aloe vera and conventional aloe vera cultivation practices

Functionality assessment covering laxative effects, skin soothing properties, and nutritional supplement applications

Analysis of reported and modeled annual revenues specific to aloe vera extract portfolios

Coverage of manufacturers and suppliers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (cultivation volume × extraction yield × ASP by country) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations, cross-referenced with ITC trade statistics and FAO agricultural production data

This methodology ensures comprehensive coverage of the aloe vera extract value chain from agricultural sourcing through end-use applications, with particular emphasis on organic certification trends, clean-label demand drivers, and regional cultivation dynamics.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















