3D Projector Market (2026 - 2035)

3D Projector Market Size, Share and Research Report By Technology (Digital Light Processing (DLP), Liquid Crystal Display (LCD), Liquid Crystal on Silicon (LCoS)), By Resolution (HD (1280 x 720), Full HD (1920 x 1080), 4K (3840 x 2160), 8K (7680 x 4320)), By Brightness Level (Low (less than 1000 lumens), Medium (1000-3000 lumens), High (more than 3000 lumens)), By Application (Education, Business, Home Theater, Gaming, Event Venues), By Portability (Portable Projectors, Semi-Portable Projectors, Stationary Projectors) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast Till 2035
ID: MRFR/SEM/29693-HCR 128 Pages Aarti Dhapte, Aarti Dhapte Last Updated: September 10, 2026
3D Projector Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.32%
2025 Market SizeUSD 4.53 billion
2035 Market SizeUSD 8.32 billion
Key Players
Sony Corporation
Epson
Barco NV
BenQ Corporation
Optoma Corporation
Christie Digital Systems
Opportunities
  • Immersive Experience Venues and Location-Based Entertainment
  • Simulation, Training, and Digital Twin Visualization
  • Smart-City Projection Mapping and Public Art

3D Projector Market Summary

The 3D Projector Market reached a valuation of USD 4.53 billion in 2025 and is projected to grow from USD 4.79 billion in 2026 to USD 8.32 billion by 2035, registering a CAGR of 6.32% over the forecast period (2026โ€“2035). Laser-phosphor illumination breakthroughs and falling cost-per-lumen economics continue to reshape procurement decisions across cinema chains, theme parks, and corporate AV installations. Government-backed digitization programs in education โ€” India's PM e-VIDYA initiative alone earmarked over USD 700 million for classroom technology upgrades through 2025 โ€” are generating sustained demand for high-brightness projection hardware [1].

The 3D Projector Market is experiencing a definitive change in technology. Solid-state laser and LED illumination platforms are increasingly displacing legacy lamp-based systems, which used to be the workhorse of cinema and large-venue projection, offering 30,000+ hours of operating life with no maintenance. Between 2023 and 2025, Samsung and Barco jointly invested approximately USD 480 million in next generation laser cinema platforms, which is indicative of the industryโ€™s desire to move away from mercury-lamp architecturesย [2]. Real-time geometric correction in advanced image processors is also making possible projection mapping installations that would have been impossible five years ago.

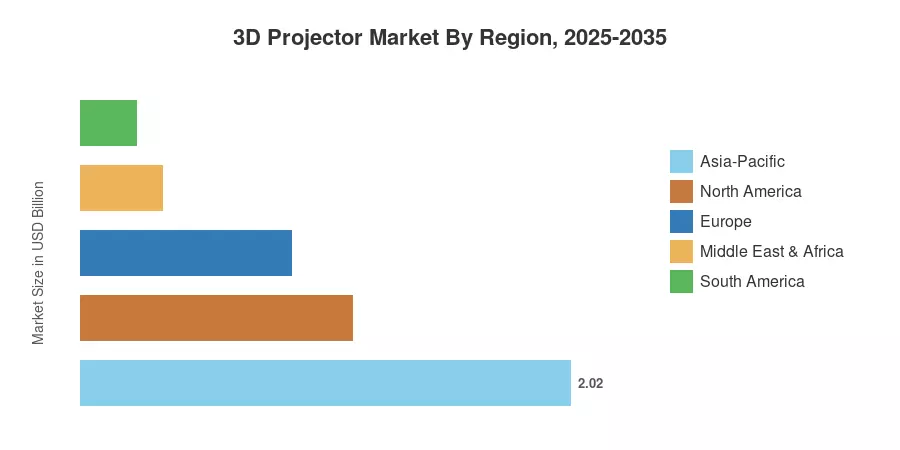
The Asia-Pacific region holds the highest share of the 3D Projector Market, generating almost 44.5% of global revenue in 2025, thanks to the growth of multiplexes in China and India and the deployment of state-funded smart classrooms across Southeast Asia. The Middle East and Africa region is the fastest-expanding geography, with a projected CAGR of 7.40% until 2035, driven by mega-entertainment developments in Saudi Arabia and the UAE that are driving demand for ultra-high-brightness systems. North America remains the second largest region with around 24.8% of the market share, led by premium home-theater adoption and theme-park enhancements across the US. The 3D Projector Market is at the threshold of structural growth, with immersive entertainment, simulation training and hybrid event formats converging around next-generation projection technology.

Key Report Takeaways

โ€ข By Technology

  • DLP systems accounted for 61.2% of the 3D Projector Market in 2025, reflecting the technology's dominance in cinema and large-venue deployments.
  • LCOS projection is forecast to expand at a 6.35% CAGR through 2035, gaining traction in high-resolution simulation and medical imaging applications.

โ€ข By Light Source & Design

  • Laser-illuminated projectors captured 49.1% of the 3D Projector Market share in 2025, outpacing lamp-based units in total cost of ownership.
  • Portable and pico-format projectors are expanding at a 9.35% CAGR, the fastest rate among design categories, as battery technology and miniaturized optics improve.

โ€ข By End User & Geography

  • Cinema end users represented 34.2% of the 3D Projector Market in 2025, though events and large-venue installations are growing at the highest rate within the end-user dimension.
  • Asia-Pacific held a 44.5% revenue share in 2025, while the Middle East and Africa are accelerating at a 7.40% CAGR.

ย 

Market Size and Forecast (2021โ€“2035)

Market Research Futureโ€™s 3D Projector Market sizing is based on a bottom-up approach that integrates shipment statistics, average selling prices and channel intelligence across seven segmentation dimensions. Historical figures (2021โ€“2024) are sourced from audited company filings and customs-trade databases; the forecast window (2026โ€“2035) utilizes econometric regression adjusted for technological adoption curves, policy mandates, and regional cinema-screen development plans.
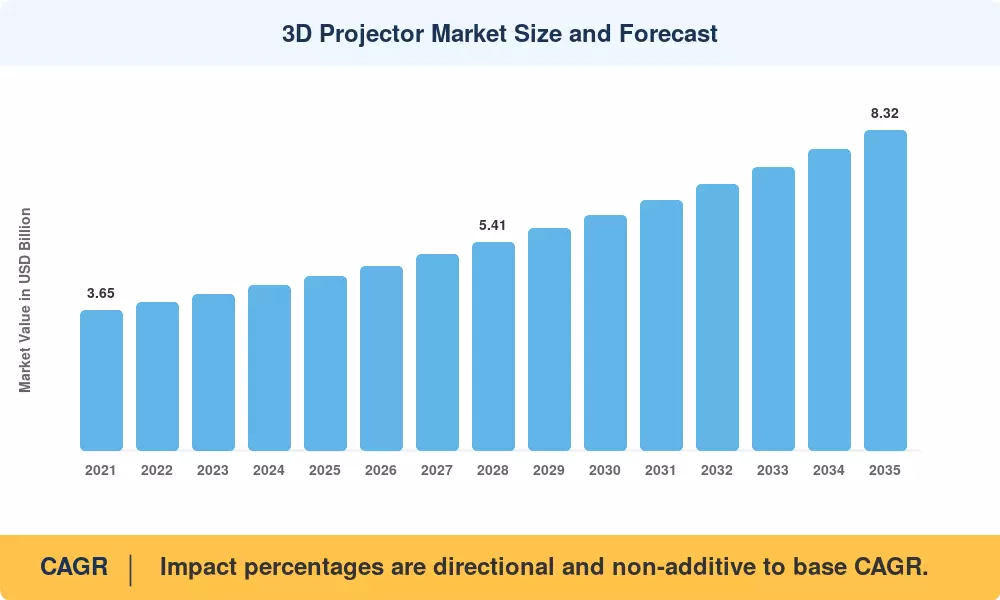
3D Projector Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Laser illumination cost reduction +1.1 Global Short-term (โ‰ค2 yr)
Multiplex and screen expansion in Asia +0.9 Asia-Pacific Medium-term (2โ€“4 yr)
Education sector digital classroom mandates +0.8 Asia-Pacific, Europe Medium-term (2โ€“4 yr)
Immersive entertainment and theme-park buildout +0.7 MEA, North America Long-term (โ‰ฅ4 yr)
4K and 8K resolution demand escalation +0.5 Global Short-term (โ‰ค2 yr)
E-commerce channel expansion for AV equipment +0.4 Global Short-term (โ‰ค2 yr)
Simulation and training sector growth +0.3 North America, Europe Long-term (โ‰ฅ4 yr)

ย 

Laser Illumination Cost Reduction

Solid-state laser light engines have seen a 42% decline in per-unit manufacturing cost between 2020 and 2025, according to IHS Markit channel-pricing data [5]. This cost compression enables cinema operators to achieve payback on laser projector upgrades within 18 months โ€” down from 36 months in 2019 โ€” by eliminating lamp replacement cycles that previously cost USD 800โ€“1,500 per unit annually. The 3D Projector Market is a direct beneficiary as laser platforms also deliver wider color gamuts essential for stereoscopic content.

Multiplex and Screen Expansion in Asia

China's State Film Administration approved construction permits for over 4,200 new cinema screens in 2024 alone, while India's National Centre for Film Exhibition reported a 19% year-over-year rise in multiplex licensing applications [8]. Both markets heavily favor digital 3D-capable systems for premium-format auditoriums, where ticket-price premiums of 30โ€“45% justify the higher capital expenditure. This expansion trajectory underpins the 3D Projector Market's strongest regional growth corridor through 2030.

Education Digital-Classroom Mandates

The European Commission's Digital Education Action Plan (2021โ€“2027) allocated EUR 2.5 billion for technology-equipped classrooms, with interactive projection systems listed as eligible procurement categories [1]. South Korea's Smart Education initiative separately committed KRW 1.2 trillion to replace legacy displays with ultra-short-throw projectors across 11,000 public schools by 2027. These policy-driven purchasing cycles create predictable demand for the 3D Projector Market over the medium term.

Immersive Entertainment and Theme-Park Buildout

Saudi Arabia's NEOM and Qiddiya entertainment districts represent a combined investment exceeding USD 15 billion in immersive venues that rely on ultra-high-brightness projection for ride experiences, dome theaters, and facade mapping [10]. Universal Studios' planned expansions in Orlando and Beijing similarly specify next-generation laser projection arrays. The 3D Projector Market benefits from these capital-intensive projects because projection remains the only viable technology for curved, irregular, and dome-shaped display surfaces at scale.

ย 

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Direct-view LED wall competition โˆ’0.8 Global Medium-term (2โ€“4 yr)
Consumer shift to large-format flat-panel TVs โˆ’0.6 North America, Europe Short-term (โ‰ค2 yr)
High upfront capital cost of โ‰ฅ10,000-lumen systems โˆ’0.5 Emerging markets Long-term (โ‰ฅ4 yr)
Content availability constraints for stereoscopic 3D โˆ’0.3 Global Medium-term (2โ€“4 yr)
Mercury and e-waste regulatory pressures on lamp systems โˆ’0.2 Europe Short-term (โ‰ค2 yr)

ย 

Direct-View LED Wall Competition

MicroLED and fine-pitch LED video walls have dropped below USD 1,200 per square meter at 1.2 mm pixel pitch, making them a credible alternative to projection in corporate boardrooms and mid-size venues [16]. Samsung's The Wall and LG's Magnit lines are actively marketed as "projector replacements," and AV integrators report that LED walls now account for 28% of bids that would have specified projection three years ago. This substitution pressure constrains the 3D Projector Market in the fixed-installation corporate segment, though projection retains advantages in venues exceeding 200-inch diagonal and in dome or irregular-surface applications.

Consumer Shift to Large-Format Flat-Panel TVs

The average selling price of 85-inch 4K televisions fell below USD 1,000 in North America by late 2024, reducing the price-performance gap that once made home projectors attractive for large-screen entertainment [17]. Consumer 3D projector shipments in the sub-3,000-lumen category declined 11% year-over-year in the US market during 2024, according to CEDIA channel data. This trend limits household penetration and compresses the consumer-facing portion of the 3D Projector Market.

Content Availability Constraints for Stereoscopic 3D

Hollywood studios released only 14 major stereoscopic 3D theatrical titles in 2024, down from 26 in 2018, reflecting a broader creative pivot toward high-dynamic-range 2D presentations [19]. Without a robust content pipeline, cinema operators face difficulty justifying premium 3D screen investments, and consumers have fewer reasons to purchase 3D-capable home equipment. This content gap acts as a demand-side brake on the 3D Projector Market, particularly in the consumer and small-venue segments.

ย 

3D Projector Market Opportunities

Immersive Experience Venues and Location-Based Entertainment

The global location-based entertainment sector is projected to reach USD 14 billion by 2030, with projection-mapped attractions and immersive art exhibitions driving a significant share of that spend [10]. Teamlab, Meow Wolf, and similar operators rely almost exclusively on multi-projector arrays to create room-scale visual environments. The 3D Projector Market stands to capture incremental revenue as these venues proliferate in secondary cities across Asia and Europe.

Simulation, Training, and Digital Twin Visualization

Defense and aviation training simulators consumed over 3,800 high-brightness projection units globally in 2024, and demand is accelerating as militaries shift to synthetic training environments [13]. Boeing's use of full-dome projection for pilot certification and Lockheed Martin's virtual maintenance trainers illustrate how the 3D Projector Market intersects with simulation budgets exceeding USD 9 billion annually. The integration of real-time rendering engines like Unreal Engine 5 with multi-channel projection hardware opens additional opportunities in industrial digital-twin visualization.

Smart-City Projection Mapping and Public Art

Municipal governments in Seoul, Singapore, and Dubai have begun commissioning permanent projection-mapped facades as part of smart-city branding strategies [14]. Seoul's DDP building mapping installation, for instance, uses 34 laser projectors to create a nightly public art display that has attracted over 8 million visitors since launch. These civic-scale deployments represent a new demand category for the 3D Projector Market that did not exist at meaningful scale before 2022.

Emerging-Market Cinema Digitization

Sub-Saharan Africa and Southeast Asia remain significantly under-screened, with Nigeria averaging just 0.5 cinema screens per million people compared to 12.5 in the United States [8]. As local cinema chains such as Filmhouse Group (Nigeria) and Major Cineplex (Thailand) expand into tier-two and tier-three cities, they create greenfield procurement opportunities for the 3D Projector Market. Affordable 4K laser projectors priced below USD 15,000 are making these expansions financially viable.

Projection-as-a-Service and Rental Business Models

Equipment rental and managed-service contracts now account for approximately 18% of professional projector revenue globally, up from 11% in 2020 [6]. This shift toward OpEx-based procurement lowers the barrier to entry for event organizers, houses of worship, and educational institutions that cannot justify capital purchases. The 3D Projector Market benefits from higher utilization rates and recurring revenue streams that stabilize demand cycles.

ย 

3D Projector Market Future Outlook

AI-Driven Content Optimization and Automated Calibration

Artificial intelligence is set to transform how projection systems are deployed and managed. Real-time AI calibration โ€” exemplified by Christie's and Barco's edge-blending algorithms โ€” can reduce multi-projector installation time by 60% and eliminate the need for on-site calibration specialists [13]. The 3D Projector Market will increasingly reward manufacturers who embed machine-learning pipelines for auto-geometry correction, ambient-light compensation, and predictive maintenance alerting directly into projector firmware.

Miniaturization and the Portable Projection Supercycle

Battery-powered pico and portable projectors are entering a performance inflection point. By 2028, LED and laser-phosphor engines in sub-1-kg form factors are expected to deliver 1,000+ ANSI lumens โ€” a threshold that enables daylight-viewable presentations and outdoor entertainment [11]. This miniaturization supercycle will expand the 3D Projector Market's addressable base beyond traditional AV buyers to include content creators, mobile educators, and pop-up retail operators.

Sustainability and Circular-Economy Pressures

The EU's proposed Ecodesign for Sustainable Products Regulation (ESPR) will impose energy-efficiency and recyclability requirements on professional AV equipment starting in 2027 [20]. Lamp-based projectors, with their mercury content and high power consumption, face potential phase-out timelines in European markets. Manufacturers who accelerate the transition to mercury-free solid-state illumination will gain regulatory advantage in the 3D Projector Market, while refurbishment and take-back programs present new service-revenue opportunities.

Convergence with Extended Reality (XR) Platforms

The boundary between projection and mixed-reality display is blurring. Spatial computing platforms from Apple, Meta, and Magic Leap are driving content-creation pipelines that can output to both head-mounted displays and projection-mapped environments simultaneously [15]. The 3D Projector Market stands to benefit from this convergence as enterprise training, architectural visualization, and live events increasingly demand hybrid display ecosystems that combine projectors with AR overlays.

ย 

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific 44.5% revenue share (2025) Multiplex expansion, education digitization, smart-city projects
North America 24.8% revenue share (2025) Premium home theater, theme parks, corporate AV upgrades
Europe 19.2% revenue share (2025) Cultural-venue modernization, simulation training, EU digital mandates
South America 5.0% revenue share (2025) Cinema chain growth, event-based projection rental
Middle East & Africa 7.40% CAGR (2026โ€“2035) Mega-entertainment projects, emerging cinema infrastructure
Total USD 4.53 billion (2025) โ€”

The 3D Projector Market exhibits distinct regional demand profiles shaped by cinema infrastructure maturity, education policy, entertainment investment, and commercial AV adoption rates. Asia-Pacific leads on volume and value, while the Middle East and Africa post the fastest growth trajectory through 2035.

ย 

North America

Country Key Metric Key Driver
United States 78.5% of regional share Theme-park expansion, premium large-format cinema
Canada 12.8% of regional share Education and corporate AV modernization
Mexico 8.7% of regional share Multiplex growth in metro areas

ย 

North America's 3D Projector Market is anchored by the United States, where over 44,000 cinema screens and a robust corporate AV channel sustain consistent replacement demand. Universal Studios' Epic Universe (opened 2025) and Disney's ongoing Imagineering projects collectively specified more than 600 laser projection units, underscoring the region's role as a technology-validation ground for high-brightness systems [10].

Europe

Country Key Metric Key Driver
Germany 6.15% CAGR (2026โ€“2035) Automotive simulation and industrial visualization
United Kingdom 21.4% of regional share West End and cultural-venue upgrades
France 17.8% of regional share Heritage-site projection mapping
Italy USD 0.11 billion (2025) Tourism-driven immersive exhibitions
Spain 5.85% CAGR (2026โ€“2035) Event and hospitality sector growth
Nordic Countries 8.2% of regional share Education technology leadership
Russia 5.1% of regional share State-funded cultural digitization
Rest of Europe USD 0.09 billion (2025) Varied adoption across Eastern Europe

ย 

Europe's 3D Projector Market benefits from the EU's Digital Europe Programme, which allocates EUR 7.5 billion for technology adoption across member states through 2027 [1]. Germany leads in simulation and automotive-visualization applications, while France's Culturespaces operates the largest network of immersive digital art centers in Europe, each deploying 50โ€“140 projection units per venue.

Asia-Pacific

Country Key Metric Key Driver
China 38.2% of regional share Cinema screen buildout, projection mapping
India 7.15% CAGR (2026โ€“2035) Smart-classroom mandates, multiplex expansion
Japan USD 0.29 billion (2025) Enterprise AV and theme-park technology
South Korea 11.5% of regional share Digital signage and immersive entertainment
ASEAN 6.85% CAGR (2026โ€“2035) Emerging cinema markets, tourism venues
Rest of Asia-Pacific 7.3% of regional share Australia, New Zealand AV markets

ย 

The Asia-Pacific 3D Projector Market is propelled by China's film industry, which operated over 86,000 cinema screens by end-2024 โ€” the largest installed base globally [8]. India's Multiplex Association reported that 3D-equipped screens increased by 22% in 2024 as PVR INOX and Cinepolis India accelerated tier-two city rollouts. Japan's strength in enterprise AV โ€” driven by corporate boardroom upgrades and theme-park operators like Oriental Land Company โ€” adds a stable high-value demand layer.

South America

Country Key Metric Key Driver
Brazil 58.4% of regional share Cinemark and Cinepolis expansion
Argentina 5.55% CAGR (2026โ€“2035) Event production and rental market
Rest of South America USD 0.05 billion (2025) Gradual digitization across smaller markets

ย 

Brazil dominates South America's 3D Projector Market, supported by Latin America's largest cinema circuit and a growing events industry centered on Sรฃo Paulo and Rio de Janeiro. The country's digital-cinema transition, largely completed by 2023, has shifted procurement toward laser-based replacement cycles that will sustain demand through the late 2020s.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 34.6% of regional share Qiddiya, NEOM, entertainment mega-projects
UAE 28.1% of regional share Expo legacy venues, luxury hospitality
South Africa 5.90% CAGR (2026โ€“2035) Cinema chain expansion
Egypt 5.65% CAGR (2026โ€“2035) New administrative capital AV infrastructure
Rest of MEA USD 0.04 billion (2025) Early-stage adoption across Sub-Saharan Africa

ย 

The Middle East and Africa represent the fastest-growing corridor for the 3D Projector Market, powered by Saudi Arabia's Vision 2030 entertainment liberalization. Qiddiya's entertainment district alone has budgeted over USD 3 billion for immersive attractions requiring large-format projection arrays [10]. The UAE's post-Expo 2020 legacy venues in Dubai continue to generate replacement and upgrade demand for high-brightness laser systems.

ย 

3D Projector Market By Region, 2025-2035

3D Projector Market Segmentation

By Technology (DLP, LCD, LCOS)

Segment Key Metric Primary Demand Driver
DLP 61.2% market share (2025) Cinema, large-venue, high-contrast applications
LCD USD 0.98 billion (2025) Education, budget commercial installations
LCOS 6.35% CAGR (2026โ€“2035) Medical imaging, simulation, high-resolution niche

ย 

DLP technology maintains a commanding position in the 3D Projector Market owing to its superior contrast ratios and reliability in 24/7 commercial environments. Texas Instruments' DLP Cinema chipsets remain the de facto standard for theatrical exhibition, with over 95% of global cinema projectors built on DLP architecture. The technology's micro-mirror design also lends itself to compact pico projectors, giving DLP reach across both professional and consumer price bands.

LCOS (Liquid Crystal on Silicon) is gaining ground in applications that prioritize pixel density over raw brightness. Medical imaging suites and flight-simulation domes โ€” where resolution fidelity directly impacts training outcomes โ€” are shifting toward 4K LCOS engines from manufacturers like JVC and Sony. While LCOS's share remains modest, its above-average CAGR reflects growing willingness among niche buyers to pay premium prices for superior image quality.

By Light Source (Laser, LED, Lamp)

Segment Key Metric Primary Demand Driver
Laser 49.1% market share (2025) Cinema, large venues, total cost of ownership advantage
LED 8.65% CAGR (2026โ€“2035) Portable projectors, consumer home entertainment
Lamp (Metal Halide / UHP) USD 0.84 billion (2025) Legacy installed base, budget-tier replacements

ย 

Laser illumination's dominance in the 3D Projector Market reflects both performance superiority and economic logic. A laser projector eliminates lamp replacements that cost operators USD 300โ€“1,500 per cycle, while delivering wider color gamuts and instant-on operation. Major cinema chains โ€” including AMC, Wanda, and CGV โ€” have committed to full laser fleet conversions by 2028.

LED light sources represent the fastest-growing segment, driven by the portable and pico projector categories where low heat generation, compact form factors, and 30,000+ hour lifespans are critical differentiators. Active and passive 3D projection systems using LED illumination have found particular traction in consumer home-entertainment setups, where noise levels and energy efficiency matter more than raw brightness.

By Brightness

Segment Key Metric Primary Demand Driver
Less than 2,000 lumens USD 0.41 billion (2025) Consumer pico projectors, personal use
2,000โ€“3,999 lumens 5.90% CAGR (2026โ€“2035) Education, small meeting rooms
4,000โ€“9,999 lumens 37.9% market share (2025) Corporate AV, mid-size venues, worship facilities
โ‰ฅ10,000 lumens 7.75% CAGR (2026โ€“2035) Cinema, theme parks, large-venue mapping

ย 

The 4,000โ€“9,999-lumen segment occupies the largest share of the 3D Projector Market because it serves the broadest installed base of corporate, education, and mid-size entertainment venues. These projectors balance brightness, cost, and physical footprint in ways that neither pico units nor cinema-grade platforms can replicate across the general commercial market.

By Design (Fixed Installation, Portable/Pico)

Segment Key Metric Primary Demand Driver
Fixed Installation 73.1% market share (2025) Cinema, corporate, education permanent setups
Portable / Pico 9.35% CAGR (2026โ€“2035) Mobile presentations, consumer entertainment, pop-up retail

ย 

Fixed-installation projectors account for the bulk of the 3D Projector Market by value, reflecting the higher average selling prices of cinema and large-venue units. Portable and pico models, however, are closing the performance gap rapidly โ€” 4K 3D projectors for home theater in the portable segment now deliver image quality that rivals entry-level fixed units at a fraction of the weight and cost.

By End-User Application

Segment Key Metric Primary Demand Driver
Cinema 34.2% market share (2025) Theatrical exhibition, premium-format auditoriums
Education USD 0.63 billion (2025) Classroom digitization mandates, interactive learning
Events & Large Venues 6.90% CAGR (2026โ€“2035) Concerts, conferences, immersive exhibitions
Enterprise / Corporate 5.95% CAGR (2026โ€“2035) Boardroom AV, digital signage, retail
Simulation & Training USD 0.34 billion (2025) Defense, aviation, medical training

ย 

Cinema remains the anchor end-user for the 3D Projector Market, although its dominance is gradually moderating as events, enterprise, and simulation verticals grow at faster rates. Events and large-venue installations are posting the strongest CAGR, fueled by the explosion of immersive art exhibitions and projection-mapped concert tours that demand multi-projector arrays with edge-blending capabilities.

By Sales Channel

Segment Key Metric Primary Demand Driver
Direct 38.5% market share (2025) Large cinema and enterprise contracts
Distributors & VARs USD 1.62 billion (2025) System integrators, AV consultants
E-Commerce 7.10% CAGR (2026โ€“2035) Consumer portables, SMB procurement

ย 

ย 

Competitive Benchmarking

The 3D Projector market is moderately concentrated, with the top five companies anticipated to account for 48-55% of revenues. The Herfindahl-Hirschman Index (HHI) for the industry is in the 900-1,200 range, typical of a market with a few established electronics giants competing against a few specialist projection makers. Laser lighting IP, 4K chipset integration and managed service delivery models are seeing more competition.

Company Est. Revenue Share Range Key Offerings for 3D Projector Market Strategic Positioning
Sony Corporation ~10โ€“14% SXRD laser cinema projectors, 4K home-cinema VPL series Premium imaging leader in cinema and simulation
Epson (Seiko Epson) ~9โ€“13% 3LCD laser projectors for education and enterprise Largest unit-volume manufacturer for commercial segment
Barco NV ~8โ€“11% Laser cinema series, ClickShare collaboration platforms Dominant in premium cinema and control-room projection
BenQ Corporation ~6โ€“9% DLP home-theater and education projectors Price-performance leader in consumer and SMB
Optoma Corporation ~5โ€“8% DLP laser and LED portables, UHD home cinema Strong in home-entertainment and compact-projector channels
Christie Digital Systems ~5โ€“8% CP series cinema, MicroTiles LED-projection hybrid Large-venue and theme-park projection specialist
Panasonic Connect ~4โ€“7% PT-RQ series laser, fixed-install and rental fleet Rental and live-event ecosystem strength
NEC Display Solutions (Sharp NEC) ~3โ€“6% PA series laser, digital signage projectors Enterprise AV and digital signage integration
LG Electronics ~2โ€“5% CineBeam laser, UST home projectors Consumer lifestyle and smart-home convergence
ViewSonic Corporation ~2โ€“4% LED portable and education projectors Budget-tier education and consumer penetration

Recent News & Developments

  • Barco NV (June 2024): Announced a strategic partnership with CJ 4DPlex to integrate Barco laser projection with ScreenX multi-screen cinema formats across 500 theaters in Asia and North America by 2026 [4].
  • Epson (March 2024): Introduced the EB-PU2200 series, its first 20,000-lumen native 4K 3LCD laser projector aimed at rental-staging and large-venue installations, priced 25% below comparable competing models [9].
  • BenQ Corporation (January 2025): Released the HT6550 4K DLP home cinema projector with built-in Android TV and HDR10+ support, expanding its direct-to-consumer smart-projector portfolio [17].
  • Samsung Electronics (July 2024): Unveiled a cinema-grade RGB laser projector at CineAsia 2024, marking its re-entry into the theatrical projection segment after a five-year focus on LED cinema screens [16].
  • Panasonic Connect (April 2025): Deployed 120 PT-RQ50K laser projectors for the Osaka Expo 2025 Japan Pavilion, demonstrating the 3D Projector Market's role in sovereign mega-event branding [10].

ย 

ย 

ย 

3D Projector Market Report Scope

Parameter Detail
Market Scope Global 3D Projector Market covering hardware shipments and associated services
Study Period 2021โ€“2035
CAGR (Forecast Period) 6.32% (2026โ€“2035)
Base Year Market Size USD 4.53 billion (2025)
Forecast Endpoint USD 8.32 billion (2035)
Fastest Growing Segment (Technology) LCOS โ€” 6.35% CAGR
Fastest Growing Segment (Light Source) LED โ€” 8.65% CAGR
Fastest Growing Region Middle East & Africa โ€” 7.40% CAGR
Companies Profiled 10 (Sony, Epson, Barco, BenQ, Optoma, Christie, Panasonic, NEC/Sharp, LG, ViewSonic)
Valuation Currency USD billion
CAGR Driver Disclaimer Impact percentages are directional and non-additive to base CAGR.

FAQs

How do laser projectors compare with lamp-based models on total cost of ownership?
Laser projectors eliminate USD 800โ€“1,500 annual lamp-replacement costs and deliver 30,000+ hours of operation versus 2,000โ€“4,000 hours for lamps. Over a five-year cycle, total cost savings range from 25% to 40% [5].
What warranty and service terms should buyers evaluate when procuring cinema-grade 3D projectors?
Prioritize vendors offering five-year light-source warranties with on-site service-level agreements and guaranteed 48-hour spare-parts delivery. Post-warranty maintenance contracts typically add 3โ€“5% of the original purchase price annually [6].
How does ambient light rejection technology affect 3D projector selection for corporate venues?
ALR screens paired with ultra-short-throw projectors enable usable images in fully lit boardrooms. Buyers should target projectors with โ‰ฅ4,000 lumens and ALR-compatible throw ratios for rooms above 50 lux ambient [7].
What interoperability standards matter most for multi-projector 3D installations?
HDMI 2.1, HDBaseT 3.0, and SDVoE protocols are essential for low-latency 4K signal distribution across blended arrays. DCI compliance is mandatory for theatrical deployments [22].
How are financing models evolving for 3D projector fleet deployments?
Projection-as-a-Service contracts now cover 18% of professional deployments, bundling hardware, maintenance, and upgrades into monthly OpEx payments. Lease terms typically span 36โ€“60 months [6].
What role does HDR support play in differentiating 3D projectors at the premium tier?
HDR10+ and Dolby Vision decoding enable up to 4,000-nit peak brightness reproduction on compatible screens. These capabilities command 15โ€“20% price premiums and are becoming table stakes in premium cinema tenders [17].
How should buyers assess energy-efficiency metrics when comparing 3D projectors for large-venue use?
Compare watts-per-lumen ratios rather than absolute wattage; laser models typically achieve 0.04โ€“0.06 W/lm versus 0.08โ€“0.12 W/lm for lamp units. EU Ecodesign thresholds expected by 2027 will formalize these benchmarks [20]. ย  ย 
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach

ย 

Secondary Research

The secondary research process involved comprehensive analysis of technology databases, industry publications, patent repositories, and authoritative electronics organizations. Key sources included the U.S. Patent and Trademark Office (USPTO), European Patent Office (EPO), Institute of Electrical and Electronics Engineers (IEEE), International Electrotechnical Commission (IEC), Consumer Technology Association (CTA), Society for Information Display (SID), National Institute of Standards and Technology (NIST), U.S. Bureau of Labor Statistics (BLS) - Technology Employment Data, International Trade Administration (ITA), United Nations Conference on Trade and Development (UNCTAD) Technology Database, Organisation for Economic Co-operation and Development (OECD) Digital Economy Outlook, and national electronics industry associations from key markets including Japan Electronics and Information Technology Industries Association (JEITA), Korea Electronics Association (KEA), and China Electronics Chamber of Commerce (CECC).

For Digital Light Processing (DLP), Liquid Crystal Display (LCD), Liquid Crystal on Silicon (LCoS), and emerging laser projection technologies, these sources were used to gather shipment statistics, technology adoption rates, patent filing trends, regulatory compliance data, and competitive landscape analysis.

ย 

Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Product Development, heads of display technology, and regional sales directors from semiconductor foundries, 3D projector makers, and suppliers of optical components were examples of supply-side sources. Demand-side sources included purchase leads from home theater shops, systems integrators, and entertainment venues, as well as procurement directors from educational institutions, corporate AV managers, and technology officers from movie chains. Market segmentation, product roadmap dates, and information on pricing elasticity, channel distribution dynamics, and technology migration patterns were all verified by primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (38%), Europe (25%), Asia-Pacific (32%), Rest of World (5%)

ย 

Market Size Estimation

Unit shipment analysis and revenue mapping along the value chain were used to determine the global market valuation. The methodology comprised:

35+ important manufacturers in North America, Europe, Asia-Pacific, and Latin America were identified.

Technology mapping for DLP, LCD, LCoS, and laser-based projection types

Examination of annual revenues for 3D projector product lines, both reported and modeled

coverage of producers accounting for 75โ€“80% of the world market in 2024

Extrapolation across resolution tiers (HD, Full HD, 4K, 8K), brightness categories (Low <1000 lumens, Medium 1000-3000 lumens, High >3000 lumens), and application verticals (Education, Business, Home Theater, Gaming, Event Venues) using top-down (component supplier revenue validation) and bottom-up (unit shipments ร— ASP by technology and region) techniques

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















