3D Projector Market (2026 - 2035)

ID: MRFR/SEM/29693-HCR 128 Pages Aarti Dhapte Last Updated: September 17, 2026
3D Projector Market Size, Share and Research Report By Technology (Digital Light Processing (DLP), Liquid Crystal Display (LCD), Liquid Crystal on Silicon (LCoS)), By Resolution (HD (1280 x 720), Full HD (1920 x 1080), 4K (3840 x 2160), 8K (7680 x 4320)), By Brightness Level (Low (less than 1000 lumens), Medium (1000-3000 lumens), High (more than 3000 lumens)), By Application (Education, Business, Home Theater, Gaming, Event Venues), By Portability (Portable Projectors, Semi-Portable Projectors, Stationary Projectors) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast Till 2035
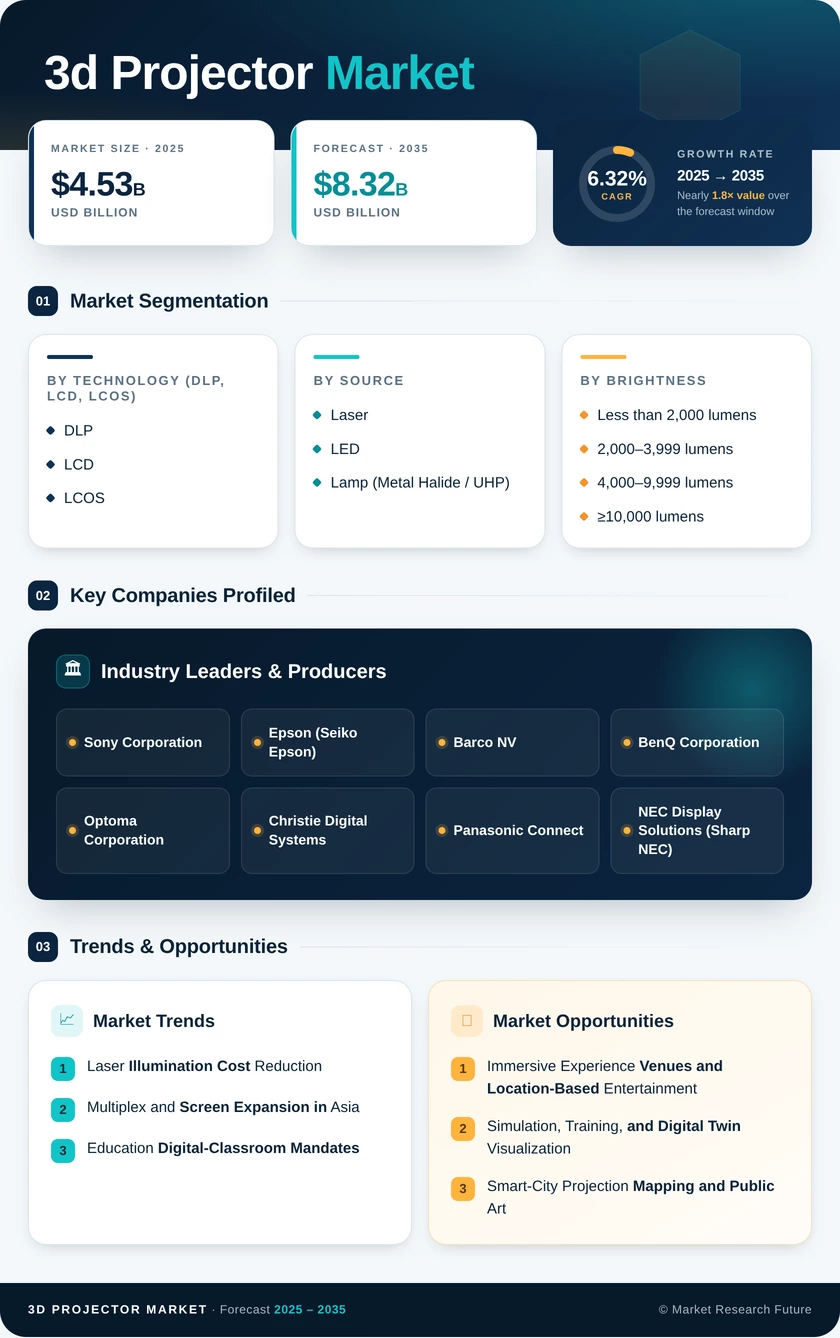
3D Projector Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.32%
2025 Market SizeUSD 4.53 billion
2035 Market SizeUSD 8.32 billion
Key Players
Sony Corporation
Epson
Barco NV
BenQ Corporation
Optoma Corporation
Christie Digital Systems
Opportunities
  • Immersive Experience Venues and Location-Based Entertainment
  • Simulation, Training, and Digital Twin Visualization
  • Smart-City Projection Mapping and Public Art
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 Laser Illumination Cost Reduction | |
      2. 3.1.2 Multiplex and Screen Expansion in Asia | |
      3. 3.1.3 Education Digital-Classroom Mandates | |
      4. 3.1.4 Immersive Entertainment and Theme-Park Buildout | |
      5. 3.1.5 4K and 8K Resolution Demand Escalation | |
      6. 3.1.6 E-Commerce Channel Expansion for AV Equipment | |
      7. 3.1.7 Simulation and Training Sector Growth |
    2. 3.2 Market Restraints Analysis | |
      1. 3.2.1 Direct-View LED Wall Competition | |
      2. 3.2.2 Consumer Shift to Large-Format Flat-Panel TVs | |
      3. 3.2.3 High Upfront Capital Cost of ≥10,000-Lumen Systems | |
      4. 3.2.4 Content Availability Constraints for Stereoscopic 3D | |
      5. 3.2.5 Mercury and E-Waste Regulatory Pressures on Lamp Systems |
    3. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Immersive Experience Venues and Location-Based Entertainment | |
      2. 3.3.2 Simulation, Training, and Digital Twin Visualization | |
      3. 3.3.3 Smart-City Projection Mapping and Public Art | |
      4. 3.3.4 Emerging-Market Cinema Digitization | |
      5. 3.3.5 Projection-as-a-Service and Rental Business Models |
    4. 3.4 Industry Value Chain Analysis |
    5. 3.5 Porter's Five Forces Analysis
  4. 4 Global 3D Projector Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Technology | |
      1. 5.1.1 DLP | |
      2. 5.1.2 LCD | |
      3. 5.1.3 LCOS |
    2. 5.2 By Light Source | |
      1. 5.2.1 Laser | |
      2. 5.2.2 LED | |
      3. 5.2.3 Lamp (Metal Halide / UHP) |
    3. 5.3 By Brightness | |
      1. 5.3.1 Less than 2,000 Lumens | |
      2. 5.3.2 2,000–3,999 Lumens | |
      3. 5.3.3 4,000–9,999 Lumens | |
      4. 5.3.4 ≥10,000 Lumens |
    4. 5.4 By Design | |
      1. 5.4.1 Fixed Installation | |
      2. 5.4.2 Portable / Pico |
    5. 5.5 By End-User Application | |
      1. 5.5.1 Cinema | |
      2. 5.5.2 Education | |
      3. 5.5.3 Events & Large Venues | |
      4. 5.5.4 Enterprise / Corporate | |
      5. 5.5.5 Simulation & Training |
    6. 5.6 By Sales Channel | |
      1. 5.6.1 Direct | |
      2. 5.6.2 Distributors & VARs | |
      3. 5.6.3 E-Commerce
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 India | |
      3. 6.3.3 Japan | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 Sony Corporation | |
      2. 7.3.2 Epson (Seiko Epson) | |
      3. 7.3.3 Barco NV | |
      4. 7.3.4 BenQ Corporation | |
      5. 7.3.5 Optoma Corporation | |
      6. 7.3.6 Christie Digital Systems | |
      7. 7.3.7 Panasonic Connect | |
      8. 7.3.8 NEC Display Solutions (Sharp NEC) | |
      9. 7.3.9 LG Electronics | |
      10. 7.3.10 ViewSonic Corporation
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 AI-Driven Content Optimization and Automated Calibration |
    2. 8.2 Miniaturization and the Portable Projection Supercycle |
    3. 8.3 Sustainability and Circular-Economy Pressures |
    4. 8.4 Convergence with Extended Reality (XR) Platforms
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 12 LIST OF TABLES |
  13. TABLE 1 Global 3D Projector Market Size & Forecast, by Revenue (USD billion), 2021–2035 |
  14. TABLE 2 Global 3D Projector Market — Year-over-Year Growth Analysis, 2021–2035 |
  15. TABLE 3 Global 3D Projector Market — Driver Impact Analysis |
  16. TABLE 4 Global 3D Projector Market — Restraint Impact Analysis |
  17. TABLE 5 Global 3D Projector Market Size, by Technology, 2021–2035 (USD billion) |
  18. TABLE 6 Global 3D Projector Market Size, by Light Source, 2021–2035 (USD billion) |
  19. TABLE 7 Global 3D Projector Market Size, by Brightness, 2021–2035 (USD billion) |
  20. TABLE 8 Global 3D Projector Market Size, by Design, 2021–2035 (USD billion) |
  21. TABLE 9 Global 3D Projector Market Size, by End-User Application, 2021–2035 (USD billion) |
  22. TABLE 10 Global 3D Projector Market Size, by Sales Channel, 2021–2035 (USD billion) |
  23. TABLE 11 Global 3D Projector Market Size, by Region, 2021–2035 (USD billion) |
  24. TABLE 12 North America 3D Projector Market Size, by Country, 2021–2035 (USD billion) |
  25. TABLE 13 Europe 3D Projector Market Size, by Country, 2021–2035 (USD billion) |
  26. TABLE 14 Asia-Pacific 3D Projector Market Size, by Country, 2021–2035 (USD billion) |
  27. TABLE 15 South America 3D Projector Market Size, by Country, 2021–2035 (USD billion) |
  28. TABLE 16 Middle East & Africa 3D Projector Market Size, by Country, 2021–2035 (USD billion) |
  29. TABLE 17 Competitive Benchmarking Matrix — Global 3D Projector Market, 2025 |
  30. TABLE 18 Company Profiles — Key Players, Global 3D Projector Market |
  31. TABLE 19 Recent Developments & Strategic Announcements, 2023–2025 |
  32. TABLE 20 Report Scope & Methodology Summary |
  33. TABLE 21 Detailed Sources and Citations
  34. 13 LIST OF FIGURES |
  35. FIGURE 1 Global 3D Projector Market Dynamics — Drivers, Restraints, and Opportunities |
  36. FIGURE 2 Industry Value Chain Analysis — 3D Projector Market |
  37. FIGURE 3 Porter's Five Forces Analysis — 3D Projector Market |
  38. FIGURE 4 Global 3D Projector Market Size Trend (USD billion), 2021–2035 |
  39. FIGURE 5 Global 3D Projector Market Share, by Technology (%), 2025 |
  40. FIGURE 6 Global 3D Projector Market Share, by Light Source (%), 2025 |
  41. FIGURE 7 Global 3D Projector Market Share, by Brightness (%), 2025 |
  42. FIGURE 8 Global 3D Projector Market Share, by Design (%), 2025 |
  43. FIGURE 9 Global 3D Projector Market Share, by End-User Application (%), 2025 |
  44. FIGURE 10 Global 3D Projector Market Share, by Sales Channel (%), 2025 |
  45. FIGURE 11 Global 3D Projector Market Share, by Region (%), 2025 |
  46. FIGURE 12 North America 3D Projector Market Share, by Country (%), 2025 |
  47. FIGURE 13 Europe 3D Projector Market Share, by Country (%), 2025 |
  48. FIGURE 14 Asia-Pacific 3D Projector Market Share, by Country (%), 2025 |
  49. FIGURE 15 South America 3D Projector Market Share, by Country (%), 2025 |
  50. FIGURE 16 Middle East & Africa 3D Projector Market Share, by Country (%), 2025 |
  51. FIGURE 17 Competitive Landscape — Market Concentration and Key Player Positioning

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
TechnologyDLP, LCD, LCOSDLP (61.2% share, 2025)LCOS (6.35% CAGR)
Light SourceLaser, LED, LampLaser (49.1% share, 2025)LED (8.65% CAGR)
Brightness<2,000 lm; 2,000–3,999 lm; 4,000–9,999 lm; ≥10,000 lm4,000–9,999 lm (37.9% share, 2025)≥10,000 lm (7.75% CAGR)
DesignFixed Installation, Portable/PicoFixed Installation (73.1% share, 2025)Portable/Pico (9.35% CAGR)
End-User ApplicationCinema, Education, Events & Large Venues, Enterprise/Corporate, Simulation & TrainingCinema (34.2% share, 2025)Events & Large Venues (6.90% CAGR)
Sales ChannelDirect, Distributors & VARs, E-CommerceDirect (38.5% share, 2025)E-Commerce (7.10% CAGR)


Market Segmentation Overview

By Technology

Sub-SegmentKey Trend
DLPRemains the cinema-standard technology; expanding into pico form factors via miniaturized chipsets
LCDCost-effective workhorse for education and budget commercial deployments
LCOSRising adoption in medical imaging, simulation, and ultra-high-resolution niche markets


DLP's dominance spans both ends of the brightness spectrum, from sub-500-lumen pico units to 75,000-lumen cinema flagships. LCOS is carving out a high-value niche where pixel density justifies the premium, particularly in defense simulation and surgical visualization.

By Light Source

Sub-SegmentKey Trend
LaserAccelerating cinema fleet conversions; total cost of ownership drives enterprise adoption
LEDFastest-growing source; dominant in portable projectors, gaining ground in education
Lamp (Metal Halide / UHP)Declining share as mercury regulations tighten; persists in budget-replacement cycles.


Laser illumination is the defining technology transition in this market. LED light sources are capturing incremental share through the portable and consumer categories, while lamp-based systems are entering a managed-decline phase.

By Brightness

Sub-SegmentKey Trend
Less than 2,000 lumensConsumer pico and personal-use market; battery-powered mobility is key differentiator
2,000–3,999 lumensClassroom and small-venue workhorses; steady replacement cycle
4,000–9,999 lumensLargest segment by share; corporate AV, worship, and mid-size venue versatility
≥10,000 lumensFastest-growing; cinema, theme parks, and outdoor mapping drive premium demand


High-brightness systems above 10,000 lumens are growing fastest as venues demand images that compete with ambient light conditions and larger screen sizes.

By Design

Sub-SegmentKey Trend
Fixed InstallationDominant in cinema and permanent commercial installations; high ASP anchor
Portable / PicoFastest-growing by CAGR; battery technology and LED/laser miniaturization are catalysts.


Fixed installations continue to generate the majority of market revenue, but the portable segment is where unit-volume growth is most dynamic.

By End-User Application

Sub-SegmentKey Trend
CinemaLargest segment; laser-conversion cycle sustains premium equipment procurement
EducationPolicy-driven demand; interactive ultra-short-throw models gaining share
Events & Large VenuesFastest-growing end-user; projection mapping, immersive exhibitions, live touring
Enterprise / CorporateBoardroom and digital signage; competition from LED walls moderating growth
Simulation & TrainingHigh-value niche; defense, aviation, and medical sectors drive specialized demand


Cinema and events together account for the majority of high-brightness projector procurement, while education represents the largest volume opportunity in the sub-5,000-lumen category.

By Sales Channel

Sub-SegmentKey Trend
DirectPreferred for large cinema and enterprise contracts; highest deal sizes
Distributors & VARsSystem integrators bundle projection with AV infrastructure for turnkey solutions.
E-CommerceFastest-growing channel; consumer portables and SMB buyers driving online procurement


E-commerce is reshaping how mid-market buyers research and procure projection equipment, pushing manufacturers to invest in richer online product configurators and virtual demo tools.


You’ve used 75% of your weekly limit.

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.