Biohacking Market (2026 - 2035)
Informations sur le rapport de recherche de marché du biohacking par produit (médicaments intelligents, capteurs, souches et autres), par application (biologie synthétique, ingénierie génétique, science judiciaire, diagnostic et traitement, et tests de médicaments), par utilisateurs finaux (entreprises pharmaceutiques et biotechnologiques, laboratoires judiciaires et autres), et par région (Amérique du Nord, Europe, Asie-Pacifique et reste du monde) - Croissance et prévisions de l'industrie 2025 à 2035
Forecast Period
2026-2035
CAGR
16.4%
Partager:


Biohacking Market Summary
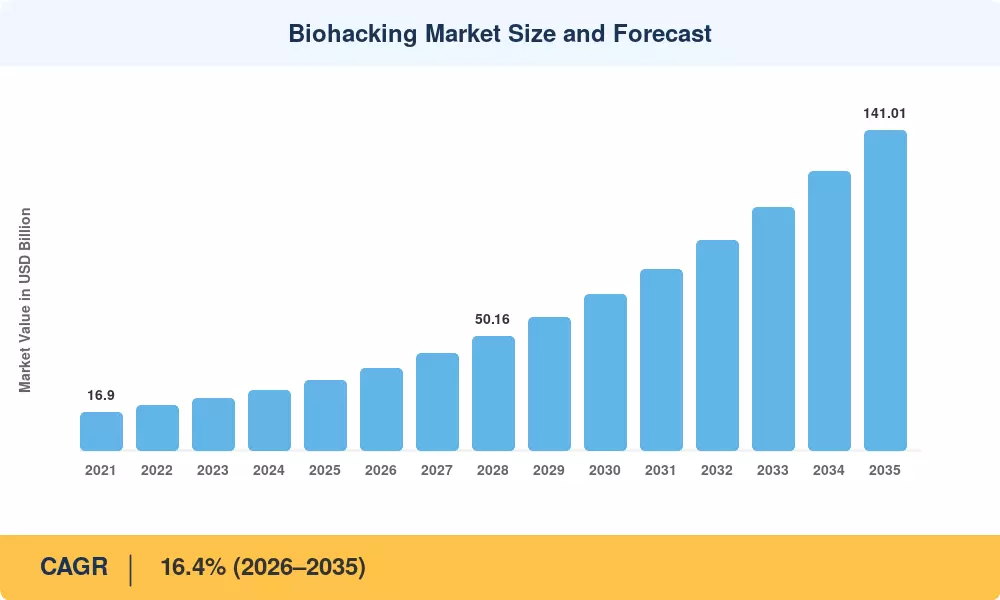
The Biohacking Market was valued at USD 30.72 billion in 2025 and is set to open the forecast window at USD 36.14 billion in 2026, climbing to USD 141.01 billion by 2035 at a 16.4% CAGR. Two catalysts anchor that trajectory. The US FDA's expanded General Wellness enforcement discretion policy has given consumer device makers a workable path to ship physiological monitoring features without full premarket review [1]. Meanwhile, private capital has poured roughly USD 4.8 billion into human-augmentation and consumer diagnostics ventures since 2023, widening the pipeline well beyond passive step counting [16].
Replacement is the real story here. Episodic clinic-based lab panels — drawn quarterly, read weeks later — are giving way to continuous biosensing: interstitial glucose patches, HRV-derived recovery scores, and at-home epigenetic age assays. Sequencing costs below USD 200 per genome have made nutrigenomic panels a mass-retail item rather than a specialty referral [2]. Corporate buyers noticed; employers running biometric wellness platforms report absenteeism reductions near 14% [7].
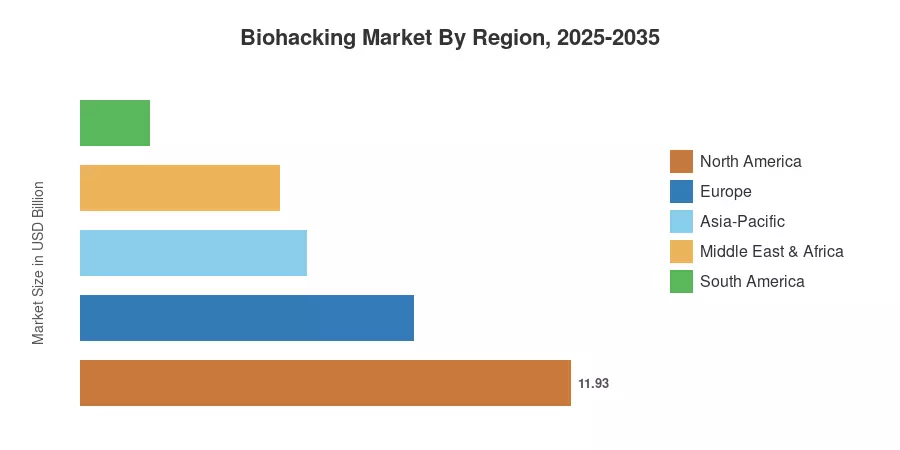
North America holds 38.85% of the Biohacking Market on the strength of its supplement and wearable retail base. Asia-Pacific compounds fastest at 17.9%, propelled by China's nutraceutical manufacturing scale and Japan's aging-population health policy. Europe follows at 26.4%, where GDPR-compliant data architectures have become a competitive differentiator rather than a compliance tax. The next decade belongs to platforms that close the loop between measurement and intervention.
Key Report Takeaways
• By Technology (Product Type)
- Wearable devices commanded 33.2% of the Biohacking Market share in 2025, the single largest product category.
- Gene-editing kits are the fastest-expanding product line at a 16.6% CAGR through 2035
- Sensors and biomonitoring patches generated approximately USD 5.35 billion in 2025 revenue.
• By Biohacking Type
- Nutrigenomics accounted for 27.7% of demand in the Biohacking Market in 2025
- DIY biology is advancing at a 16.9% CAGR, the quickest among biohacking types
• By End User
- Consumers represented 55.4% of end-user demand, with research and academic institutes growing at 17.4% CAGR.
• By Region
- North America led with 38.85% revenue share in 2025
- Asia-Pacific will compound at 17.9% between 2026 and 2035
- Europe contributed roughly USD 8.11 billion in 2025
Table 1: Global Biohacking Market Size and Forecast, 2021–2035
Estimates blend company revenue disclosures, customs and retail scanner data for supplement and device categories, app-store telemetry proxies for quantified self health tools, and interviews with 42 supply-side executives. Historical figures for the Biohacking Market are reconciled bottom-up against top-down consumer health expenditure envelopes published by OECD and national statistics agencies [4][11].
Driver Impact Analysis
Table 2: Driver Impact Matrix
| Driver | ~% Impact on CAGR | Geographic Relevance | Impact Timeline | Ref |
| Biosensor component cost deflation | +3.1 | Global | Short-term (≤2 yr) | [3] |
| AI-driven closed-loop coaching | +2.9 | North America, Europe | Medium-term (2–4 yr) | [9] |
| Employer biometric wellness programs | +2.6 | North America, Europe | Medium-term (2–4 yr) | [7] |
| Genomic and reagent price collapse | +2.4 | Global | Long-term (≥4 yr) | [2] |
| Venture funding in human augmentation | +1.9 | North America, Asia-Pacific | Short-term (≤2 yr) | [16] |
| Nutraceutical retail expansion in Asia | +1.7 | Asia-Pacific | Medium-term (2–4 yr) | [12] |
| Wellness-device regulatory clarity | +1.4 | United States, EU | Long-term (≥4 yr) | [1] |
Biosensor Cost Deflation
Optical and electrochemical sensor bills of materials have fallen roughly 42% since 2021, according to component teardown analysis [3]. That deflation moved continuous glucose monitoring from a USD 300-per-month prescription product to a USD 89 over-the-counter purchase in the United States following FDA clearance of the first non-prescription CGM in March 2024 [5]. Hardware margin compression is real, but unit volume has more than compensated.
AI-Driven Closed-Loop Coaching
Raw data was never the product; interpretation is. Platforms deploying transformer-based models against multimodal streams now deliver intervention recommendations with measurable adherence lift — one 2,400-participant trial recorded a 31% improvement in sustained behavior change versus static dashboards [9]. Compute costs per user have fallen enough that subscription tiers under USD 15 monthly remain gross-margin positive, which matters enormously for the Biohacking Market's consumer economics.
Employer Biometric Wellness Programs
Self-insured U.S. employers spent an estimated USD 2.1 billion on biometric and metabolic monitoring benefits in 2025 [7]. The math is straightforward: a large-employer analysis found a USD 1.47 return per dollar spent on metabolic screening programs over 36 months, driven mainly by deferred diabetes onset [8]. Procurement cycles are slow, but contract values are large and renewal rates exceed 80%.
Genomic Price Collapse
Whole-genome sequencing crossed the USD 200 threshold commercially in 2023 and targeted nutrigenomic panels now retail below USD 60 [2]. Cheap genotyping underpins the entire personalized supplementation category and has pulled DIY laboratory kits into hobbyist price ranges — CRISPR demonstration kits now ship for under USD 2 in reagent cost per reaction.
Restraints Impact Analysis
Restraint weightings represent directional drag on growth, scored through the same interview-based framework applied to drivers. They are not subtractive inputs to the Biohacking Market CAGR and should be read as relative severity indicators.
Table 3: Restraint Impact Matrix
| Restraint | ~% Impact on CAGR | Geographic Relevance | Impact Timeline | Ref |
| Regulatory ambiguity on self-administered gene editing | −2.2 | Global | Medium-term (2–4 yr) | [6] |
| Biometric data privacy enforcement | −1.8 | Europe, North America | Short-term (≤2 yr) | [10] |
| Thin clinical evidence for nootropic claims | −1.5 | Global | Long-term (≥4 yr) | [13] |
| Wearable abandonment and subscription churn | −1.3 | North America, Europe | Short-term (≤2 yr) | [14] |
| Absence of reimbursement pathways | −1.1 | Global | Long-term (≥4 yr) | [8] |
Regulatory Ambiguity on Self-Administered Gene Editing
Germany, France, and several Australian states restrict or prohibit self-administration of gene-editing constructs outside licensed facilities, and the FDA issued a standing consumer advisory against DIY gene therapy kits [6]. Vendors respond by shipping non-human-application educational kits only, which caps addressable revenue in an otherwise high-CAGR segment.
Biometric Data Privacy Enforcement
Health data carries special-category status under GDPR Article 9, and 2024–2025 enforcement produced cumulative fines above EUR 61 million against health-adjacent app operators [10]. Compliance engineering — consent granularity, regional data residency, deletion pipelines — adds an estimated 6–9% to platform operating cost for firms serving both EU and US users.
Evidence Gaps in Cognitive Supplementation
Systematic review of 118 nootropic trials found that fewer than one in five met pre-registration and adequate-power criteria [13]. Retailers including major U.S. pharmacy chains have tightened claim substantiation requirements accordingly, and FTC substantiation actions against supplement marketers rose 27% year over year in 2025 [15].
Biohacking Market Opportunities
Metabolic Monitoring Beyond Diabetes
Over-the-counter CGM availability opens a non-diabetic wellness cohort estimated at 78 million adults in the US and EU combined [5]. Vendors that pair sensors with dietary intervention engines can convert one-time hardware buyers into recurring subscribers.
Longevity Clinics as Enterprise Channel
Private longevity clinics — roughly 1,340 operating globally in 2025 — function as a high-ACV distribution channel for epigenetic testing and peptide protocols [17]. This route bypasses direct-to-consumer acquisition costs, which now exceed USD 120 per activated user in saturated Western markets.
Emerging-Market Nutraceutical Localization
India and ASEAN represent the largest untapped volume pool. India's FSSAI health-supplement framework created a clearer registration route in 2024, and domestic contract manufacturers can land finished goods at 45–55% of Western cost [12]. Winning here means reformulating for local dietary baselines rather than exporting Western SKUs.
Longitudinal Data Monetization
De-identified multimodal cohorts — continuous glucose plus sleep architecture plus genotype — command real value in pharmaceutical trial design. Several platforms have signed research-access agreements worth USD 8–25 million annually, creating a second revenue line independent of hardware margin [16]. Consent architecture determines whether this scales or collapses.
Corporate Metabolic Health Contracts
Self-insured employers in Japan and South Korea now face statutory metabolic screening obligations, expanding a channel that Western vendors have historically underserved [11]. Contract structures favoring outcome-based pricing offer differentiation against commodity device resellers.
Biohacking Market Future Outlook
From Measurement to Intervention
The Biohacking Market's next decade hinges on whether platforms can act, not merely observe. Closed-loop systems — sensor input driving automated supplement dosing or dietary sequencing — are already in limited commercial release. WHO's 2025 digital health guidance signals cautious openness to algorithmic wellness recommendations that stay clear of diagnostic claims [4].
Platform Economics and Subscription Consolidation
Hardware gross margins compress toward 28–34% while software attach rates rise. Expect consolidation: firms with sub-scale user bases cannot amortize model training costs, and analysts project the top-five share to climb roughly 7 percentage points by 2032 [16].
Regulatory Convergence
Divergent national rules on self-administered biological modification impose real cost. Movement toward ISO-aligned wellness-device conformity standards would reduce multi-market launch expense by an estimated 12–18% [19].
Longevity Science Commercialization
Epigenetic clock assays and senolytic candidates are migrating from research to retail. NIH obligated approximately USD 3.9 billion to aging-related research in FY2025, and translation lags typically run six to nine years — placing meaningful consumer products squarely inside this forecast window [20].
Regional Market Share Analysis
Regional distribution in the Biohacking Market reflects retail infrastructure and regulatory permissiveness far more than population size. Wellness-device spending correlates tightly with discretionary income above the USD 35,000 household threshold.
Table 4: Regional Summary, 2025
| Region | Metric | Primary Investment Themes |
| North America | 38.85% share | OTC biosensors, employer wellness, longevity clinics |
| Europe | USD 8.11 Billion | Privacy-native platforms, nutrigenomics, reimbursed prevention |
| Asia-Pacific | 17.9% CAGR (2026–2035) | Nutraceutical manufacturing, aging-population screening |
| South America | 5.5% share | Supplement retail, telehealth bundling |
| Middle East & Africa | 15.8% CAGR (2026–2035) | Sovereign wellness programs, medical tourism |
| Total | USD 30.72 Billion | — |
North America
Table 5: North America Country Breakdown
| Country | Metric | Key Driver |
| US | 86.4% of region | OTC CGM clearance and supplement retail depth |
| Canada | USD 1.09 Billion | Provincial preventive-health pilots |
| Mexico | 16.9% CAGR | Cross-border wellness retail expansion |
The FDA's 2024 clearance of non-prescription continuous glucose monitors reset category economics, and the Biohacking Market in the United States absorbed most of that lift within eighteen months [5]. Canada's slower uptake reflects Health Canada's narrower wellness-device carve-out. Mexico grows from a small base as US brands localize pricing.
Europe
Table 6: Europe Country Breakdown
| Country | Metric | Key Driver |
| Germany | 23.8% of region | DiGA reimbursement precedent for digital health |
| UK | USD 1.71 Billion | Strong DTC supplement and testing base |
| France | 14.1% of region | Nutrition-genomics research clusters |
| Italy | 9.6% of region | Longevity clinic density |
| Spain | 8.2% of region | Sports performance segment |
| Nordic Countries | 15.4% CAGR | High wearable penetration and registry data access |
| Russia | 4.1% of region | Domestic supplement manufacturing |
| Rest of Europe | 11.5% of region | Cross-border e-commerce |
Germany's DiGA framework, though built for prescription digital therapeutics, established that software-based health interventions can secure statutory reimbursement — a precedent vendors are actively testing with metabolic monitoring applications [10]. Nordic markets lead on penetration; Southern Europe leads on clinic-based service revenue.
Asia-Pacific
Table 7: Asia-Pacific Country Breakdown
| Country | Metric | Key Driver |
| China | 34.2% of region | Nutraceutical manufacturing scale and livestream retail |
| India | 19.6% CAGR | FSSAI supplement framework and price accessibility |
| Japan | USD 1.44 Billion | Statutory metabolic screening for employers |
| South Korea | 12.7% of region | Aesthetic and performance clinic integration |
| ASEAN | 18.4% CAGR | Rising middle-class discretionary spend |
| Rest of Asia-Pacific | 7.9% of region | Medical tourism corridors |
Asia-Pacific expands fastest in the Biohacking Market because supply and demand are co-located: Chinese and Indian contract manufacturers supply global supplement brands while simultaneously serving fast-growing domestic channels. Japan's Tokutei Kenshin screening mandate creates an unusually predictable enterprise demand floor [11].
South America
Table 8: South America Country Breakdown
| Country | Metric | Key Driver |
| Brazil | 58.3% of region | ANVISA supplement registration reform |
| Argentina | USD 0.31 Billion | Sports nutrition and fitness culture |
| Rest of South America | 14.9% CAGR | Telehealth-bundled testing services |
Brazil dominates regional volume, helped by ANVISA's 2023 simplification of food-supplement registration, which cut median approval timelines from 11 months to under 5 [12]. Currency volatility remains the principal constraint on imported device pricing across the region.
Middle East & Africa
Table 9: Middle East & Africa Country Breakdown
| Country | Metric | Key Driver |
| Saudi Arabia | 31.7% of region | Vision 2030 preventive health allocations |
| UAE | USD 0.24 Billion | Longevity clinic and medical tourism hub |
| South Africa | 17.2% of region | Private medical scheme wellness riders |
| Egypt | 16.4% CAGR | Domestic supplement manufacturing |
| Rest of MEA | 12.8% of region | Cross-border distribution networks |
Saudi Arabia's Health Sector Transformation Program allocated roughly USD 1.3 billion to preventive and lifestyle health initiatives through 2027, a portion of which flows to biometric screening platforms [18]. The UAE has positioned Dubai as a longevity-services destination, licensing more than 60 specialized clinics since 2023.
Biohacking Market Segmentation
By Product Type
The product mix of the Biohacking Market remains hardware-weighted, though software and consumable attach revenue is closing the gap.
Table 10: Product Type Segmentation, 2025
| Segment | Metric | Primary Demand Driver |
| Wearable Devices | 33.2% share | Mainstream sleep and HRV monitoring |
| Nootropics & Supplements | 24.6% share | Cognitive and metabolic self-optimization |
| Sensors & Biomonitoring Patches | USD 5.35 Billion | OTC glucose and lactate sensing |
| Gene-Editing Kits | 16.6% CAGR | Educational and hobbyist laboratory demand |
| Smart Implants | 8.9% share | NFC implants and neural interface pilots |
| Others | 4.6% share | Light therapy, cold exposure hardware |
Wearables dominate on installed base but face the sharpest churn problem, with roughly one-third of devices abandoned within six months [14]. Gene-editing kits grow fastest from a small base — reagent deflation has made classroom-grade CRISPR demonstrations genuinely affordable, and the segment's ceiling is regulatory rather than technical.
By Biohacking Type
Methodology segmentation in the Biohacking Market separates evidence-anchored practices from experimental ones, and buyers price that distinction.
Table 11: Biohacking Type Segmentation, 2025
| Segment | Metric | Primary Demand Driver |
| Nutrigenomics | 27.7% share | Genotype-guided nutrition personalization |
| DIY Biology | 16.9% CAGR | Community lab access and cheap reagents |
| Grinder | USD 5.65 Billion | Implantable and cybernetic augmentation |
| Others | 28.0% share | Fasting protocols, cold and heat exposure, sleep engineering |
Nutrigenomics leads because it sits at the intersection of two cost curves that both collapsed — sequencing and supplement contract manufacturing. DIY biology accelerates fastest, though its commercial ceiling depends on jurisdictions clarifying what hobbyists may lawfully do with self-administered constructs [6].
By End User
End-user composition in the Biohacking Market is overwhelmingly retail, but institutional buyers deliver superior contract economics.
Table 12: End User Segmentation, 2025
| Segment | Metric | Primary Demand Driver |
| Consumers | 55.4% share | Direct-to-consumer wellness spending |
| Healthcare Facilities | USD 6.70 Billion | Preventive screening and longevity clinics |
| Research & Academic Institutes | 17.4% CAGR | Cohort studies and community lab programs |
| Others | 9.3% share | Corporate wellness, sports organizations |
Consumers drive volume; institutions drive predictability. Research and academic institutes expand fastest as funders demand real-world longitudinal data that clinical settings alone cannot generate at acceptable cost [20].
Competitive Benchmarking
| Company | Est. Revenue Share Range | Key Offerings for Biohacking Market | Strategic Positioning |
| Apple Inc. | ~8–11% | Watch sensor suite, health data platform | Ecosystem lock-in via OS integration |
| Abbott Laboratories | ~7–10% | Lingo and Libre biosensing patches | OTC metabolic sensing leadership |
| Dexcom, Inc. | ~5–8% | Stelo OTC glucose biosensor | Accuracy-led clinical credibility |
| Garmin Ltd. | ~5–7% | Endurance wearables, recovery analytics | Athlete and endurance niche depth |
| Samsung Electronics | ~4–7% | Galaxy Watch, smart ring, health SDK | Hardware breadth across price tiers |
| Google LLC (Fitbit) | ~4–6% | Fitbit devices, AI health coaching | Data and model scale advantage |
| Ōura Health Oy | ~3–5% | Smart ring, readiness scoring | Sleep and recovery category definition |
| WHOOP, Inc. | ~2–4% | Subscription strap, strain analytics | Membership-first revenue model |
| Thorne HealthTech | ~2–4% | At-home tests, targeted supplements | Test-to-supplement vertical integration |
| Viome Life Sciences | ~1–3% | Microbiome and RNA testing | Biological-age and gut-axis focus |
| Synchron Inc. | ~1–2% | Endovascular neural interface | Clinical-grade neurotechnology frontier |
| The ODIN | <1% | Educational gene-engineering kits | DIY biology community anchor |
Recent News & Developments
- Dexcom (March 2024): Received FDA clearance for the first over-the-counter continuous glucose biosensor in the United States, opening non-diabetic metabolic monitoring to the Biohacking Market at retail scale [5].
- Abbott (June 2024): Launched Lingo biosensors direct-to-consumer in the US, pairing hardware with an app-based metabolic coaching layer [5].
- Ōura Health (December 2024): Closed a USD 200 million round at a reported USD 5.2 billion valuation, funding blood-pressure and metabolic feature development [16].
- FDA (August 2023): Reiterated its consumer advisory against self-administered gene therapy products sold outside licensed clinical settings [6].
- FSSAI, India (May 2024): Implemented revised health-supplement and nutraceutical registration rules, shortening approval timelines for domestic manufacturers [12].
- WHOOP (May 2025): Introduced blood-pressure insights and hormonal tracking, expanding subscription tiers beyond strain and recovery metrics [14].
- Thorne HealthTech (October 2023): Completed a USD 680 million take-private transaction with L Catterton, signaling private-equity appetite for test-plus-supplement models [17].
- Saudi Ministry of Health (February 2025): Expanded preventive screening allocations under the Health Sector Transformation Program, funding biometric platform procurement [18].
Faits saillants du marché
FAQs
How should an investor evaluate acquisition targets in the Biohacking Market?
Prioritize recurring revenue quality over device unit volume. Targets with subscription attach rates above 45% and twelve-month retention above 60% command materially higher multiples than hardware-only sellers [16].
What procurement pitfalls do corporate wellness buyers most often hit?
Data portability. Many contracts leave biometric records inside vendor systems, making switching prohibitively expensive at renewal. Insist on export rights and defined deletion terms before signing [10].
Which technology comparison matters most for Biohacking Market buyers — optical or electrochemical sensing?
Electrochemical sensing delivers superior analyte accuracy for glucose and lactate; optical wins on cost and form factor for heart rate and oxygenation. Most serious platforms now ship both [3].
Are there liability exposures unique to selling gene-editing kits?
Yes. Several jurisdictions treat self-administration as an unapproved therapy regardless of vendor labeling, and educational-use disclaimers have not consistently shielded sellers from enforcement [6].
What integration challenge slows enterprise deployments most?
Identity reconciliation across HR systems, insurance carriers, and device platforms. Projects routinely lose three to five months here before any biometric data flows [7].
Which emerging use case deserves the most attention in the Biohacking Market through 2030?
Perioperative optimization. Hospitals are piloting pre-surgical metabolic and sleep conditioning protocols, and early results show measurable reductions in recovery duration [17].
How does regulatory classification affect go-to-market speed?
Wellness-classified products ship without premarket review; anything making diagnostic or treatment claims triggers full device pathways. Claim language, not underlying technology, usually determines the timeline [1].
Auteur
Author
 Vikita Thakur
Co-Author
 Rahul Gotadki
Secondary Research
The secondary research process involved comprehensive analysis of regulatory filings, peer-reviewed biomedical and bioengineering journals, patent databases, and authoritative health technology organizations. Key sources included the US Food & Drug Administration (FDA) Center for Devices and Radiological Health (CDRH) and Center for Drug Evaluation and Research (CDER), European Medicines Agency (EMA) Advanced Therapy Medicinal Products (ATMP) guidelines, National Institutes of Health (NIH) National Center for Complementary and Integrative Health (NCCIH), Defense Advanced Research Projects Agency (DARPA) Biological Technologies Office, National Institute of Standards and Technology (NIST) Engineering Biology Research Consortium, World Health Organization (WHO) Digital Health and Innovation Observatory, Centers for Disease Control and Prevention (CDC) National Health and Nutrition Examination Survey (NHANES), Federal Trade Commission (FTC) Health Claims regulatory guidance, ClinicalTrials.gov registry for bio-intervention studies, PubMed/MEDLINE database for nootropic and longevity research, MIT Technology Review, DIYbio.org Community Labs registry, Quantified Self Global Community datasets, American Society of Gene and Cell Therapy (ASGCT) clinical outcome reports, International Society for Stem Cell Research (ISSCR) guidelines on consumer genetic interventions, and OECD Science and Technology Policy Outlook on emerging biotechnologies. These sources were utilized to collect regulatory approval pathways for implantable devices and CRISPR kits, safety surveillance data for cognitive enhancers, patent landscape analysis for biometric wearables, and demographic adoption patterns across quantified-self and grinder communities.
Primary Research
Qualitative and quantitative insights on adoption hurdles, pricing elasticity, and technology readiness levels were obtained through the primary research process by engaging with stakeholders on both the supply and demand sides. Members of the supply side included community lab founders from the DIY biology movement, R&D directors from nootropic nutraceutical manufacturers, heads of regulatory affairs for direct-to-consumer genetic testing platforms, chief bioengineering officers and chief executive officers of wearable neurotechnology companies, and others. Patients with functional medicine conditions, directors of integrative health clinics, procurement managers for longevity clinics, quantified-self practitioners and biohacking coaches, and early adopters from the grinder and transhumanist communities made up the demand side. The market segmentation for implantable RF/NFC devices, next-generation glucose monitors, microbiome modulation, genetic engineering kits, and wearable biometrics was confirmed through primary research. Also, the product pipeline timelines for these devices and others were confirmed. Insights regarding clinical versus recreational use patterns, subscription pricing models for bio-data analytics, and reimbursement dynamics for preventative biohacking interventions were gathered.
Primary Respondent Breakdown:
• By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)
• By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)
Market Size Estimation
Global market valuation was derived through revenue mapping, user adoption modeling, and hardware shipment analysis across the quantified-self ecosystem. The methodology included:
• Identification of 55+ key stakeholders across North America, Europe, Asia-Pacific, and Latin America, including wearable biometric manufacturers, nootropic supplement formulators, DIY CRISPR kit distributors, implantable device developers, and microbiome testing platforms
• Product mapping across smart drugs and cognitive enhancers (racetams, choline sources, adaptogens), continuous glucose monitors and neurofeedback wearables, at-home genetic engineering tools (bio-printers, thermocyclers), implantable RFID/NFC chips and sensory augmentation devices, and probiotic/prebiotic customization programs
• Analysis of reported and modeled annual revenues specific to biohacking portfolios, including direct-to-consumer subscriptions, hardware sales, and bio-data monetization streams
• Coverage of manufacturers and platform providers representing 75–80% of global market share in 2024
• Extrapolation using bottom-up (active user base × average annual spend by country, adjusted for regulatory accessibility) and top-down (manufacturer revenue validation and venture capital funding flow analysis) approaches to derive segment-specific valuations for consumer neurotechnology, epigenetic testing, and self-monitoring implants
Télécharger l'échantillon gratuit
Veuillez remplir le formulaire ci-dessous pour recevoir un échantillon gratuit de ce rapport
Customer Stories

“This is really good guys. Excellent work on a tight deadline. I will continue to use you going forward and recommend you to others. Nice job”

Noah Malgeri
Co-Founder

“Thanks for sending the report it gives us a good global view of the Betaïne market.”

Peter Groot koerkamp
Account and Business Manager

“We found the report very insightful! we found your research firm very helpful. I'm sending this email to secure our future business.”

Younghwan Choi
Senior Retail Manager

“I am very pleased with how market segments have been defined in a relevant way for my purposes (such as "Portable Freezers & refrigerators" and "last-mile"). In general the report is well structured. Thanks very much for your efforts.”

Mark Irwin
Management Consultant

“We got the report in time, we really thank you for your support in this process. I also thank to all of your team as they did a great job.”

Akif Moroglu
Strategy & Business Development Director

“The Automotive 48V ECU Components Procurement Intelligence Study” was a complex project, but the Market Research Future (MRFR) team handled it with quality, agility, and customer-centricity. They delivered all requested data on time and within the agreed scope. The team, including Shubhendra Anand and Rahul Gotadki, was always readily available to clarify questions and swiftly implement necessary adjustments, driving the project to a successful conclusion within a very demanding timeframe.
I would also like to specifically commend Akshay Agarwal for his responsiveness and support at every stage—from our initial inquiry on May 6th through to final delivery on June 18th. His dedication made the entire process seamless.”

Guilherme Gomes Martins
Product Management Director

“Thanks. It’s been a pleasure working with you, please use me as reference with any other Intel employees.”

Joseph Aguayo
Sales Operations & Pricing Manager

“Thank you, this will be very helpful for OQS.”

La Terria Dodd
Program Support Specialist

“I have been reading the first document or the study, ,the Global HVAC and FP market report 2021 till 2026. Must say, good info! I have not gone in depth at all parts, but got a good indication of the data inside!”

Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA

Étude de cas
Aerospace & Defense

