Cash Management System Market (2026 – 2035)

Informe de investigación de mercado del sistema de gestión de efectivo: Información por tipo de componente (servicios y software), tipo de producto (cheque para compensar, tarjeta de compra, mercado minorista y mayorista, conciliación de cuentas, desembolso controlado, informes de información, transferencia bancaria, compensación automatizada y cuenta de depósito a la vista), implementación (local y en la nube), empresa (pequeña y mediana empresa y gran empresa), usuario final (minorista, servicios bancarios y no bancarios), región (Norteamérica, Europa, Asia-Pacífico): pronóstico hasta 2032
ID: MRFR/ICT/7130-HCR 111 Pages Ankit Gupta Last Updated: September 15, 2026
Cash Management System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.45%
2025 Market SizeUSD 21.85 Billion
2035 Market SizeUSD 43.20 Billion
Key Players
Oracle
FIS
SAP
Fiserv
Kyriba
ACI Worldwide
Opportunities
  • SME Cloud Adoption
  • Embedded Treasury and Banking-as-a-Service
  • Emerging-Market Digital Banking

Cash Management System Market Summary

El Mercado de Sistemas de Gestión de Efectivo alcanzó los 21.85 mil millones de USD en 2025 y se espera que abra la ventana de pronóstico en 23.45 mil millones de USD en 2026 antes de subir a 43.20 mil millones de USD para 2035, avanzando a un CAGR del 7.45% durante el período 2026–2035. Dos catalizadores anclan esta trayectoria: el despliegue global de las vías de pago en tiempo real ISO 20022 y las reglas más estrictas de pruebas de estrés de liquidez de Basilea IV que obligan a los equipos de tesorería a demostrar visibilidad de efectivo siempre activa. Los líderes financieros ya no tratan la supervisión del efectivo como una tarea de oficina trasera; se ha convertido en una disciplina a nivel de junta vinculada al capital de trabajo, riesgo de fraude e informes ESG.

La conciliación de hojas de cálculo heredadas y las interfaces bancarias segregadas están siendo reemplazadas por soluciones nativas de la nube que conectan bancos, ERP y APIs de fintech. Entre los esfuerzos por reducir costos de TI y aumentar la precisión de las predicciones se encuentra un cambio hacia el manejo automatizado de efectivo. Los balances corporativos de EE. UU. todavía tienen 1.76 billones de USD en capital de trabajo atrapado, por lo que la demanda de soluciones de tesorería de efectivo de extremo a extremo sigue siendo estructuralmente sólida y la previsión de flujo de efectivo basada en IA está pasando de proyectos piloto a implementaciones en producción.

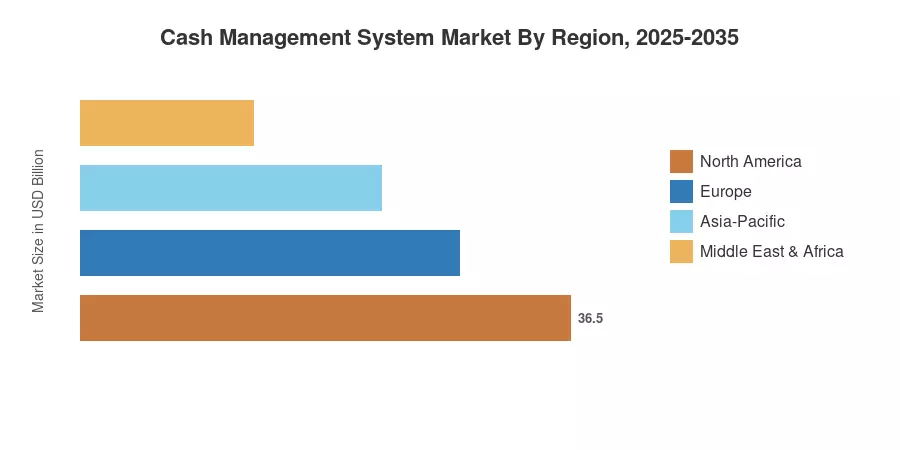
América del Norte es el mercado más grande con un 41.5% de participación en 2025 debido a una infraestructura financiera robusta y la implementación temprana del control de efectivo empresarial. Asia-Pacífico es la región de más rápido crecimiento, con un CAGR del 14.05%, seguida de Europa, que se beneficia de la reforma de tesorería impulsada por regulaciones. Aquellos proveedores que dominen la interoperabilidad ganarán la próxima década.

Sección 2 — Principales Conclusiones del Informe

Por Componente

  • Las implementaciones en la nube capturaron aproximadamente el 67% de la participación del Mercado de Sistemas de Gestión de Efectivo en 2025 a medida que los equipos financieros retiraron pilas locales
  • Las herramientas de previsión de flujo de efectivo están expandiéndose a un CAGR del 17.6%, el segmento de tipo de operación más rápido en el Mercado de Sistemas de Gestión de Efectivo

Por Usuario Final

  • BFSI generó cerca de 5.9 mil millones de USD en valor de sistemas de gestión de efectivo durante 2025, manteniendo su posición de liderazgo
  • El comercio minorista y el comercio electrónico son los verticales de usuario final de más rápido crecimiento con un CAGR del 12.4% hasta 2035

Por Regional

Sección 3 — Tamaño del Mercado y Pronóstico (2021–2035)

El dimensionamiento del mercado combina el seguimiento de ingresos de proveedores de abajo hacia arriba con puntos de referencia de gasto en tecnología de tesorería de arriba hacia abajo, calibrados contra datos de infraestructura bancaria y verificados contra encuestas de aceptación de software corporativo. Los años históricos para (2021-2024) son informes financieros; 2025 es el año base; 2026-2035 son valores pronosticados para el MRFR.
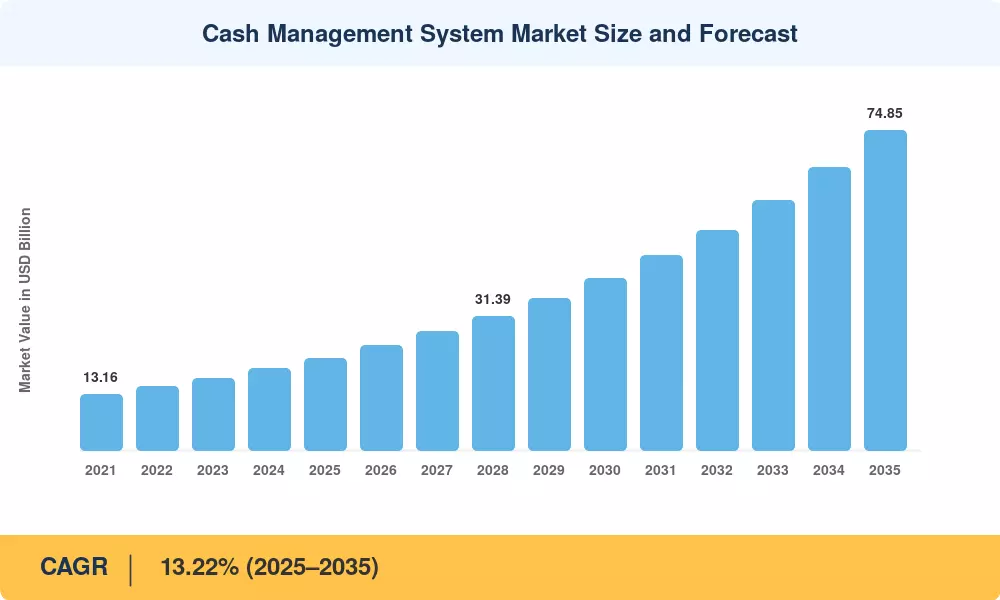
Tamaño y Pronóstico del Mercado de Sistemas de Gestión de Efectivo
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry


Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
ISO 20022 real-time payment rails 21% Global Short-term
AI-based cash-flow forecasting 19% North America, Europe Medium-term
Basel IV liquidity stress tests 16% Europe, North America Short-term
Cloud-native platform migration 15% Global Medium-term
Working capital optimization pressure 12% North America, Asia-Pacific Long-term
Open banking and fintech APIs 10% Europe, Asia-Pacific Medium-term
Fraud and cybersecurity mandates 7% Global Long-term


ISO 20022 Real-Time Payment Rails

The global migration to ISO 20022 messaging is the single strongest driver of automated cash handling demand. SWIFT's coexistence period closes in November 2025, forcing banks and corporates onto richer data formats that enable structured remittance and instant reconciliation. The US Federal Reserve's FedNow service, live since 2023, processed rising instant-payment volumes through 2025, and treasury cash solutions that natively parse ISO 20022 data have become procurement table stakes.

AI-Based Cash-Flow Forecasting

Machine-learning forecasting is shifting from experimental to essential. Vendors report forecast-accuracy gains of 20–30% when AI models replace rule-based projections, directly improving enterprise cash control. With USD 1.76 trillion in working capital locked across US corporates, even modest accuracy improvements unlock meaningful liquidity, making cash flow management tools a CFO-level investment priority.

Basel IV Liquidity Stress Tests

Basel IV's revised liquidity coverage and net stable funding requirements, phasing in through 2025–2028, compel banks to demonstrate granular, real-time cash positions. This regulatory weight pushes financial institutions toward sophisticated treasury cash solutions capable of intraday liquidity monitoring and automated stress-test reporting.

Cloud-Native Platform Migration

The retirement of on-premise treasury workstations is accelerating. Cloud platforms cut infrastructure costs and shorten deployment cycles. Finance leaders increasingly favor subscription-based automated cash handling over capital-heavy installs, broadening the addressable base to include mid-market firms.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Data security and breach exposure 28% Global Long-term
Integration complexity with legacy ERPs 24% North America, Europe Medium-term
High switching and implementation costs 19% Global Short-term
Shortage of skilled treasury technologists 16% Asia-Pacific, MEA Medium-term
Fragmented cross-border banking standards 13% Europe, South America Long-term


Data Security and Breach Exposure

Cash systems concentrate sensitive financial data, making them prime targets. The cost of a financial-sector data breach averaged USD 6.08 million in 2024, and treasury teams remain cautious about exposing payment infrastructure to cloud and API surfaces, slowing some enterprise cash control deployments.

Integration Complexity with Legacy ERPs

Many corporations run decades-old ERP installations that resist clean API connectivity. Stitching modern cash flow management tools into these environments demands costly middleware and custom development, extending implementation timelines and deterring risk-averse buyers.

High Switching and Implementation Costs

Replacing an entrenched treasury platform carries substantial cost and operational risk. Implementation fees, data migration, and staff retraining can run into seven figures for large enterprises, anchoring incumbents and lengthening sales cycles for new automated cash handling vendors.


Cash Management System Market Opportunities

SME Cloud Adoption

Small and medium enterprises represent the largest untapped pool of demand. As cloud pricing falls and onboarding simplifies, lightweight cash flow management tools designed for lean finance teams open a high-growth segment historically priced out of treasury technology

Embedded Treasury and Banking-as-a-Service

Banking-as-a-service lets software vendors embed payments and cash visibility directly into ERP and vertical platforms. This blurs the line between treasury software and banking, creating new revenue models for vendors that position enterprise cash control as a native platform feature

Emerging-Market Digital Banking

Asia-Pacific, Africa, and Latin America are leapfrogging legacy banking infrastructure. Rapid digital-bank rollouts and government real-time payment schemes — India's UPI, Brazil's Pix — create greenfield demand for treasury cash solutions among newly formalized corporates

Cash-Flow Data Monetization

The transaction and forecasting data generated by cash systems hold standalone value. Vendors can monetize anonymized liquidity benchmarks, credit-scoring inputs, and working-capital analytics, turning ATM cash management and treasury data exhaust into a recurring revenue line.

ESG and Sustainable Treasury Reporting

Boards increasingly require treasury teams to track ESG-linked financing and sustainable cash allocation. Platforms that bake ESG reporting into automated cash handling workflows can capture compliance-driven budget


Cash Management System Market Future Outlook

AI and Autonomous Treasury

By the early 2030s, treasury operations will trend toward autonomous cash management — systems that forecast, sweep, and fund positions with minimal human input. AI-based cash-flow forecasting will mature into prescriptive engines that recommend liquidity actions, making cash flow management tools indispensable to the modern finance function.

Platform Economics and Consolidation

The vendor landscape will consolidate around interoperable platforms. As switching costs and integration complexity favor scale, leading vendors will expand through acquisition, and embedded treasury models will redistribute value toward whoever owns the enterprise cash control layer.

Real-Time Everything

The decade ahead belongs to instant settlement. With over 70 countries operating real-time payment schemes by 2025, treasury cash solutions must process continuous, 24/7 cash flows. ATM cash management and physical-cash logistics will increasingly integrate with digital rails into unified visibility layers.

ESG-Linked Cash Governance

Sustainability reporting will reshape treasury mandates. Regulators and boards will expect cash allocation tied to ESG criteria, and automated cash handling platforms that embed sustainability metrics will capture compliance-driven budget through the back half of the forecast period.

Regional Market Share Analysis

Region 2025 Share (%) Primary Investment Themes
North America 41.5 Real-time rails, AI forecasting
Europe 27.0 Basel IV compliance, open banking
Asia-Pacific 21.0 Digital banking, SME adoption
South America 6.5 Pix-driven modernization
Middle East & Africa 4.0 Banking digitization
Total 100.0 —

The Cash Management System Market shows clear regional concentration, with North America and Europe together holding the majority of revenue, while Asia-Pacific drives incremental growth.


North America

Country Share of Region (%) Key Driver
US 82.0 FedNow adoption
Canada 12.5 Real-time Rail launch
Mexico 5.5 SPEI modernization


North America anchors the Cash Management System Market on the strength of FedNow's expanding instant-payment footprint and aggressive AI forecasting adoption among large banks. US corporates lead working-capital optimization programs, and Canada's Real-Time Rail rollout reinforces regional treasury cash solutions demand.

Europe

Country Value (USD B) Key Driver
Germany 1.45 Industrial treasury demand
UK 1.30 Open banking maturity
France 0.98 Corporate liquidity focus
Italy 0.62 SME digitization
Spain 0.55 Banking consolidation
Nordic Countries 0.48 Cashless economy leads
Russia 0.30 Domestic payment systems
Rest of Europe 0.22 Cross-border harmonization


Europe's market reflects Basel IV compliance pressure and the world's most mature open-banking regime under PSD2. German and UK corporates lead enterprise cash control investment, while Nordic economies — already near-cashless — push advanced automated cash handling adoption.

Asia-Pacific

Country CAGR (%) Key Driver
China 14.8 Digital yuan rollout
India 16.5 UPI corporate expansion
Japan 9.2 Treasury modernization
South Korea 11.0 Open banking mandate
ASEAN 15.2 Cross-border QR linkage
Rest of Asia-Pacific 12.0 Banking digitization


Asia-Pacific is the growth engine of the Cash Management System Market, led by India's extension of UPI rails into corporate payments and China's digital yuan pilots. ASEAN's cross-border QR payment linkages create fresh demand for interoperable cash flow management tools.

South America

Country Share of Region (%) Key Driver
Brazil 62.0 Pix instant payments
Argentina 18.5 Inflation-driven cash control
Rest of South America 19.5 Banking digitization


South America's expansion rides on Brazil's Pix, one of the world's most successful instant-payment schemes, which has normalized real-time settlement and pushed corporates toward modern treasury cash solutions. Argentina's high-inflation environment intensifies the need for tight enterprise cash control.

Middle East & Africa

Country Value (USD B) Key Driver
Saudi Arabia 0.28 Vision 2030 fintech push
UAE 0.26 Banking innovation hub
South Africa 0.18 PayShap real-time rails
Egypt 0.10 Financial inclusion drive
Rest of MEA 0.05 Gradual digitization


The Middle East & Africa region is small but accelerating. Saudi Arabia's Vision 2030 fintech agenda and the UAE's role as a regional banking hub drive automated cash handling uptake, while South Africa's PayShap rails extend real-time capability across the continent.

Cash Management System Market By Region, 2025-2035
 

Cash Management System Market Segmentation

By Component

The Cash Management System Market splits cleanly between solutions and the services that deploy them.

Segment 2025 Share (%) Primary Demand Driver
Solution 66.5 Platform standardization
Services 33.5 Implementation and support


Solutions dominate as corporates prioritize core platform capability, while services grow faster as complex integrations demand specialist consulting. The services tier benefits directly from the integration challenges that slow some enterprise cash control rollouts.

By Organization Size

Segment CAGR (%) Primary Demand Driver
Large Enterprises 6.1 Multi-entity complexity
SMEs 14.8 Affordable cloud tooling


Large enterprises hold the revenue majority, but SMEs are the growth story — falling cloud prices put credible cash flow management tools within reach of lean finance teams for the first time.

By Deployment Mode

Segment 2025 Share (%) Primary Demand Driver
Cloud 67.0 Lower IT overhead
On-Premise 33.0 Data sovereignty needs


Cloud deployment leads decisively and continues to gain share as vendors retire on-premise roadmaps. On-premise persists mainly where data-residency rules or security policy require local control.

By Operation Type

Segment 2025 Share (%) Primary Demand Driver
Cash-Flow Forecasting 35.0 AI accuracy gains
Corporate Liquidity Management 29.5 Basel IV pressure
Receivables & Payables 21.0 Working-capital focus
Other Operations 14.5 Niche workflows


Cash-flow forecasting is the largest and fastest-expanding operation type as AI lifts accuracy. Corporate liquidity management follows, propelled by regulatory stress-testing demands.

By End-User Industry

Segment Value (USD B) Primary Demand Driver
BFSI 5.90 Regulatory compliance
IT & Telecom 3.85 Multi-currency operations
Retail & E-commerce 3.40 Transaction volume
Manufacturing 3.10 Supply-chain finance
Others 5.60 Broad digitization


BFSI remains the anchor vertical given its regulatory burden and cash intensity. Retail and e-commerce grow fastest as transaction volumes and omnichannel payments demand sharper cash visibility.


Competitive Benchmarking

The Cash Management System Market is moderately concentrated with an estimated HHI in the 900 - 1,200 range. The top five vendors together account for between 38–44% of sales, with a lengthy tail of regional and niche specialists. The competition is not only on pricing but on interoperability, AI capability and depth of bank connectivity.

Company Est. Revenue Share Range Key Offerings for Cash Management System Market Strategic Positioning
Oracle ~9–12% Treasury and cash modules in the ERP suite Enterprise incumbent
FIS ~8–11% Banking and treasury cash platforms Bank-channel leader
SAP ~7–10% Integrated treasury management ERP-embedded reach
Fiserv ~6–9% Cash and payments solutions Financial institution focus
Kyriba ~5–8% Cloud treasury and liquidity platform Cloud-native specialist
ACI Worldwide ~4–6% Real-time payments and cash tools Payments infrastructure
Nomentia ~3–5% European treasury and cash platform Regional cloud player
Bottomline Technologies ~3–5% Payment and cash management software Mid-market specialist
GTreasury ~2–4% Treasury and risk management platform Integration-focused vendor
Coupa ~2–4% Spend and cash flow management tools Source-to-pay adjacency


Revenue share ranges are MRFR estimates and are not intended to sum precisely. Source: MRFR analysis, 2026.


Recent News & Developments

  • Kyriba (March 2025): Launched an expanded AI forecasting suite, sharpening cash flow management tools' accuracy for multi-entity corporates.
  • FIS (November 2024): Announced enhanced ISO 20022 connectivity across its treasury platform, easing real-time payment adoption for bank clients.
  • Oracle (September 2024): Released embedded liquidity analytics within Fusion Cloud ERP, strengthening enterprise cash control.
  • SAP (June 2024): Partnered with a major bank to deliver embedded treasury services via banking-as-a-service.
  • Federal Reserve (April 2024): Reported accelerating FedNow participation, expanding the real-time rails underpinning automated cash handling.
  • Nomentia (January 2024): Acquired a complementary payments vendor to broaden its European cash management footprint.
  • ACI Worldwide (October 2023): Launched a real-time cash positioning module aligned with global instant-payment schemes.
  • Bottomline Technologies (May 2023): Introduced fraud-detection enhancements for its cash and payments platform amid rising breach concerns.

Section 12 — Report Scope and Methodology

Parameter Detail
Market Scope Global Cash Management System Market — solutions and services
Study Period 2021–2035
CAGR 7.45% (2026–2035)
Market Size Checkpoints USD 21.85B (2025); USD 23.45B (2026); USD 43.20B (2035)
Fastest Growing Segments SMEs; Cloud deployment; Cash-flow forecasting
Companies Profiled Oracle, FIS, SAP, Fiserv, Kyriba, ACI Worldwide, Nomentia, Bottomline, GTreasury, Coupa
Valuation Currency USD Billion


Section 13 — Detailed Sources and Citations

# Full Citation URL / Source
1 Nomentia, "Treasury Technology Trends 2025," 2025 nomentia.com
2 World Bank, "Global Financial Development Report," 2023 worldbank.org
3 SWIFT, "ISO 20022 Migration Status Update," 2024 swift.com
4 US Federal Reserve, "FedNow Service Adoption Report," 2025 federalreserve.gov
5 Bank for International Settlements, "Fast Payments Tracker," 2024 bis.org
6 Oracle, "Annual Report and Treasury Cloud Brief," 2024 oracle.com
7 MRFR, "Treasury and Cash Management Technology Forecast," 2024 MRFR
8 OECD, "Sustainable Finance and Corporate Treasury," 2025 oecd.org
9 Bank for International Settlements, "Basel IV Implementation Note," 2024 bis.org
10 J.P. Morgan, "Working Capital Index," 2024 jpmorgan.com
11 European Banking Authority, "Open Banking and PSD2 Review," 2024 eba.europa.eu
12 IBM Security, "Cost of a Data Breach Report," 2024 ibm.com
13 MRFR, "Global Treasury Survey," 2024 MRFR
14 MRFR, "Treasury Technology Benchmarking Study," 2024 MRFR
15 MRFR, "The Future of Corporate Treasury," 2024 MRFR
16 Reserve Bank of India, "UPI Statistics and Roadmap," 2025 rbi.org.in
17 Banco Central do Brasil, "Pix Adoption Report," 2024 bcb.gov.br
18 FIS, "Annual Report," 2024 fisglobal.com
19 SAP, "Integrated Report," 2024 sap.com
20 Kyriba, "State of Treasury Report," 2025 kyriba.com
21 EY, "Treasury Operations Benchmarking," 2024 ey.com
22 Aite-Novarica, "Cash Management Technology Landscape," 2024 aite-novarica.com


Section 14 — Frequently Asked Questions

Q1. What should buyers prioritize when evaluating vendors in the Cash Management System Market?

Prioritize bank connectivity breadth, native ISO 20022 support, and proven ERP integration. A vendor with shallow bank coverage forces costly workarounds regardless of interface quality.

Q2. How do cloud and on-premise deployments compare for total cost of ownership?

Cloud lowers upfront capital and shortens deployment, but carries recurring subscription costs that compound over time. On-premise demands heavier IT investment yet may suit firms with strict data-residency rules.

Q3. What integration challenges most often delay implementations in the Cash Management System Market?

Legacy ERP connectivity is the top obstacle, followed by inconsistent bank data formats. Projects stall when middleware must bridge old systems to modern APIs, extending timelines and budgets.

Q4. How is AI changing competitive dynamics among vendors?

AI forecasting accuracy has become a primary differentiator. Vendors with mature machine-learning models win deals on liquidity-prediction performance, pressuring slower incumbents to acquire AI capability.

Q5. What regulatory nuance should procurement teams watch in the Cash Management System Market?

Basel IV liquidity rules phase in unevenly across jurisdictions through 2028. Multinationals should confirm a platform handles regional stress-test reporting differences rather than assuming one-size compliance.

Q6. Are emerging-market deployments riskier than mature-market ones?

Emerging markets offer faster growth but face fragmented banking standards and thinner local support. Buyers should weigh real-time scheme maturity, such as UPI or Pix, before committing.

Q7. What new use cases are expanding beyond traditional treasury functions?

Cash-flow data monetization and embedded treasury are emerging fast. Vendors increasingly turn transaction data into credit-scoring and benchmarking products, opening revenue beyond core software licensing.

Cash Management System Market Report Scope

Parameter Detail
Market Scope Global Cash Management System Market — solutions and services
Study Period 2021–2035
CAGR 7.45% (2026–2035)
Market Size Checkpoints USD 21.85B (2025); USD 23.45B (2026); USD 43.20B (2035)
Fastest Growing Segments SMEs; Cloud deployment; Cash-flow forecasting
Companies Profiled Oracle, FIS, SAP, Fiserv, Kyriba, ACI Worldwide, Nomentia, Bottomline, GTreasury, Coupa
Valuation Currency USD Billion

Preguntas frecuentes

¿Qué deben priorizar los compradores al evaluar proveedores en el mercado de sistemas de gestión de efectivo?

Priorizar la amplitud de conectividad bancaria, el soporte nativo de ISO 20022 y la integración probada con ERP. Un proveedor con cobertura bancaria limitada obliga a costosos trabajos alternativos sin importar la calidad de la interfaz .

¿Cómo se comparan las implementaciones en la nube y en las instalaciones en términos de costo total de propiedad?

La nube reduce el capital inicial y acorta la implementación, pero conlleva costos de suscripción recurrentes que se acumulan con el tiempo. Las instalaciones requieren una inversión de TI más pesada, pero pueden ser adecuadas para empresas con estrictas reglas de residencia de datos .

¿Cuáles son los desafíos de integración que más a menudo retrasan las implementaciones en el mercado de sistemas de gestión de efectivo?

La conectividad de ERP heredado es el principal obstáculo, seguido de formatos de datos bancarios inconsistentes. Los proyectos se estancan cuando el middleware debe conectar sistemas antiguos a API modernas, extendiendo los plazos y presupuestos .

¿Cómo está cambiando la IA las dinámicas competitivas entre proveedores?

La precisión de las previsiones de IA se ha convertido en un diferenciador principal. Los proveedores con modelos de aprendizaje automático maduros ganan contratos basados en el rendimiento de predicción de liquidez, presionando a los incumbentes más lentos a adquirir capacidades de IA .

¿Qué matiz regulatorio deben observar los equipos de adquisiciones en el mercado de sistemas de gestión de efectivo?

Las reglas de liquidez de Basilea IV se implementan de manera desigual en las jurisdicciones hasta 2028. Las multinacionales deben confirmar que una plataforma maneja las diferencias en los informes de pruebas de estrés regionales en lugar de asumir un cumplimiento de talla única .

¿Son más arriesgadas las implementaciones en mercados emergentes que en mercados maduros?

Los mercados emergentes ofrecen un crecimiento más rápido pero enfrentan estándares bancarios fragmentados y un soporte local más limitado. Los compradores deben sopesar la madurez del esquema en tiempo real, como UPI o Pix, antes de comprometerse .

¿Qué nuevos casos de uso están expandiéndose más allá de las funciones tradicionales de tesorería?

La monetización de datos de flujo de efectivo y la tesorería integrada están surgiendo rápidamente. Los proveedores convierten cada vez más los datos de transacciones en productos de puntuación crediticia y benchmarking, abriendo ingresos más allá de la licencia de software central .

Autor
Autor Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach

Research Methodology on Cash Management System Market

1. Introduction:

Market Research Future (MRFR) has initiated an in-depth study of the global cash management system market. The present research document provides a detailed understanding of the cash management system market, with an exhaustive analysis of the market size and market potential for the period of 2023 to 2030 (forecast period). The report aims to offer lucrative insights and attainable growth prospects of the cash management system market. The study further elaborates on the current trends, market opportunities, and driving forces in the cash management system market.

2. Research Objective:

The research objectives for this report on the cash management system market are:

  • To analyze and forecast the market size of the cash management system market globally
  • To offer an in-depth assessment of the market segments
  • To provide a detailed analysis of macro- and micro-economic factors
  • To evaluate the regional market profiles and changes
  • To analyze the changes in demand patterns and pricing structure
  • To offer an extensive analysis of the key players contributing to the market
  • To provide a comprehensive analysis of the major dynamics surrounding the industry

3. Research Methodology:

MRFR’s data-driven approach is used to derive the market size, industry trends, market opportunity, and revenue estimates. For the cash management system market, MRFR has compiled primary and secondary data sources such as industry reports, press releases, annual reports, interviews, and newsletters. The data gathered from primary and secondary sources is further analyzed and processed to obtain qualitative and quantitative insights into the global cash management system market. Primary research is conducted through surveys and interviews with key opinion leaders from the cash management system market. Secondary research involves desk-top research techniques such as literature review.

4. Data Collection:

For the study of the cash management system market, MRFR has conducted a detailed analysis of the market size and market potential for the period of 2023 to 2030 (forecast period). The market sizing procedure involves analyzing historical data of various cash management systems and comparing them with the current market trends. This helps to derive the current market size and deduce future opportunities.

MRFR has adopted a methodical approach to studying the cash management system market. This involves a detailed market understanding of cash management systems - the types, complexities, and industry dynamics. Further, MRFR has conducted extensive primary and secondary research to compile the report. Primary research includes surveys and interviews with key opinion leaders, such as industry experts and business professionals. Secondary research includes sources such as industry reports, press releases, and annual reports.

4. Market Segmentation:

The global cash management system market has been segmented based on type, solution, application, and end user. By type, the market has been segmented into automated teller machines (ATMs), point-of-sale (POS) systems, cash-in-transit (CTI), and others. By solution, the market has been segmented into cash management solutions, cash flow management solutions, currency management solutions, and others. By application, the market has been segmented into banking, retail, healthcare, and others. By end user, the market has been segmented into retail, hospitality, BFSI, and others.

5. Regional Analysis:

The global cash management system market has been studied across five regions, namely, North America, Europe, Asia-Pacific (APAC), Middle East & Africa (MEA), and South America. North America is dominating the global cash management system market. The growth of the cash management system market in North America is due to the presence of leading IT companies, increasing adoption of cash management systems, massive investments in machine learning and artificial intelligence (AI) technology, implementation of cutting-edge technologies, and increasing focus on data analytics.

Europe is the second-largest market for cash management systems, after North America. The steady growth of the European cash management system market can be attributed to the introduction of innovative and advanced cash management systems, increasing government initiatives, and rising investments in research & development (R&D) activities.

Furthermore, the market in APAC is expected to witness growth at the highest CAGR during the forecast period. The growth in the APAC region is due to increasing demand for cash management systems in the banking and retail sectors, implementation of cash management systems by small and medium-sized enterprises (SMEs), and rising investments in digital technologies.

6. Competitive Analysis:

The competitive analysis section of the report provides a detailed analysis of the key players operating in the global cash management system market. The players have been studied based on their product offerings, business strategies, recent developments, and financials. The market potential of all the leading players has been extensively studied in the report and provides an adequate data set for risk analysis. Moreover, the players have been studied based on their respective strengths and weaknesses in the market.

The prominent players in the global cash management system market are BEAMEX AG (Switzerland), Tieto Oyj (Finland), CashGuard Oy (Finland), Diebold Nixdorf (US), RDM Corporation (Canada), Giesecke and Devrient GmbH (Germany), NCR Corporation (US), Sampi Secure Oy (Finland), Wincor Nixdorf (Germany), Nautilus Hyosung Corporation (South Korea), Bally Technologies (US), Diebold (US), Tidel Engineering LP (US), Glory Global Solutions (UK), and CPI Card Group Inc. (US).

Descargar muestra gratis

Complete el formulario a continuación para recibir una muestra gratuita de este informe

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















