Vitrectomy Devices Market (2026 - 2035)

Vitrectomy Devices Market Research Report By Product Type (Vitrectomy Systems, Illuminators, Cutting Devices, Fluid Management Devices), By End User (Hospitals, Ambulatory Surgical Centers, Ophthalmology Clinics), By Application (Retinal Detachment Repair, Vitrectomy for Macular Hole, Diabetic Retinopathy, Vitreous Hemorrhage), By Usage (Initial Procedure, Follow-Up Procedure, Reoperation Procedure) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035
ID: MRFR/HC/9251-HCR 120 Pages Rahul Gotadki, Satyendra Maurya Last Updated: September 15, 2026
Vitrectomy Devices Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.10%
2025 Market SizeUSD 1.90 Billion
2035 Market SizeUSD 3.44 Billion
Key Players
Alcon
Bausch + Lomb
Carl Zeiss Meditec
Johnson & Johnson Vision
D.O.R.C.
Topcon Healthcare
Opportunities
  • Disposables-Led Razor-and-Blade Economics
  • Portable Platforms for Emerging Geographies
  • Surgical Data and Outcome Analytics

Vitrectomy Devices Market Summary

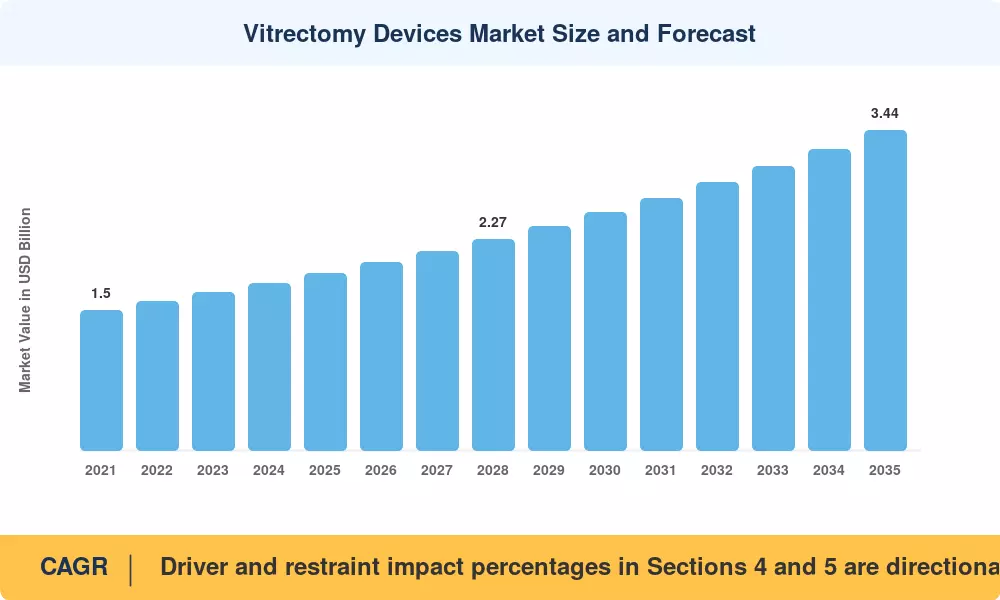
The Vitrectomy Devices Market was valued at USD 1.90 billion in 2025 and is projected to grow to USD 3.44 billion by 2035, expanding at a compound annual growth rate (CAGR) of 6.10% between 2026 and 2035. Market value is expected to reach USD 2.02 billion in 2026 as the first year of the forecast period. This growth is being driven primarily by stable U.S. reimbursement for complex retinal procedures and a large, growing global diabetic population, alongside a broader shift toward smaller-gauge, higher-speed surgical platforms.

In the United States, the Centers for Medicare & Medicaid Services (CMS) has held facility payment for complex posterior-segment procedures broadly intact through the 2025 Outpatient Prospective Payment System (OPPS) cycle. This reimbursement stability protects the economics of high-acuity retina work and supports continued investment in vitrectomy equipment by surgical centers. At the same time, the International Diabetes Federation counts 589 million adults living with diabetes in 2024, a population that feeds directly into retinal surgical volume, since diabetic retinopathy remains a leading driver of vitrectomy procedures.

Technology is also reshaping the installed base of vitrectomy equipment. Legacy 20-gauge consoles with pneumatic guillotine cutters are being replaced by 25- and 27-gauge platforms featuring dual-pneumatic and hypersonic cutting at 15,000 to 20,000 cuts per minute, along with integrated endoillumination and digitally assisted visualization. Alcon, Bausch + Lomb, and Carl Zeiss Meditec jointly invested more than USD 4.1 billion into research and development across their surgical businesses in fiscal year 2024, with a significant portion of that spending directed toward console update cycles expected to define the Vitrectomy Devices Market through 2030.

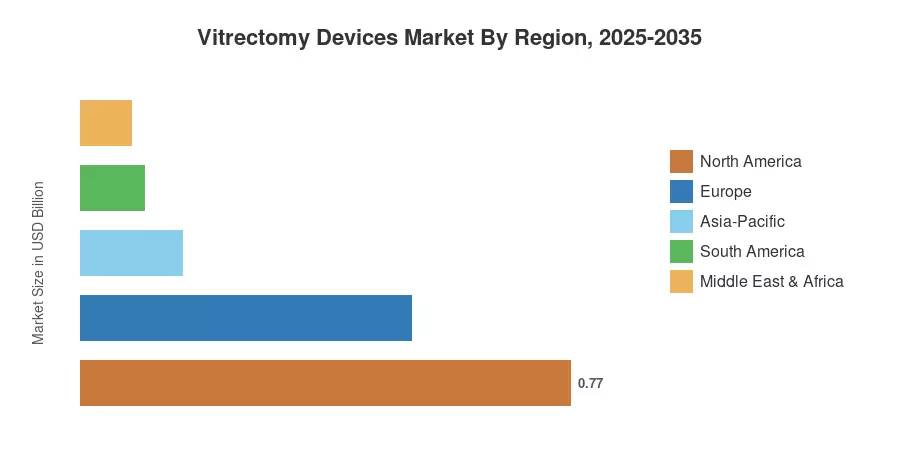
By region, North America holds the largest share of the Vitrectomy Devices Market, at 40.4% of 2025 revenue, driven by a high density of retina specialist networks and continued migration toward ambulatory surgical settings. Asia-Pacific is the fastest-growing region, with a projected CAGR of 8.2% through 2035, as China, India, and Japan expand tertiary eye-care capacity. Europe holds the second-largest position, where the Medical Device Regulation (MDR) has delayed certain new product launches but has strengthened the position of incumbents with already-authorized portfolios. As consoles become increasingly commoditized, the Vitrectomy Devices Market is expected to steadily shift toward disposables-led revenue.

Key Report Takeaways

• By Product Type

  • Vitrectomy packs led the Vitrectomy Devices Market with a 33.0% revenue share in 2025, reflecting per-procedure consumable pull-through.
  • Vitrectomy systems are forecast to expand at a 7.4% CAGR through 2035 as hypersonic and dual-pneumatic consoles displace older platforms.
  • Photocoagulation lasers contributed roughly USD 0.26 Billion in 2025 revenue, supported by combined laser-and-cutter procedure protocols.

• By Application

  • Diabetic retinopathy accounted for 42.7% of Vitrectomy Devices Market revenue in 2025, the single largest procedural pool
  • Macular hole repair is the fastest-advancing application at an 8.0% CAGR to 2035


  • End User


  • Ophthalmology clinics are growing at a 7.0% CAGR as case mix shifts out of inpatient theatres.

• By Region

  • North America commanded 40.4% of global revenue in 2025
  • Asia-Pacific is the fastest-growing region at an 8.2% CAGR through 2035
  • Europe generated approximately USD 0.52 Billion in 2025


Market Size and Forecast (2021–2035)

Estimates blend bottom-up procedure modelling — national retina case volumes cross-checked against Medicare claims, NHS Hospital Episode Statistics and Japan MHLW procedure registries — with top-down triangulation from surgical-segment disclosures in listed ophthalmic manufacturers' annual filings [11][12][13][14]. Console shipments are modelled separately from consumable attach rates, then reconciled to reported revenue.
Vitrectomy Devices Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising diabetic retinopathy prevalence ~1.6% Global Long-term (≥4 yr)
Population ageing and vitreomacular disease ~1.2% North America, Europe, Japan Long-term (≥4 yr)
Migration of cases to ambulatory settings ~0.9% North America, Europe Medium-term (2–4 yr)
Small-gauge and hypersonic cutter adoption ~0.8% Global Medium-term (2–4 yr)
Stable procedural reimbursement ~0.6% North America, Western Europe Short-term (≤2 yr)
Public eye-care capacity programmes ~0.5% Asia-Pacific, Middle East Long-term (≥4 yr)
Digitally assisted 3D visualisation uptake ~0.4% Global Short-term (≤2 yr)


Diabetic Retinopathy Volume Is the Structural Engine

Diabetes is the demand floor beneath the Vitrectomy Devices Market. The International Diabetes Federation projects the adult diabetic population reaching 853 million by 2050, with roughly one in three developing some grade of retinopathy [1]. The US National Eye Institute estimates that vision-threatening diabetic retinopathy affects about 1.84% of American adults over 40 [2]. Proliferative disease that fails anti-VEGF control converts into surgical referral, and each conversion pulls a full disposable pack alongside console time.

Ambulatory Migration Reshapes Purchasing

Site-of-service shift has changed who signs the purchase order. CMS added several posterior-segment codes to the ASC covered-procedures list across recent rulemaking cycles, and ambulatory centres now capture a meaningful slice of US retina volume [3]. Centres buying their own consoles favour compact, fast-boot platforms with predictable consumable pricing over flagship theatre systems, which compresses average selling prices while lifting unit counts.

Instrumentation Miniaturisation Widens the Performance Gap

Cutters running at 20,000 cuts per minute through 27-gauge ports reduce vitreous traction and shorten operative time, with published series reporting meaningful reductions in mean surgical duration versus 23-gauge benchmarks [15]. Manufacturers have converted that clinical margin into premium pricing. Small-gauge instrumentation now anchors the flagship tier of nearly every major vendor catalogue [11][12][14].

Visualisation Convergence

Heads-up 3D digital viewing systems, intraoperative OCT and integrated laser modules are collapsing into single-vendor ecosystems. Carl Zeiss Meditec and Alcon both market console-plus-visualisation bundles that lock consumable choice for the equipment's operating life [11][13], lifting attach rates by an estimated 12–15% over standalone console sales.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Anti-VEGF therapy deferring surgical referral ~-1.1% North America, Europe Long-term (≥4 yr)
High console capital cost ~-0.7% Asia-Pacific, Africa, South America Medium-term (2–4 yr)
Retina surgeon shortage ~-0.6% Global Long-term (≥4 yr)
EU MDR recertification burden ~-0.4% Europe Short-term (≤2 yr)
Reprocessed instrument price pressure ~-0.3% North America Medium-term (2–4 yr)


Pharmacology Competes With the Scalpel

Intravitreal anti-VEGF therapy has genuinely deferred surgery for a subset of diabetic and vein-occlusion patients. Medicare Part B spending on ophthalmic biologics has run into the billions annually, and Protocol S long-term data showed ranibizumab non-inferior to panretinal photocoagulation for proliferative diabetic retinopathy at five years [16]. Every well-controlled patient is a postponed vitrectomy.

Capital Intensity Blocks Emerging Adoption

Flagship consoles carry list prices between USD 90,000 and USD 160,000 before consumables. For district hospitals in South Asia, Sub-Saharan Africa and much of South America, that outlay competes against cataract throughput equipment with far shorter payback. World Bank health-expenditure data shows several high-burden countries spending under 4% of GDP on health, which caps tertiary capital budgets [7].

Workforce Is the Hard Ceiling

Consoles do not operate themselves. The American Academy of Ophthalmology and comparable European bodies report retina fellowship output growing more slowly than the ageing patient pool, leaving many regional centres with a single vitreoretinal surgeon [17]. Utilisation, not equipment availability, becomes the binding constraint.


Vitrectomy Devices Market Opportunities

Disposables-Led Razor-and-Blade Economics

The most durable margin pool in the Vitrectomy Devices Market sits in the pack, not the console. Vendors placing consoles at subsidised or zero capital cost against multi-year consumable commitments convert lumpy capital cycles into annuity revenue. Packs already hold the largest product-type share, and the model travels well into ASC and clinic channels.

Portable Platforms for Emerging Geographies

Compact systems weighing under 20 kg, running on single-phase power with integrated pneumatics, open district-hospital demand across India, ASEAN and Sub-Saharan Africa. India's Ayushman Bharat scheme has expanded tertiary procedure coverage to hundreds of millions of beneficiaries [8], creating volume that a USD 35,000–50,000 platform can economically serve where a flagship cannot.

Surgical Data and Outcome Analytics

Connected consoles generate cut-rate profiles, vacuum curves, fluidics logs and case duration for every procedure. Vendors are beginning to license de-identified benchmarking dashboards back to hospital groups as subscription analytics — a business model with software-grade margins layered onto hardware already installed. Early offerings price at USD 4,000–9,000 per console annually [13].

Combination Procedure Bundles

Cataract-plus-vitrectomy combined cases are rising with an ageing patient mix, and vendors able to supply both phaco and posterior platforms on shared fluidics capture double consumable pull-through. This is where scale players hold a structural edge over specialists in the Vitrectomy Devices Market.

Regulatory Fast Lanes

The FDA's Breakthrough Devices and Safer Technologies programmes have shortened review timelines for qualifying ophthalmic devices, while Japan's PMDA Sakigake pathway offers a parallel route [5][9]. Vendors sequencing filings across both jurisdictions can compress global launch by 12–18 months.


Vitrectomy Devices Market Future Outlook

Machine Vision Enters the Operating Field

Software-assisted membrane detection and automated fluidics compensation will move from research to commercial release within the decade. Intraoperative OCT already guides membrane peeling in premium theatres, and vendors are training models on the case libraries their connected consoles generate. Expect the first regulatory-cleared decision-support module in the Vitrectomy Devices Market before 2029, priced as a console subscription rather than hardware.

Platform Economics Beat Hardware Margins

Console list prices will keep compressing as Chinese and Indian manufacturers reach clinical parity on mid-tier specifications. Vendors will defend profit by binding consumables, service contracts and analytics into multi-year agreements. By 2035, recurring revenue should account for well over two-thirds of category revenue, up from roughly 58% today.

Ambulatory Becomes the Default Setting

Site-of-service shift has further to run. If ASC penetration of eligible retina cases in the United States climbs from current levels toward cataract-like rates, unit demand for compact consoles could double independent of procedure growth [3]. European ambulatory tariff reform in France and Germany points the same direction.

Sustainability Reshapes the Disposable Pack

Single-use packs generate substantial operating-theatre waste, and NHS England's net-zero supplier roadmap now requires carbon reduction plans from device suppliers [10]. Hybrid packs pairing reusable handpieces with single-use cassettes are the likely compromise. Procurement scoring on embodied carbon will become a genuine tender differentiator in the Vitrectomy Devices Market by the early 2030s.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 40.4% share ASC channel build-out, premium console refresh
Europe 27.2% share MDR-compliant portfolio consolidation
Asia-Pacific 8.2% CAGR (2026–2035) Tertiary eye-care capacity, portable platforms
South America USD 0.10 Billion Public-hospital tenders, distributor networks
Middle East & Africa 4.4% share Sovereign health programmes, surgeon training
Total USD 1.90 Billion

Geographic concentration in the Vitrectomy Devices Market remains high, with North America and Europe together holding roughly two-thirds of 2025 revenue while Asia-Pacific supplies most incremental growth.


North America

Country Share of Region (2025) Key Driver
US 86.5% Dense retina-specialist network and ASC migration
Canada 8.9% Provincial cataract-and-retina backlog funding
Mexico 4.6% Private hospital chain expansion


American dominance in the Vitrectomy Devices Market rests on procedure density rather than population. More than 2,000 practising vitreoretinal surgeons operate across roughly 6,000 ambulatory surgery centres and hospital outpatient departments, and CMS payment stability through the 2025 OPPS cycle has kept complex retina work economically viable in both settings [3][17]. Canadian demand tracks provincial wait-list funding, which has run in the hundreds of millions of Canadian dollars since 2023. Mexico's growth is private-pay led, concentrated in Monterrey, Guadalajara and Mexico City.

Europe

Country Share of Region (2025) Key Driver
Germany 24.1% Highest per-capita retina procedure volume in the bloc
UK 17.3% NHS elective recovery funding
France 15.2% Ambulatory tariff reform
Italy 11.4% Regional tender consolidation
Spain 9.6% Private clinic network growth
Nordic Countries 7.8% Early adoption of 3D visualisation
Russia 6.2% Domestic manufacturing substitution
Rest of Europe 8.4% Central European capacity upgrades


Regulation defines the European picture. The Medical Device Regulation raised clinical-evidence and post-market surveillance obligations sharply, and MedTech Europe has documented notified-body capacity constraints that delayed recertification for numerous legacy Class IIb devices [6]—incumbents with completed dossiers gained share by default. NHS England's elective recovery programme, funded at multi-billion-pound scale, has been the single largest volume unlock in the region since 2023 [10].

Asia-Pacific

Country Metric (2026–2035) Key Driver
China 9.1% CAGR Provincial tertiary hospital expansion
India 9.6% CAGR Ayushman Bharat coverage and private chains
Japan 4.8% CAGR Highest-in-region ageing population
South Korea 6.4% CAGR Premium console adoption
ASEAN 8.3% CAGR Medical tourism hubs in Thailand and Singapore
Rest of Asia-Pacific 6.9% CAGR Donor-funded blindness-prevention programmes


Asia-Pacific supplies the steepest growth curve in the Vitrectomy Devices Market because disease burden and capacity investment are rising together. China's NMPA has accelerated domestic device approvals under its innovation pathway, and provincial volume-based procurement has pushed pricing down while expanding unit placement [18]. India adds roughly 77 million diabetic adults to the addressable pool [1], with large private chains such as Aravind and Dr. Agarwal's operating high-throughput retina theatres. Japan's demand is ageing-driven rather than incidence-driven.

South America

Country Share of Region (2025) Key Driver
Brazil 58.4% SUS public procurement and private hospital growth
Argentina 17.1% Urban ophthalmology clinic density
Rest of South America 24.5% Chile and Colombia capacity additions


Brazilian tenders set the regional tone. ANVISA registration timelines and the Unified Health System's centralised purchasing mean vendors compete on total cost per case rather than console specification [20]. Currency volatility remains the sharpest commercial risk, pushing several manufacturers toward local distributor partnerships with real-denominated pricing. Argentine demand concentrates almost entirely in Buenos Aires private clinics.

Middle East & Africa

Country Share of Region (2025) Key Driver
Saudi Arabia 31.2% Vision 2030 health-sector transformation
UAE 22.6% Medical tourism and private hospital investment
South Africa 18.4% Private-sector retina capability
Egypt 12.1% High diabetes prevalence, public eye programmes
Rest of MEA 15.7% Donor and NGO-funded surgical capacity


Sovereign programmes drive the region. Saudi Arabia's Health Sector Transformation Programme under Vision 2030 has committed substantial capital to specialist hospital construction, with ophthalmology among the prioritised service lines [19]. Egypt carries one of the world's highest diabetes prevalence rates among adults. Yet, retina surgical capacity lags badly — a gap that portable platforms and surgeon-training partnerships are beginning to address.


Vitrectomy Devices Market By Region, 2025-2035

Vitrectomy Devices Market Segmentation

Segment structure in the Vitrectomy Devices Market follows the taxonomy used across the vitreoretinal surgical category: product type, application and end user.

By Product Type

Product-type dynamics in the Vitrectomy Devices Market split cleanly between annuity consumables and cyclical capital equipment.

Segment Metric (2025) Primary Demand Driver
Vitrectomy Packs 33.0% share Per-procedure consumption tied to case volume
Vitrectomy Systems 7.4% CAGR (2026–2035) Console refresh toward hypersonic cutting
Instruments 18.6% share Forceps, scissors and light-pipe replacement cycles
Photocoagulation Lasers USD 0.26 Billion Combined laser-and-cutter protocols
Other Product Types 6.5% share Tamponade agents, accessories


Packs dominate because they scale with procedures rather than purchase decisions. Every case consumes a cutter, cassette, tubing set and infusion line, and vendors design port geometry so that third-party substitution carries clinical risk. Systems grow faster in percentage terms because the installed base is mid-cycle: platforms placed between 2014 and 2018 are reaching end of service life, and replacement buyers are skipping straight to 27-gauge hypersonic capability rather than upgrading incrementally.

By Application

Application mix in the Vitrectomy Devices Market maps directly onto retinal disease epidemiology.

Segment Metric (2025) Primary Demand Driver
Diabetic Retinopathy 42.7% share Global diabetes prevalence [1]
Retinal Detachment 26.9% share Trauma, myopia and post-cataract incidence
Macular Hole 8.0% CAGR (2026–2035) OCT-driven earlier diagnosis
Other Applications 14.6% share Endophthalmitis, dislocated lens, vitreous haemorrhage


Diabetic cases carry longer operative times and higher consumable intensity than routine detachment repair, which is why their revenue share exceeds their procedure share. Macular hole leads on growth because widespread OCT screening in optometric practice now catches stage 2 holes that previously progressed undetected — earlier detection converts directly into more surgical candidates with better anatomical outcomes.

By End User

End-user structure in the Vitrectomy Devices Market is shifting faster than any other dimension.

Segment Metric (2025) Primary Demand Driver
Hospitals 63.8% share Complex and emergency case referral
Ophthalmology Clinics 7.0% CAGR (2026–2035) Routine case migration and physician ownership
Ambulatory Surgical Centers USD 0.23 Billion Reimbursement parity for eligible codes [3]


Hospitals retain the majority because trauma, endophthalmitis and combined anterior-posterior cases need anaesthesia backup and inpatient escalation paths. Clinics take the routine tail — macular pucker, uncomplicated macular hole, vitreous floaters — where physician ownership aligns incentives toward throughput and lower-cost consoles.


Competitive Benchmarking

Concentration in the Vitrectomy Devices Market is high. Market Research Future estimates a Herfindahl-Hirschman Index in the 1,750–1,950 range, with the top five suppliers holding an estimated 72–78% of global revenue. The structure is best described as a tight oligopoly at the premium tier, ringed by specialist instrument makers and regional challengers competing on price and service responsiveness rather than platform breadth.

Company Est. Revenue Share Range Key Offerings for Vitrectomy Devices Market Strategic Positioning
Alcon ~26–30% Constellation Vision System, Hypervit dual-blade probes, Grieshaber instruments Category leader; deepest consumable ecosystem
Bausch + Lomb ~13–16% Stellaris Elite platform, Vitesse hypersonic technology Differentiated cutting mechanism; strong ASC channel
Carl Zeiss Meditec ~10–13% QUATERA and visualisation-integrated suites, RESIGHT viewing Visualisation-plus-console bundling
Johnson & Johnson Vision ~6–9% Posterior segment instrumentation, combined cataract-retina portfolio Scale advantage in combined procedures
D.O.R.C. (Dutch Ophthalmic) ~5–8% EVA NEXUS platform, VacuFlow VTi fluidics Specialist innovator; strong European base
Topcon Healthcare ~3–5% Surgical consoles, integrated imaging Imaging-to-surgery continuum
NIDEK ~3–5% Fortas vitrectomy system, photocoagulation lasers Asia-Pacific strength; laser crossover
Oertli Instrumente ~2–4% OS 4 platform, Continuous Flow Cutter Premium Swiss engineering niche
HOYA Surgical Optics ~2–4% Illumination systems, single-use instrumentation Disposables-first model
MedOne Surgical ~1–3% Micro-instrumentation, backflush handpieces Universal-fit accessory specialist
IRIDEX ~1–3% Endophotocoagulation laser systems Laser pure-play
Lumenis Vision ~1–2% Photocoagulation platforms Retina laser adjacency


Recent News & Developments

  • Bausch + Lomb (March 2023): Expanded Vitesse hypersonic vitrectomy availability across additional European markets, broadening the only non-guillotine cutting mechanism in mainstream clinical use [12]
  • Alcon (September 2023): Rolled out Hypervit 27+ dual-blade probe compatibility on the Constellation platform, lifting effective cut rate toward 20,000 cpm and reinforcing consumable lock-in [11]
  • Carl Zeiss Meditec (May 2024): Integrated intraoperative OCT guidance across its digital visualisation portfolio for posterior-segment procedures, tightening the imaging-to-surgery loop [13]
  • D.O.R.C. (July 2024): Announced completion of its acquisition by Carl Zeiss Meditec, consolidating two of the five largest console franchises and reshaping European supply dynamics [13]
  • FDA (November 2024): Cleared additional 27-gauge instrumentation under the 510(k) pathway with predicate reliance, shortening time-to-market for small-gauge accessories [5]
  • NIDEK (February 2025): Introduced updated Fortas console configurations targeting ambulatory and clinic buyers across ASEAN and India [14]
  • CMS (December 2024): Finalised CY2025 OPPS and ASC payment rules maintaining facility rates for major posterior-segment codes, preserving ambulatory case economics [3]
  • MedTech Europe (June 2025): Published updated analysis on notified-body throughput under MDR, confirming continued recertification backlogs affecting legacy ophthalmic device families [6]


Vitrectomy Devices Market Report Scope

Parameter Detail
Market Scope Global vitrectomy systems, packs, instruments, photocoagulation lasers and related consumables across hospitals, ophthalmology clinics and ambulatory surgical centres
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.10% (2026–2035)
Market Size Checkpoints USD 1.90 Billion (2025); USD 2.02 Billion (2026); USD 2.71 Billion (2031); USD 3.44 Billion (2035)
Fastest Growing Segments Vitrectomy Systems (product type); Macular Hole (application); Ophthalmology Clinics (end user); Asia-Pacific (geography)
Companies Profiled Alcon, Bausch + Lomb, Carl Zeiss Meditec, Johnson & Johnson Vision, D.O.R.C., Topcon Healthcare, NIDEK, Oertli Instrumente, HOYA Surgical Optics, MedOne Surgical, IRIDEX, Lumenis Vision
Valuation Currency USD Billion, constant 2025 exchange rates
CAGR Driver Disclaimer Driver and restraint impact percentages in Sections 4 and 5 are directional analyst weightings, not additive components of the headline CAGR.

FAQs

What contract structures should hospitals negotiate when buying into the Vitrectomy Devices Market?
Push for consumable price caps indexed to inflation across the full console life, not just year one. Bundle service, software updates and probe pricing into a single multi-year agreement. Unbundled deals routinely cost 20–30% more over seven years [11].
How does hypersonic cutting differ from guillotine cutting technically?
Guillotine cutters use a reciprocating blade; hypersonic systems liquefy vitreous through ultrasonic port vibration with a continuously open aperture. The result is steadier flow and less pulsatile traction. Clinical superiority remains debated rather than settled [12].
Are third-party consumables viable in the Vitrectomy Devices Market?
Universal-fit instruments from specialists like MedOne work reliably for forceps and backflush handpieces. Cutters and cassettes are effectively proprietary — port geometry and fluidics calibration make substitution clinically risky and often warranty-voiding [11].
What is the realistic payback period on an ambulatory surgery centre console?
At 200–300 retina cases annually with facility reimbursement intact, a USD 100,000 console typically pays back in 30–42 months. Below 150 cases, shared-use or per-case placement models make better financial sense [3].
How should buyers evaluate cybersecurity in the Vitrectomy Devices Market?
Request a software bill of materials and confirm the vendor supports FDA premarket cybersecurity expectations for connected devices. Networked consoles pushing case data to cloud dashboards need documented patch commitments through end of service life [5].
Does tariff exposure meaningfully affect console pricing?
Yes for Asia-manufactured mid-tier systems, where duties can add 5–12% to landed cost. Premium platforms from Switzerland, Germany and the United States are less exposed but carry currency risk instead [20].
What training investment does a new 27-gauge programme require?
Budget 15–25 wet-lab and proctored cases per surgeon before independent small-gauge operating. Most vendors bundle initial training, but ongoing fellow education is usually chargeable at USD 8,000–15,000 annually [17].    
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















