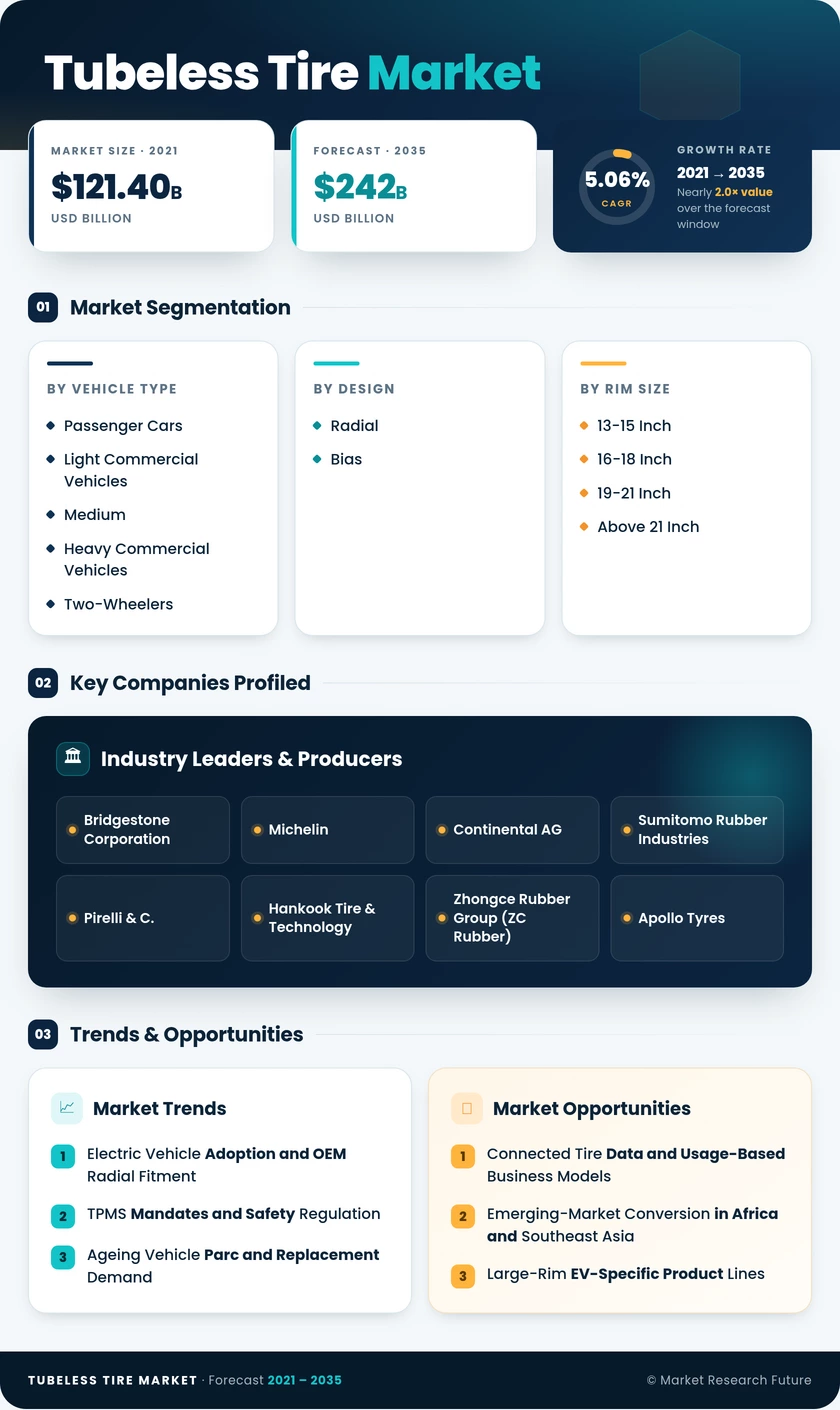
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Vehicle Type | Passenger Cars, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles, Two-Wheelers | Passenger Cars (51.2% share) | Light Commercial Vehicles (5.1% CAGR) |
| By Design | Radial, Bias | Radial (92.5% share) | Radial (92.5% share; grows faster than Bias) |
| By Rim Size | 13-15 Inch, 16-18 Inch, 19-21 Inch, Above 21 Inch | 16-18 Inch (44.9% share) | Above 21 Inch (5.3% CAGR) |
| By Sales Channel | OEMs, Aftermarket | Aftermarket (71.8% share) | OEMs (5.2% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific (42.3% share) | South America (5.2% CAGR) |
Market Segmentation Overview
The segmentation below summarises the key trends behind each dimension of the Tubeless Tire Market.
By Vehicle Type
| Sub-Segment | Key Trend |
|---|---|
| Passenger Cars | Rim upsizing during replacement and EV-specific fitments |
| Light Commercial Vehicles | Delivery fleets specifying tubeless radials with TPMS |
| Medium and Heavy Commercial Vehicles | Bias-to-radial shift and retreadable casings |
| Two-Wheelers | Alloy rims replacing spoked wheels on commuter models |
Passenger Cars lead this dimension because replacement volumes from a record-age vehicle parc dwarf every other category. Light Commercial Vehicles grow fastest, as delivery operators weigh the cost of a stranded van far above a modest tire premium. Two-Wheelers add a long conversion runway in India and ASEAN, where factory tubeless fitment is now the norm.
By Design
| Sub-Segment | Key Trend |
|---|---|
| Radial | Higher load indices, silica treads, and aramid reinforcement for EVs |
| Bias | Retained in mining, forestry, and agricultural machinery |
Radial dominates and also grows faster than Bias because OEMs have standardised on it for rolling resistance and heat dissipation. Bias holds value only where sidewall flex and cut resistance outweigh speed, such as quarry and forestry equipment. New vehicle programs in emerging economies increasingly skip bias construction altogether.
By Rim Size
| Sub-Segment | Key Trend |
|---|---|
| 13-15 Inch | Compact cars in price-sensitive markets |
| 16-18 Inch | Mainstream crossovers and compact SUVs |
| 19-21 Inch | Mid-cycle refreshes on mid-size SUVs |
| Above 21 Inch | Luxury SUVs and premium EVs |
The 16-18 Inch class leads because it matches the volume crossover segment worldwide. Above 21 Inch grows fastest, driven by luxury and EV buyers for whom wheel size is part of the vehicle's appeal, and its high price points lift margins. The 13-15 Inch band remains a volume base in markets where compact hatchbacks still dominate sales.
By Sales Channel
| Sub-Segment | Key Trend |
|---|---|
| OEMs | Factory-fitted tubeless radials bundled with TPMS and sensor suites |
| Aftermarket | Replacement demand, private-label lines, and counterfeit enforcement |
The Aftermarket leads because each vehicle consumes multiple replacement sets during its service life. OEMs grow faster as automakers integrate tire sensors with ADAS and use dealer alerts to pull owners back to OE-approved replacements. Independent retailers defend share with private labels while regulators tighten checks on low-cost imports.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA