Train Battery Market (2026 - 2035)

Train Battery Market Research Report By Battery Type (Lithium-ion (LFP/NMC), Nickel-Cadmium, Lead-Acid, Lithium Titanate, Others), By Application (Auxiliary and Onboard Power, Traction and Propulsion, Starter and Cranking, Emergency and Backup), By Rolling Stock Type (Electric and Battery Multiple Units, Diesel Locomotives, Metro and Light Rail, Passenger Coaches, Freight Wagons and Specialty Vehicles), By Sales Channel (OEM, Aftermarket) - Forecast to 2035
ID: MRFR/AT/39258-HCR 100 Pages Abbas Raut, Swapnil Palwe Last Updated: September 08, 2026
Train Battery Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.9%
2025 Market SizeUSD 0.42 Billion
2035 Market SizeUSD 0.99 Billion
Key Players
Saft
EnerSys
Hoppecke Batterien
Toshiba Corporation
GS Yuasa
Exide Industries
Opportunities
  • Second-Life and Stationary Buffer Systems
  • Emerging-Market Metro Build-Outs
  • Battery Health Analytics as a Revenue Line

Train Battery Market Summary

The Train Battery Market reached USD 0.42 billion in 2025 and opens the forecast window at USD 0.46 billion in 2026, climbing to USD 0.99 billion by 2035 at an 8.9% CAGR. Two catalysts anchor that trajectory. The European Union's Connecting Europe Facility committed roughly EUR 7 billion to rail corridor upgrades through 2027 [1], while India's National Rail Plan targets full route electrification with battery-assisted last-mile shunting on non-electrified spurs [2]. Rolling stock buyers now treat energy storage as a specified subsystem, not a consumable.

Legacy chemistry is rapidly losing ground. Vented lead-acid and nickel-cadmium units, which dominated onboard auxiliary and cranking duty for four decades, are being replaced by lithium iron phosphate and lithium titanate packs. These packs offer three to five times the cycle life at a roughly 40% reduced installed mass. The Train Battery Market has absorbed this shift faster than most rail subsystems, and Deutsche Bahn alone has budgeted EUR 1.3 billion for battery-hybrid regional fleets through 2030 [3].

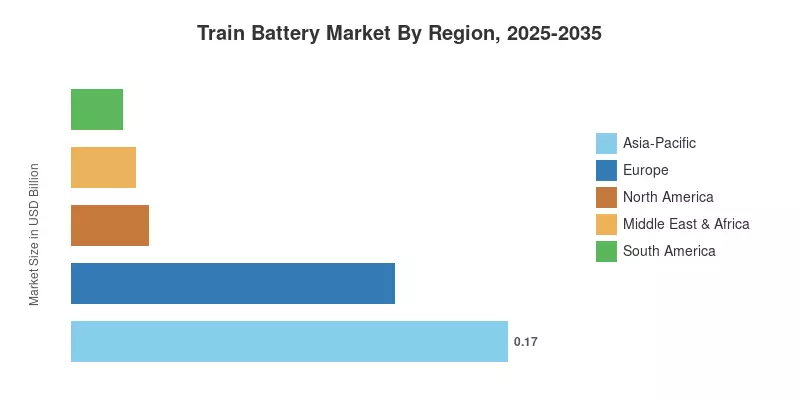
The Asia-Pacific region is responsible for 41% of 2025 revenue, which is bolstered by India's coach modernization program and China's 45,000-km high-speed network. Europe experiences the most rapid growth at a compound annual growth rate (CAGR) of 9.8% due to the impact of diesel-replacement mandates on regional lines. North America follows suit with freight locomotive auxiliary enhancements and commuter fleet renewals. The individual who obtains the upside will be determined by procurement discipline, not cell availability, through 2035.


Key Report Takeaways

• By Battery Chemistry

  • Lithium-ion holds 44% of 2025 revenue across the Train Battery Market and is the default specification for new-build rolling stock.
  • Nickel-cadmium retains a USD 0.118 billion installed base, concentrated in European and Indian legacy fleets.
  • Lithium titanate posts the steepest growth at a 12.4% CAGR, driven by fast-charge shunting duty.

• By Application

  • Traction and propulsion applications generate USD 0.121 billion in 2025 revenue.
  • Auxiliary and onboard power commands a 33% share, the single largest application slice.
  • Emergency and backup duty grows at a 7.6% CAGR under tightening evacuation-lighting standards.

• By Region

  • Asia-Pacific leads the Train Battery Market with 41% of 2025 revenue
  • Europe expands at a 9.8% CAGR, the fastest of any region
  • Middle East & Africa contributes USD 0.025 billion, weighted toward Gulf metro build-outs


Market Size and Forecast (2021–2035)

Sizing for the Train Battery Market blends bottom-up rolling stock census data from national rail regulators with OEM tender awards, aftermarket replacement-cycle modeling, and cell-level pricing from published supply agreements. Historical values reconcile against operator capital expenditure disclosures; forecast values apply fleet renewal schedules and announced procurement pipelines rather than straight-line extrapolation.
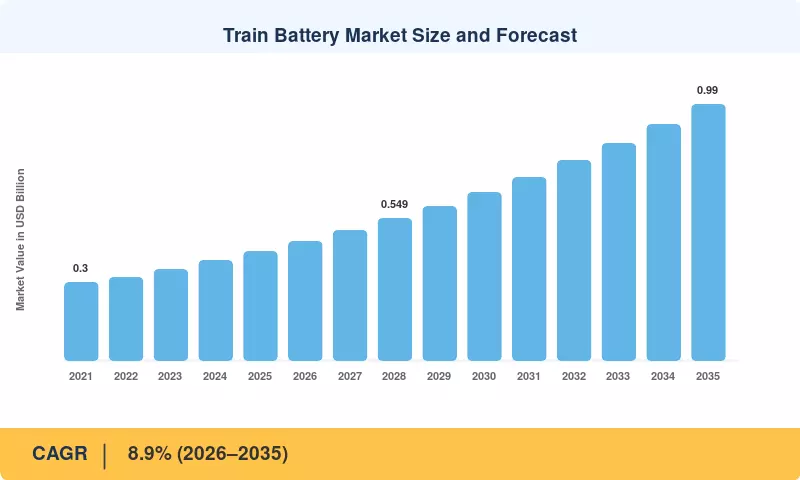
Train Battery Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rail electrification mandates and catenary gap closure +1.6 Europe, Asia-Pacific Medium-term (2–4 yr)
Legacy chemistry retrofit cycle +1.4 Europe, North America Short-term (≤2 yr)
Battery-hybrid rolling stock procurement +1.3 Germany, Japan, India Medium-term (2–4 yr)
Diesel phase-out rules on regional lines +1.1 UK, Germany, US Long-term (≥4 yr)
Falling LFP cell prices +0.9 Global Short-term (≤2 yr)
Metro and light rail expansion in emerging economies +0.8 Asia-Pacific, MEA Long-term (≥4 yr)
Onboard safety and standards tightening +0.6 Global Medium-term (2–4 yr)


Electrification Mandates and the Catenary Gap

According to the International Union of Railways (UIC) and recent Ministry of Railways data tracking global networks, large systems have achieved significant coverage, with Indian Railways reaching 99.6% electrification of its broad gauge network (comprising over 68,700 route km out of nearly 69,000 route km total). In comparison, other global networks range between 39% and 82%.


The Retrofit Wave in Legacy Fleets

Technical standards and modernization blueprints published by the Research Designs and Standards Organisation (RDSO) establish regulatory guidelines for integrating advanced Lithium Iron Phosphate (LFP) auxiliary battery architectures across passenger coach sets, replacing legacy setups under targeted rail modernization phases.


Battery-Hybrid Rolling Stock Procurement

Order books tell the story. Schleswig-Holstein contracted 55 battery-electric regional units in a single award, and Italian operators put battery-hybrid trainsets into revenue service on partially wired corridors [3]. Each trainset carries between 700 kWh and 1.6 MWh of storage — roughly forty times the content of a conventional auxiliary installation. That content multiplier explains why unit growth understates revenue growth by a wide margin.

Cell Economics

Pack-level prices for rail-qualified lithium iron phosphate fell from about USD 210/kWh in 2021 to near USD 128/kWh in 2025 [5]. Rail volumes are too small to move cell markets, so the sector free-rides on automotive scale. Qualification costs and rail-specific enclosures keep a durable premium over automotive pricing. However, the direction of travel has flipped the total-cost calculus against diesel gensets on most regional duty cycles.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Upfront cost premium over incumbent chemistries −1.2 Emerging markets Short-term (≤2 yr)
Homologation and fire-safety certification timelines −0.9 Europe, North America Medium-term (2–4 yr)
Duty-cycle degradation and thermal management −0.7 MEA, South Asia Medium-term (2–4 yr)
Cell supply concentration and raw material volatility −0.6 Global Long-term (≥4 yr)
Depot charging and grid connection constraints −0.5 Europe, North America Long-term (≥4 yr)


Certification Drag

Rail energy storage must clear IEC 62928 and EN 50547 before entering service, and national safety authorities frequently add fire-load assessments on top [9]. Typical homologation runs 14 to 26 months. Suppliers carry that cost without revenue, which pushes smaller entrants out and slows the pace at which new chemistries reach the Train Battery Market. Certification, not engineering, is the real gate.

Duty Cycles Rail Engineers Did Not Design For

Traction packs on regional services see two to four deep cycles per day plus regenerative braking spikes, often in ambient temperatures spanning −25°C to +50°C. Field data from Gulf and South Asian operators shows capacity fade of 18–24% within five years where liquid cooling was omitted to save weight [12]. Warranty exposure of that scale changes bid pricing and has already forced several suppliers to requote long-term service agreements.

Depot Power

Fast-charging multiple battery units draws 1–2 MW at the pantograph. Many depots sit on connections rated for lighting and compressed air, and utility upgrade queues in parts of Europe now exceed three years [13]. Operators are responding with stationary buffer storage and off-peak scheduling, but the constraint is real, and it delays revenue recognition on otherwise signed fleet contracts.


Train Battery Market Opportunities

Second-Life and Stationary Buffer Systems

Traction packs retired at 75–80% state of health still serve depot buffering and substation smoothing. Operators that retain ownership can recover 15–25% of original pack value rather than paying for disposal, converting a liability into infrastructure.

Emerging-Market Metro Build-Outs

Riyadh, Cairo, Jakarta, and Ho Chi Minh City have committed more than USD 60 billion in combined urban rail capital through 2032 [8]. These systems specify storage from day one for emergency traction and evacuation lighting, giving suppliers greenfield entry without the retrofit certification burden that slows European awards.

Battery Health Analytics as a Revenue Line

Telemetry from onboard management systems supports condition-based maintenance contracts priced per trainset-year. Several suppliers now bundle state-of-health monitoring with performance guarantees, shifting margin from hardware to recurring service — the clearest data-monetization path available in the Train Battery Market today.

Freight Yard and Shunting Electrification

Shunting locomotives idle for 60–70% of duty hours, burning diesel to no purpose. Battery-electric shunters cut yard fuel consumption by an estimated 70% and eliminate local emissions in enclosed terminals [7]. North American Class I operators have begun pilot deployments at intermodal hubs.

Standardized Modular Packs

Rail's fragmented voltage classes have historically forced bespoke designs. Modular 48V building blocks that scale from emergency lighting train battery duty to megawatt traction strings would cut engineering cost per program by roughly a third and shorten homologation through type-approval reuse.


Train Battery Market Future Outlook

Chemistry Convergence

By 2030, the sector will likely settle on two chemistries: lithium iron phosphate for energy-dense traction duty and lithium titanate for high-cycle, fast-charge applications. Sodium-ion enters evaluation around 2028 with a cost advantage but a mass penalty rail engineers may tolerate on freight and shunting duty [5].

Predictive Maintenance and Autonomous Depot Operations

Onboard management systems already generate cell-level telemetry at second-by-second resolution. Operators applying machine learning to that stream have reported 20–30% reductions in unplanned battery-related withdrawals, and depot scheduling algorithms will increasingly optimize charging against day-ahead electricity pricing [16].

The Electrification Supercycle

Global rail electricity demand is projected to rise sharply through 2035 as networks convert from diesel, with the International Energy Agency identifying rail as among the most electrified transport modes already [17]. Storage becomes the buffer that makes partial electrification economically viable, extending catenary value rather than replacing it.

Circularity Reporting

The EU Batteries Regulation phases in carbon footprint declarations and recycled content minimums through 2031 [11]. Rail operators bidding on public service contracts will need supplier-verified lifecycle data, which favors established manufacturers with auditable supply chains and disadvantages low-cost importers.


Regional Market Share Analysis

Region Metric Primary Investment Themes
North America 8.1% CAGR Freight auxiliary upgrades, commuter fleet renewal
Europe USD 0.126 Billion Diesel replacement, cadmium phase-out compliance
Asia-Pacific 41% share High-speed expansion, coach modernization
South America 4% share Commuter rail rehabilitation, mining rail
Middle East & Africa USD 0.025 Billion Greenfield metro, harsh-climate qualification
Total USD 0.420 Billion

Regional performance across the Train Battery Market diverges by fleet age and electrification policy rather than by GDP. Europe converts fastest because its diesel deadlines are legally binding; Asia-Pacific leads on absolute volume because its fleet is simply larger. The Train Battery Market in the Americas splits between freight auxiliary demand and commuter renewals.


North America

Country Metric Key Driver
United States 58% of region Class I freight auxiliary and shunting pilots
Canada 7.9% CAGR Commuter fleet renewal in Toronto and Montreal
Mexico USD 0.012 Billion Maya Train and suburban corridor build-out


North America's train battery market is dominated by the United States, which commands 58% of the regional market share driven by Class I freight auxiliary and shunting pilots. Meanwhile, Canada represents the fastest-growing segment, expanding at a 7.9% CAGR due to commuter fleet renewals in Toronto and Montreal. At the same time, Mexico contributes USD 0.012 billion via the Maya Train and suburban corridor build-outs. Policy frameworks like Federal-State Partnership grants and CRISI (Consolidated Rail Infrastructure and Safety Improvements) funding heavily accelerate these deployments by channeling capital toward US rail capital projects and battery-hybrid switchers.


Europe

Country Metric Key Driver
Germany 26% of region Federal state BEMU tenders
United Kingdom USD 0.022 Billion Diesel-only withdrawal target
France 9.6% CAGR Regional TER hybrid conversions
Spain USD 0.011 Billion Cercanías modernization
Rest of Europe 18% of region Nordic and Benelux fleet renewal


Europe's train battery market is dominated by Germany, holding 26% of the regional share through federal-state BEMU tenders. In comparison, France stands as the fastest-growing segment at a 9.6% CAGR driven by regional TER hybrid conversions. The United Kingdom contributes USD 0.022 billion via diesel-only withdrawal targets, Spain adds USD 0.011 billion for Cercanías modernization, and the Rest of Europe accounts for 18% via Nordic and Benelux fleet renewals.

Guided by the EU Batteries Regulation and decarbonization mandates, European operators leverage strict environmental compliance and green public transit tenders to accelerate the widespread adoption of battery-electric and hybrid trainsets.


Asia-Pacific

Country Metric Key Driver
China 34% of region High-speed and metro network expansion
India 11.2% CAGR Coach modernization and lithium specification
Japan USD 0.034 Billion Lithium titanate adoption on regional lines
South Korea 6% of region KTX fleet auxiliary upgrades
Australia 7.8% CAGR Regional and mining rail conversions
Rest of Asia-Pacific USD 0.018 Billion ASEAN urban rail projects


Asia-Pacific's train battery market is dominated by China, capturing 34% of the regional share through high-speed and metro network expansion. India emerges as the fastest-growing segment with an 11.2% CAGR, driven by coach modernization and lithium specifications. Additionally, Japan accounts for USD 0.034 Billion, South Korea holds 6% of the region, Australia grows at a 7.8% CAGR, and the Rest of Asia-Pacific contributes USD 0.018 billion.

Supported by regional sustainability frameworks like national green transport mandates and clean energy railway policies, these markets accelerate local manufacturing and large-scale battery-electric integration.


South America

Country Metric Key Driver
Brazil 61% of region Commuter rehabilitation, mining rail
Chile 8.4% CAGR Santiago metro and regional services
Argentina USD 0.002 Billion Buenos Aires suburban renewal
Rest of South America 9% of region Colombian and Peruvian urban projects


South America's train battery market is dominated by Brazil, which holds 61% of the region, driven by commuter rehabilitation and mining rail. Meanwhile, Chile represents the fastest-growing segment, expanding at an 8.4% CAGR due to Santiago metro and regional services. Argentina contributes USD 0.002 billion via Buenos Aires suburban renewal, and the Rest of South America accounts for 9% of the region through Colombian and Peruvian urban projects. This market expansion is supported by regional policy frameworks such as national electromobility and decarbonization strategies (including Chile's National Electromobility Strategy aiming for sustainable public transport), which promote cleaner energy corridors and modern transit infrastructure.


Middle East & Africa

Country Metric Key Driver
Saudi Arabia USD 0.007 Billion Riyadh Metro and Landbridge program
United Arab Emirates 10.1% CAGR Etihad Rail expansion
South Africa 21% of region Transnet and PRASA fleet recovery
Egypt 9.2% CAGR Cairo monorail and national network upgrade
Rest of MEA 12% of region North African and East African corridors


The Middle East and Africa train battery market is dominated by South Africa, accounting for 21% of the region through Transnet and PRASA fleet recoveries. At the same time, the United Arab Emirates is the fastest-growing segment, expanding at a 10.1% CAGR driven by the Etihad Rail expansion. Additional metrics include Saudi Arabia at USD 0.007 billion (Riyadh Metro and Landbridge program), Egypt at a 9.2% CAGR (Cairo monorail and national network upgrades), and the Rest of MEA at 12% of the region.

Guided by regional decarbonization and green mobility frameworks—such as national sustainability strategies and transit transition plans—governments across the region are heavily investing in new-build urban and freight rail infrastructure.


Train Battery Market By Region, 2025-2035

Train Battery Market Segmentation

By Battery Type

Chemistry choice remains the sharpest dividing line in the Train Battery Market.

Segment Metric Primary Demand Driver
Lithium-ion (LFP/NMC) 44% share New-build rolling stock specification
Nickel-cadmium USD 0.118 Billion Legacy fleet installed base
Lead-acid 21% share Cost-sensitive aftermarket replacement
Lithium titanate 12.4% CAGR Fast-charge and shunting duty
Others USD 0.010 Billion Hybrid supercapacitor configurations


Lithium-ion with 44% share crossed the majority threshold in new procurement around 2023 and has not looked back; its advantage compounds because maintenance savings accrue over a 12–15 year service life. Nickel-cadmium remains commercially significant but is a declining annuity — revenue holds up on replacement demand even as its share of new specifications approaches zero. Lead-acid persists where capital budgets are thinnest, particularly in freight wagon and older coach applications.

By Application

Application mix determines pack size, and pack size determines revenue concentration within the Train Battery Market.

Segment Metric Primary Demand Driver
Auxiliary and onboard power 33% share HVAC, lighting, control systems
Traction and propulsion USD 0.121 Billion Battery-hybrid and battery-electric units
Starter and cranking 18% share Diesel locomotive fleets
Emergency and backup 7.6% CAGR Evacuation lighting standards


Auxiliary duty with 33% share dominates as every powered vehicle needs it, and replacement cycles are predictable. Traction is the value business: a single trainset installation can exceed the revenue of two hundred auxiliary packs. That asymmetry is why supplier strategy has tilted so heavily toward traction qualification despite the longer sales cycle and heavier warranty exposure.

By Rolling Stock Type

Fleet composition shapes regional demand patterns across the Train Battery Market.

Segment Metric Primary Demand Driver
Electric and battery multiple units 29% share Regional service diesel replacement
Diesel locomotives USD 0.096 Billion Cranking and auxiliary replacement
Metro and light rail 10.8% CAGR Urban network expansion
Passenger coaches 19% share Lighting and HVAC backup
Freight wagons and specialty USD 0.029 Billion Telemetry and brake systems


The rolling stock type segment of the train battery market is shaped by diverse fleet demands, featuring electric and battery multiple units at 29% share, diesel locomotives at USD 0.096 billion, passenger coaches at 19% share, and freight wagons at USD 0.029 billion. Electric and battery multiple units act as the dominating segment driven by regional diesel replacements, while metro and light rail stand as the fastest-growing segment expanding at a 10.8% CAGR due to urban network expansions. This segment is supported by international public transport decarbonization targets and green rail transit frameworks.

By Sales Channel

Segment Metric Primary Demand Driver
OEM 54% share New-build rolling stock programs
Aftermarket USD 0.193 Billion Scheduled overhaul and retrofit


The sales channel segment within the train battery market divides expenditure between OEM and aftermarket streams. The OEM channel dominates the market with a 54% share driven by new-build rolling stock programs. In contrast, the aftermarket channel is valued at USD 0.193 billion, fueled by scheduled overhauls and retrofits. This market structure is governed by international supplier quality standards like IEC 62928 and regional circularity policies such as the EU Batteries Regulation, which dictate compliance for both new equipment manufacturing and long-term fleet maintenance cycles.


Competitive Benchmarking

Concentration sits in the moderate band, with an estimated HHI near 1,050 and a top-five combined share of roughly 51%. Specialist rail battery houses hold defensible positions because certification history is difficult to replicate, while regional players dominate their home aftermarkets on service coverage rather than technology. Cell manufacturers are pressing upward into pack integration, and the Train Battery Market should expect further consolidation as automotive-scale suppliers seek rail qualification.

Company Est. Revenue Share Range Key Offerings for Train Battery Market Strategic Positioning
Saft (TotalEnergies) ~14–18% Nickel and lithium onboard systems Rail-certified incumbent, broad OEM approvals
EnerSys ~9–12% Onboard and auxiliary storage Global aftermarket reach, industrial breadth
Hoppecke Batterien ~7–10% NiCd and lithium rail packs European depot service depth
Toshiba Corporation ~6–9% Lithium titanate modules Fast-charge specialist, Japanese OEM ties
GS Yuasa ~5–8% Lithium and lead-acid rail units Asia-Pacific volume leadership
Exide Industries ~4–6% Coach and locomotive batteries Indian Railways approved supplier
HBL Power Systems ~3–5% Nickel-based and lithium systems South Asian retrofit specialist
Leclanché ~3–5% Traction battery systems High-energy modular architecture
Amara Raja Energy & Mobility ~2–4% Industrial and rail storage Cost-competitive emerging-market supply
Sichuan Changhong Battery ~2–4% Rail auxiliary and traction cells Domestic Chinese fleet coverage


Recent News & Developments

  • Hitachi Rail (September 2023): Placed battery-hybrid trainsets into commercial service on partially electrified Italian regional routes, validating hybrid operation at scale [3]
  • Stadler (March 2024): Delivered the first units of a 55-trainset battery-electric order for Schleswig-Holstein, one of the largest such contracts awarded to date [3]
  • European Commission (July 2024): Advanced implementation phases of the Batteries Regulation covering carbon footprint declaration and cadmium restrictions affecting rail packs [11]
  • Toshiba (November 2024): Expanded lithium titanate module production capacity, citing rail and heavy-duty transport demand [18]
  • Indian Railways (January 2025): Issued revised technical specifications for lithium-based coach batteries, widening the approved vendor pool [2]
  • Saft (April 2025): Announced expanded rail-qualified lithium production supporting European regional fleet programs [19]
  • US Federal Railroad Administration (June 2025): Confirmed grant awards including battery-electric switching locomotive deployments at intermodal terminals [14]
  • Etihad Rail (August 2025): Advanced passenger service procurement with high-temperature-qualified onboard storage specified [8]


Train Battery Market Report Scope

Parameter Detail
Market Scope Onboard energy storage for rolling stock: traction, auxiliary, starter, and emergency applications across all chemistries
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.9% (2026–2035)
Market Size Checkpoints USD 0.42 Billion (2025); USD 0.46 Billion (2026); USD 0.65 Billion (2030); USD 0.99 Billion (2035)
Fastest Growing Segments Lithium titanate by chemistry; metro and light rail by rolling stock type
Companies Profiled Saft, EnerSys, Hoppecke, Toshiba, GS Yuasa, Exide Industries, HBL Power Systems, Leclanché, Amara Raja Energy & Mobility, Sichuan Changhong
Valuation Currency USD, constant 2025 prices

FAQs

What procurement structure works best for first-time buyers entering the Train Battery Market?
Bundle the pack with a performance-guaranteed service agreement covering state of health at defined intervals. This shifts degradation risk to the supplier and gives finance teams a predictable per-year cost rather than a lumpy replacement liability [6].
How do lithium titanate and lithium iron phosphate compare for rail duty?
Titanate accepts charge roughly four times faster and tolerates 15,000-plus cycles, making it right for terminal-charge shunting. Iron phosphate offers better energy per kilogram and lower cost, which suits longer independent-range traction [18].
What integration issue most often derails a Train Battery Market retrofit project?
Vehicle mass and axle-load limits. Adding traction storage frequently pushes a converted unit past its certified axle load, forcing structural rework or reduced pack size that undercuts the original business case [21].
Are there insurance or warranty considerations buyers underestimate?
Yes — fire-load classification affects depot insurance premiums, and several underwriters now require thermal propagation test evidence before covering enclosed maintenance facilities. Budget for testing documentation early [9].
How should investors read consolidation signals in the Train Battery Market?
Watch type-approval portfolios rather than revenue. A supplier holding approvals across multiple national authorities carries acquisition value that recent financials rarely reflect, because approvals take years to reproduce [21].
What regulatory nuance catches exporters off guard?
Transport classification. Rail-scale packs exceed UN 38.3 shipping thresholds for single units, requiring segmented shipment or specialized carriers, which adds cost and lead time to cross-border supply [11].
Which emerging use case deserves attention beyond passenger and freight rail?
Track maintenance machinery. Tampers and inspection vehicles operate inside tunnels and stations where diesel exhaust is a hard constraint, and battery conversion is proceeding faster than most fleet forecasts capture [20].    
Author
Author Author Profile Abbas Raut LinkedIn Research Analyst
Abbas Raut is a Senior Research Analyst with 5+ years of experience delivering data-driven insights and strategic recommendations across the Automotive and Aerospace & Defense sectors. He specializes in emerging technologies, industry value chains, and global market dynamics shaping the future of mobility and defense. In automotive, Abbas has led studies on EVs, charging stations, BMS, superchargers, and more, guiding stakeholders through electrification and regulatory shifts. In Aerospace & Defense, he has analyzed markets for military electronics, drones, radars, and electronic warfare solutions, supporting procurement and investment strategies. With expertise in market sizing, forecasting, benchmarking, and technology adoption, Abbas is known for transforming complex datasets into actionable insights that drive strategy, innovation, and growth.
Co-Author Co-Author Profile Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, technical standards, and authoritative transportation and energy organizations. Key sources included the International Union of Railways (UIC), International Energy Agency (IEA), International Renewable Energy Agency (IRENA), US Department of Transportation (DOT), Federal Railroad Administration (FRA), European Union Agency for Railways (ERA), European Commission Transport Research and Innovation Monitoring and Information System (TRIMIS), International Electrotechnical Commission (IEC), Institute of Electrical and Electronics Engineers (IEEE), International Association of Public Transport (UITP), Association of American Railroads (AAR), Railway Supply Institute (RSI), International Battery Association (IBA), US Energy Information Administration (EIA), International Transport Forum (ITF), OECD Transport Division, national railway administrations from key markets (Deutsche Bahn, SNCF, JR East, Indian Railways, China State Railway Group), and technical publications from the Journal of Power Sources, Batteries, and IEEE Transactions on Transportation Electrification. These sources were used to collect railway electrification statistics, battery technology deployment data, regulatory compliance standards, carbon emission reduction targets, infrastructure investment trends, and competitive landscape analysis for lithium-ion, lead-acid, nickel-metal hydride, and nickel-cadmium battery technologies in rail applications.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, CTOs, VPs of Engineering, heads of railway divisions, and commercial directors from rolling stock manufacturers, battery makers, and railway system integrators were examples of supply-side sources. Chief mechanical engineers, fleet managers, procurement directors from national railway operators, urban transit agencies, freight rail businesses, and infrastructure managers were examples of demand-side sources. Market segmentation, technological roadmap timescales, procurement trends, lifetime cost analysis, charging infrastructure needs, and regulatory compliance tactics were all confirmed by primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (33%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and deployment volume analysis. The methodology included:

Identification of 40+ key manufacturers and system integrators across North America, Europe, Asia-Pacific, and Latin America

Product mapping across lithium-ion, lead-acid, nickel-metal hydride, and nickel-cadmium battery categories

Analysis of reported and modeled annual revenues specific to railway battery portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (battery capacity deployment × ASP by region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations across battery type, train type, application, and end-use segments

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















