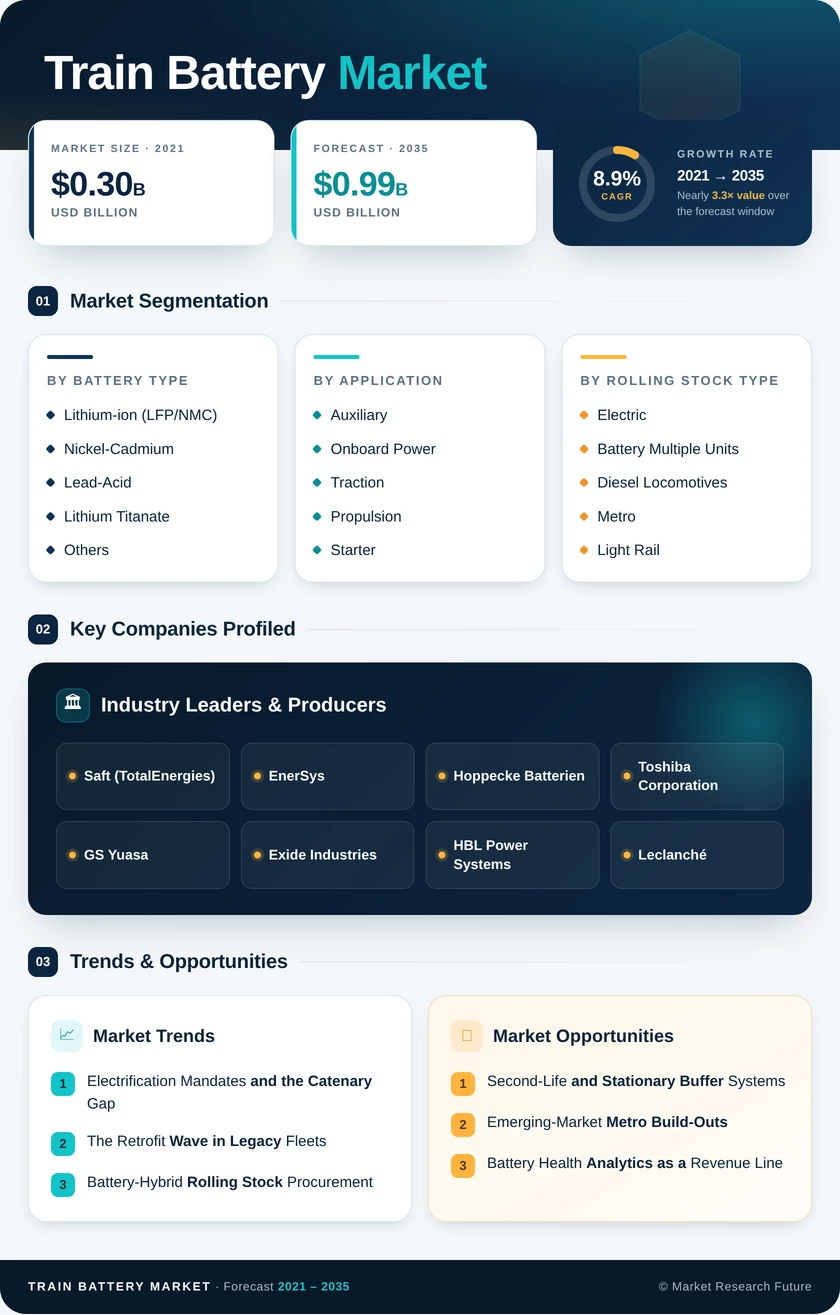
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Battery Type | Lithium-ion (LFP/NMC), Nickel-Cadmium, Lead-Acid, Lithium Titanate, Others | Lithium-ion (LFP/NMC) | Lithium Titanate |
| By Application | Auxiliary and Onboard Power, Traction and Propulsion, Starter and Cranking, Emergency and Backup | Auxiliary and Onboard Power | Traction and Propulsion |
| By Rolling Stock Type | Electric and Battery Multiple Units, Diesel Locomotives, Metro and Light Rail, Passenger Coaches, Freight Wagons and Specialty Vehicles | Electric and Battery Multiple Units | Metro and Light Rail |
| By Sales Channel | OEM, Aftermarket | OEM | Aftermarket |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | Europe |
Market Segmentation Overview
By Battery Type
| Sub-Segment | Key Trend |
| Lithium-ion (LFP/NMC) | Default specification for new-build traction and auxiliary systems |
| Nickel-Cadmium | Declining annuity supported by legacy installed base and phased cadmium restrictions. |
| Lead-Acid | Retained in cost-constrained freight and older coach applications |
| Lithium Titanate | Preferred where terminal fast-charge and deep cycling dominate the duty profile |
| Others | Supercapacitor-hybrid configurations for braking energy capture |
Chemistry selection has become a lifecycle-cost decision rather than a purchase-price decision. Operators modeling twelve to fifteen years of service consistently find lithium variants cheaper despite higher acquisition cost, and disposal obligations on cadmium-bearing units are accelerating conversion in regulated jurisdictions.
By Application
| Sub-Segment | Key Trend |
| Auxiliary and Onboard Power | Steady replacement demand tied to HVAC and control system loads |
| Traction and Propulsion | Highest revenue per installation; drives supplier qualification strategy |
| Starter and Cranking | Stable but structurally declining with diesel fleet retirement |
| Emergency and Backup | Growth driven by tightening evacuation and lighting standards |
Traction installations dominate revenue growth while auxiliary installations dominate unit volume, and the gap between those two curves is widening each year. Suppliers positioned only in auxiliary duty will hold share by count while losing it by value.
By Rolling Stock Type
| Sub-Segment | Key Trend |
| Electric and Battery Multiple Units | Central platform for regional diesel replacement programs |
| Diesel Locomotives | Cranking and auxiliary demand persists through fleet transition. |
| Metro and Light Rail | Fastest expansion, concentrated in emerging-economy urban projects |
| Passenger Coaches | Lighting and climate backup drives predictable replacement cycles. |
| Freight Wagons and Specialty Vehicles | Telemetry, brake, and maintenance machinery electrification |
Fleet age determines which sub-segment leads in any given country. Mature European and Japanese networks convert multiple units first; expanding Asian and Gulf networks generate metro demand ahead of mainline conversion.
By Sales Channel
| Sub-Segment | Key Trend |
| OEM | Specification locked at rolling stock design stage, long qualification cycles |
| Aftermarket | Retrofit and scheduled overhaul demand, higher margin, service-led |
OEM channel share reflects new-build activity, while aftermarket performance tracks the installed base and overhaul calendars. Suppliers with both channels smooth revenue across procurement cycles that can otherwise swing sharply year to year.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA