Torque Vectoring Market (2026 - 2035)

ID: MRFR/AT/5191-CR 138 Pages Shubham Munde Last Updated: September 15, 2026
Torque Vectoring Market Research Report By Vehicle Type (Passenger Car, Commercial Vehicle), By Drive Type (Rear-Wheel Drive, Front-Wheel Drive, All-Wheel Drive), By Torque Vectoring Technology Type (Brake-Based, Differential-Based, Electronic), By Propulsion Type (ICE, HEV, BEV, FCEV) - Forecast to 2035
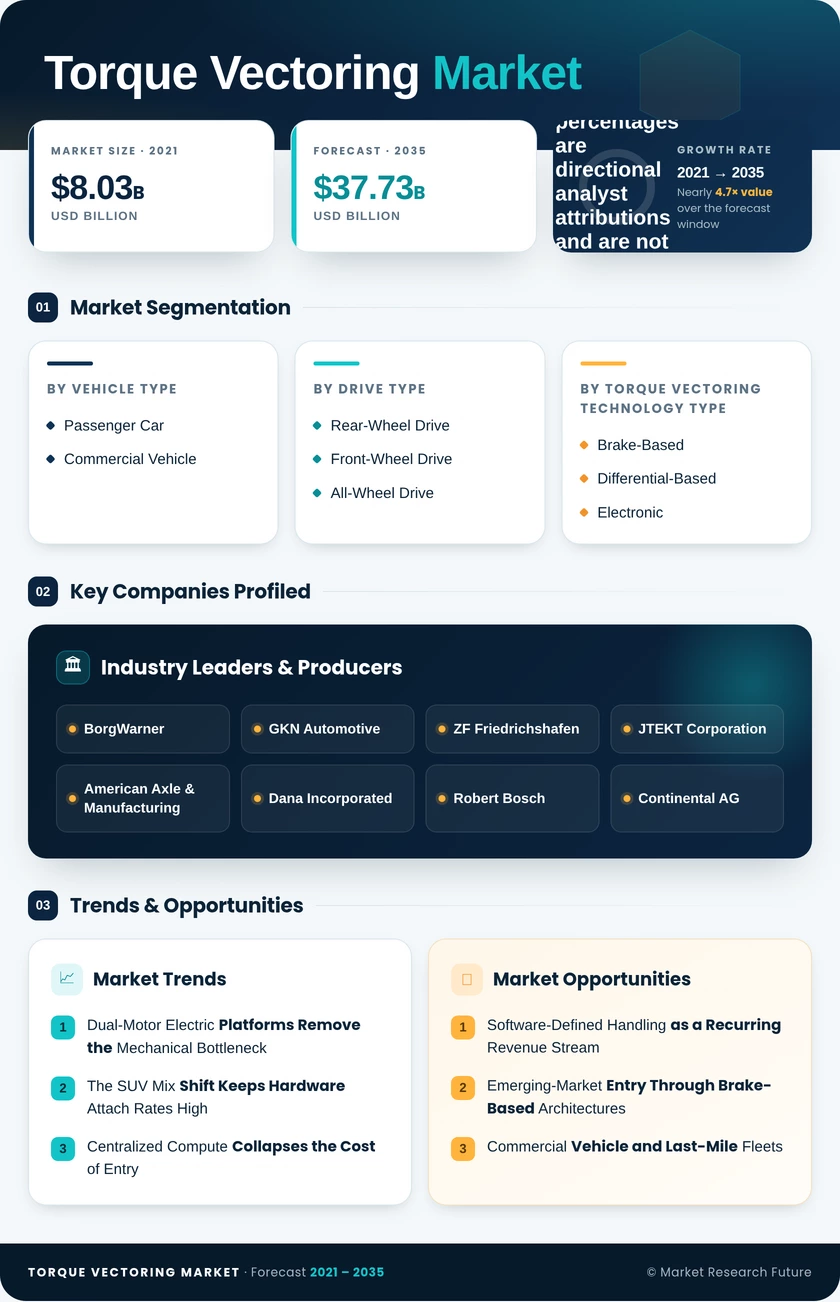
Torque Vectoring Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.2%
2025 Market SizeUSD 11.93 Billion
2035 Market SizeUSD 37.73 Billion
Key Players
BorgWarner
GKN Automotive
ZF Friedrichshafen
JTEKT Corporation
American Axle & Manufacturing
Dana Incorporated
Opportunities
  • Software-Defined Handling as a Recurring Revenue Stream
  • Emerging-Market Entry Through Brake-Based Architectures
  • Commercial Vehicle and Last-Mile Fleets
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Drivers Analysis | |
    1. 4.1 Dual-Motor Electric Platform Proliferation | |
    2. 4.2 SUV and Crossover Model-Mix Shift | |
    3. 4.3 Centralized E/E Architecture Rollout | |
    4. 4.4 Mandated Stability-Control Sensor Base | |
    5. 4.5 Premium and Performance Trim Demand | |
    6. 4.6 ADAS and Autonomy Chassis Integration | |
    7. 4.7 Software-Monetization Business Models | |
  5. 5 Market Restraints Analysis | |
    1. 5.1 Component Cost Versus Entry-Segment Budgets | |
    2. 5.2 Calibration and Validation Engineering Burden | |
    3. 5.3 Added Mass and Efficiency Penalty | |
    4. 5.4 Aftermarket Service and Diagnostic Complexity | |
    5. 5.5 Functional Safety Certification Cost | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Software-Defined Handling as Recurring Revenue | |
    2. 6.2 Emerging-Market Entry Through Brake-Based Architectures | |
    3. 6.3 Commercial Vehicle and Last-Mile Fleets | |
    4. 6.4 Integration With Autonomous Path-Following | |
    5. 6.5 Data Monetization From Chassis Telemetry | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Chassis Control as an Autonomy Prerequisite | |
    2. 8.2 Platform Economics and Software Suppliers | |
    3. 8.3 Electrification Supercycle and Attach Rates | |
    4. 8.4 Efficiency Reporting and Design Discipline | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Vehicle Type | | |
      1. 9.1.1 Passenger Car | | |
      2. 9.1.2 Commercial Vehicle | |
    2. 9.2 By Drive Type | | |
      1. 9.2.1 Rear-Wheel Drive | | |
      2. 9.2.2 Front-Wheel Drive | | |
      3. 9.2.3 All-Wheel Drive | |
    3. 9.3 By Torque Vectoring Technology Type | | |
      1. 9.3.1 Brake-Based | | |
      2. 9.3.2 Differential-Based | | |
      3. 9.3.3 Electronic | |
    4. 9.4 By Propulsion Type | | |
      1. 9.4.1 ICE | | |
      2. 9.4.2 HEV | | |
      3. 9.4.3 BEV | | |
      4. 9.4.4 FCEV | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 BorgWarner | | |
      2. 10.3.2 GKN Automotive | | |
      3. 10.3.3 ZF Friedrichshafen | | |
      4. 10.3.4 JTEKT Corporation | | |
      5. 10.3.5 American Axle & Manufacturing | | |
      6. 10.3.6 Dana Incorporated | | |
      7. 10.3.7 Robert Bosch | | |
      8. 10.3.8 Continental AG | | |
      9. 10.3.9 Schaeffler AG | | |
      10. 10.3.10 Magna International | | |
      11. 10.3.11 Eaton Corporation | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Valuation Currency & Units | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Torque Vectoring Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Torque Vectoring Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis – Global Torque Vectoring Market, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis – Global Torque Vectoring Market, 2026–2035 | |
  19. TABLE 5 Global Torque Vectoring Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Torque Vectoring Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Torque Vectoring Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Torque Vectoring Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Torque Vectoring Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Torque Vectoring Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Torque Vectoring Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Torque Vectoring Market Size, by Drive Type, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Torque Vectoring Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  29. TABLE 15 North America Torque Vectoring Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Torque Vectoring Market Size, by Drive Type, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  32. TABLE 18 North America Torque Vectoring Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  33. TABLE 19 Europe Torque Vectoring Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  34. TABLE 20 Europe Torque Vectoring Market Size, by Drive Type, 2021–2035 (USD Billion) | |
  35. TABLE 21 Europe Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  36. TABLE 22 Europe Torque Vectoring Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  37. TABLE 23 Asia-Pacific Torque Vectoring Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  38. TABLE 24 Asia-Pacific Torque Vectoring Market Size, by Drive Type, 2021–2035 (USD Billion) | |
  39. TABLE 25 Asia-Pacific Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  40. TABLE 26 Asia-Pacific Torque Vectoring Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  41. TABLE 27 South America Torque Vectoring Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  42. TABLE 28 South America Torque Vectoring Market Size, by Drive Type, 2021–2035 (USD Billion) | |
  43. TABLE 29 South America Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  44. TABLE 30 South America Torque Vectoring Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  45. TABLE 31 Middle East & Africa Torque Vectoring Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  46. TABLE 32 Middle East & Africa Torque Vectoring Market Size, by Drive Type, 2021–2035 (USD Billion) | |
  47. TABLE 33 Middle East & Africa Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  48. TABLE 34 Middle East & Africa Torque Vectoring Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  49. TABLE 35 US Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  50. TABLE 36 Canada Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  51. TABLE 37 Mexico Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  52. TABLE 38 Germany Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  53. TABLE 39 UK Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  54. TABLE 40 France Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  55. TABLE 41 Italy Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  56. TABLE 42 Spain Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  57. TABLE 43 Nordic Countries Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  58. TABLE 44 China Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  59. TABLE 45 India Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  60. TABLE 46 Japan Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  61. TABLE 47 South Korea Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  62. TABLE 48 ASEAN Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  63. TABLE 49 Brazil Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  64. TABLE 50 Saudi Arabia Torque Vectoring Market Size, by Technology Type, 2021–2035 (USD Billion) | |
  65. TABLE 51 Competitive Benchmarking Matrix – Global Torque Vectoring Market, 2026 | |
  66. TABLE 52 Company Profiles – Key Players, Global Torque Vectoring Market | |
  67. TABLE 53 Recent Developments & Strategic Announcements, 2023–2025 | |
  68. TABLE 54 Report Scope & Methodology Summary | |
  69. TABLE 55 Detailed Sources & Citations Index | | LIST OF FIGURES | |
  70. FIGURE 1 Global Torque Vectoring Market – Market Dynamics Snapshot (Drivers, Restraints, Opportunities) | |
  71. FIGURE 2 Industry Value Chain Analysis – Torque Vectoring Ecosystem | |
  72. FIGURE 3 Porter's Five Forces Analysis – Global Torque Vectoring Market | |
  73. FIGURE 4 Global Torque Vectoring Market Size Trend, 2021–2035 (USD Billion) | |
  74. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 (%) | |
  75. FIGURE 6 Driver Impact Weighting – Contribution to Forecast Growth | |
  76. FIGURE 7 Restraint Impact Weighting – Drag on Forecast Growth | |
  77. FIGURE 8 Market Share by Vehicle Type, 2025 vs 2035 (%) | |
  78. FIGURE 9 Market Share by Drive Type, 2025 vs 2035 (%) | |
  79. FIGURE 10 Market Share by Torque Vectoring Technology Type, 2025 vs 2035 (%) | |
  80. FIGURE 11 Market Share by Propulsion Type, 2025 vs 2035 (%) | |
  81. FIGURE 12 Regional Market Share Distribution, 2025 (%) | |
  82. FIGURE 13 Regional Market Share Distribution, 2035 (%) | |
  83. FIGURE 14 Regional CAGR Comparison, 2026–2035 (%) | |
  84. FIGURE 15 North America Country-Level Share Breakdown, 2025 (%) | |
  85. FIGURE 16 Europe Country-Level Share Breakdown, 2025 (%) | |
  86. FIGURE 17 Asia-Pacific Country-Level Share Breakdown, 2025 (%) | |
  87. FIGURE 18 Competitive Landscape – Estimated Revenue Share Bands, 2026 | |
  88. FIGURE 19 Competitive Positioning Matrix – Hardware Depth vs Software Capability | |
  89. FIGURE 20 Technology Adoption S-Curve – Mechanical to Electronic Transition, 2021–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Vehicle TypePassenger Car; Commercial VehiclePassenger CarCommercial Vehicle
By Drive TypeRear-Wheel Drive; Front-Wheel Drive; All-Wheel DriveAll-Wheel DriveAll-Wheel Drive
By Torque Vectoring Technology TypeBrake-Based; Differential-Based; ElectronicDifferential-BasedElectronic
By Propulsion TypeICE; HEV; BEV; FCEVICEBEV
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarSUV and crossover mix keeps AWD hardware attach rates structurally high
Commercial VehicleElectrified delivery vans adopt independent motors for urban manoeuvrability


By Drive Type

Sub-SegmentKey Trend
Rear-Wheel DriveTwin-clutch rear differentials define premium performance calibration
Front-Wheel DriveBrake-based logic extends capability without added hardware cost
All-Wheel DriveHighest content per vehicle and strongest growth across all regions


All-wheel drive dominates because four driven wheels create the widest control envelope and the richest bill of materials. Front-wheel-drive growth is quieter but strategically important, since software-only implementations open volume segments that mechanical hardware can never reach on cost.

By Torque Vectoring Technology Type

Sub-SegmentKey Trend
Brake-BasedReuses mandated stability-control actuators for near-zero incremental cost
Differential-BasedMature clutch-pack and planetary units anchor premium AWD programs
ElectronicDual-motor and e-axle layouts deliver millisecond-scale torque authority


Differential-based hardware retains the largest installed base and a deep supplier ecosystem. Electronic control is displacing it from the top down, because on a dual-motor platform vectoring capability arrives as a consequence of drivetrain architecture rather than a separate purchase decision.

By Propulsion Type

Sub-SegmentKey Trend
ICELarge installed AWD SUV and pickup base sustains near-term volume
HEVElectrified rear axles add vectoring while preserving conventional economics
BEVIndependent-motor architectures drive the fastest segment expansion
FCEVLimited to niche commercial and demonstration fleet deployments


Internal combustion still supplies most units and will through the late 2020s given fleet replacement cycles. Battery electric platforms carry higher software content per vehicle and shift value toward calibration IP, while hybrids occupy a pragmatic middle ground that suppliers should not underestimate.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.