Tooling Dies for Automotive Aerospace and Industrial Market (2026 - 2035)

ID: MRFR/Equip/66604-CR 200 Pages Snehal Singh Last Updated: October 16, 2026
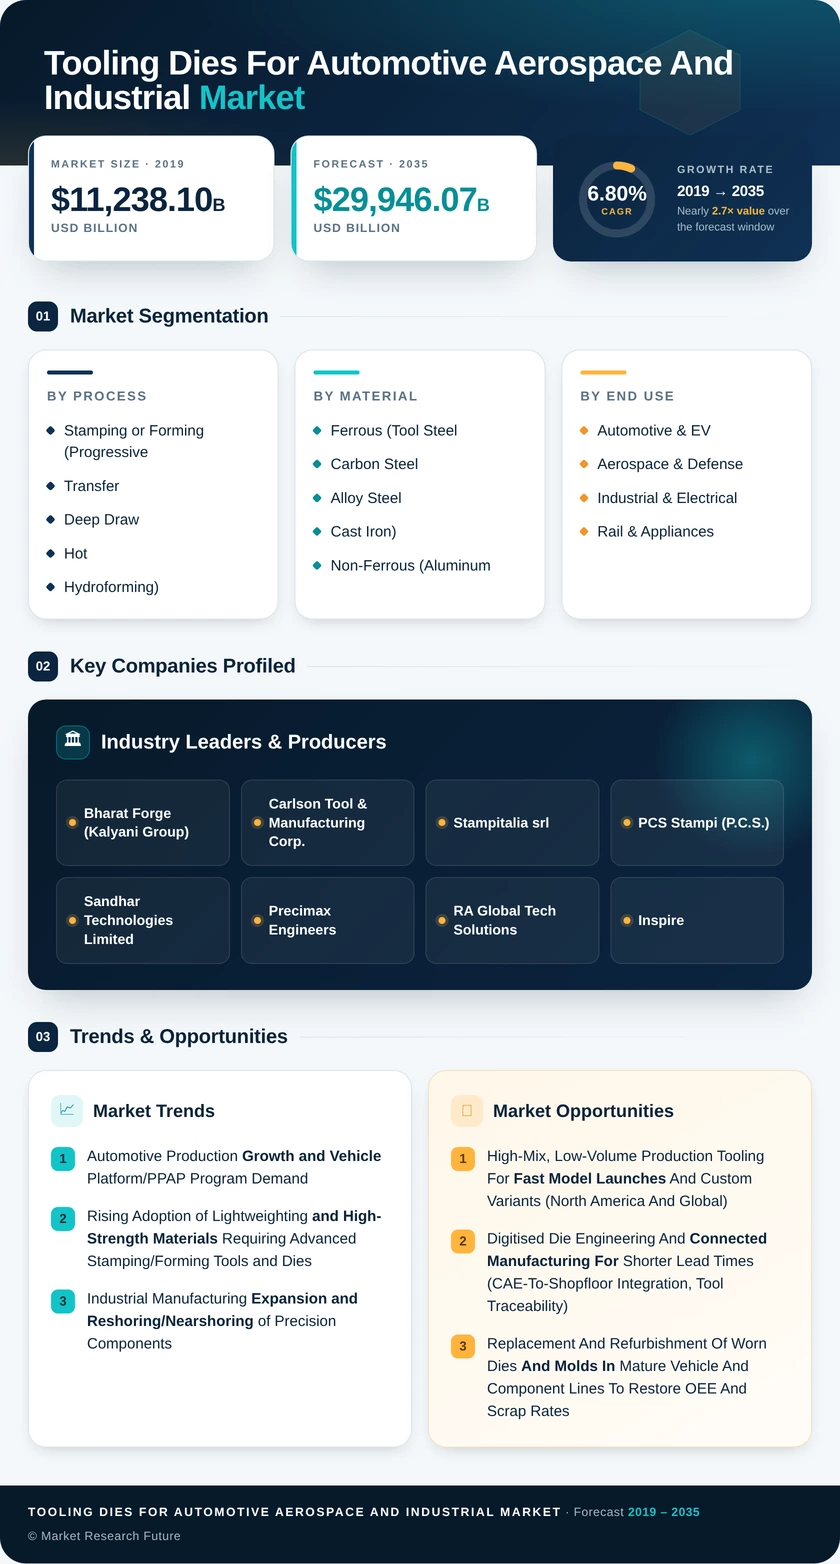
Tooling Dies for Automotive, Aerospace and Industrial Market Research Report By Process (Stamping or Forming (Progressive, Transfer, Deep Draw, Hot, Hydroforming), Die Casting (HPDC, LPDC, GDC + Trimming), Extrusion (Solid, Hollow, Porthole, Bridge), Forging, Tube or Forming (Bending, End Forming, Hydroformng)), By Material (Ferrous Materials (Tool Steel, Carbon Steel, Alloy Steel, Cast Iron), Non-Ferrous Materials (Aluminum, Zinc, Magnesium, Titanium or Superalloys)), By End Use (Automotive and EV, Aerospace and Defense, Industrial Electrical, Rail or Appliances), By Customer (Stamping Houses, Die Casters or Foundries, Extruders, Aerospace Primes or Tier, Contract Tool Rooms) - Forecast to 2035
Tooling Dies for Automotive Aerospace and Industrial Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.80%
2025 Market SizeUSD 15,285.26 Million (USD 15.29 Billion)
2035 Market SizeUSD 29,946.07 Million (USD 29.95 Billion)
Key Players
Bharat Forge
Carlson Tool & Manufacturing Corp.
Stampitalia srl
PCS Stampi
Sandhar Technologies Limited
Precimax Engineers
Opportunities
  • High-Mix, Low-Volume Production Tooling For Fast Model Launches And Custom Variants (North America And Global)
  • Digitised Die Engineering And Connected Manufacturing For Shorter Lead Times (CAE-To-Shopfloor Integration, Tool Traceability)
  • Replacement And Refurbishment Of Worn Dies And Molds In Mature Vehicle And Component Lines To Restore OEE And Scrap Rates
  1. 1 EXECUTIVE SUMMARY22 | |
  2. 2 MARKET INTRODUCTION26 | |
    1. 2.1 DEFINITION26 | |
    2. 2.2 SCOPE OF THE STUDY26 | |
    3. 2.3 Research Objective26 | |
    4. 2.4 MARKET STRUCTURE27 | |
  3. 3 RESEARCH METHODOLOGY28 | |
    1. 3.1 OVERVIEW28 | |
    2. 3.2 DATA flow30 | | |
      1. 3.2.1 DATA MINING PROCESS30 | |
    3. 3.3 Purchased Database:31 | |
    4. 3.4 Secondary Sources:32 | | |
      1. 3.4.1 SECONDARY RESEARCH DATA FLOW:33 | |
    5. 3.5 Primary Research:34 | | |
      1. 3.5.1 PRIMARY RESEARCH DATA FLOW:35 | | |
      2. 3.5.2 PRIMARY RESEARCH: NUMBER OF INTERVIEWS CONDUCTED36 | | |
      3. 3.5.3 PRIMARY RESEARCH: REGIONAL COVERAGE36 | |
    6. 3.6 Approaches for market size estimation:37 | | |
      1. 3.6.1 CONSUMPTION & NET TRADE APPROACH37 | | |
      2. 3.6.2 REVENUE ANALYSIS APPROACH37 | |
    7. 3.7 Data forecasting38 | | |
      1. 3.7.1 DATA FORECASTING TECHNIQUE38 | |
    8. 3.8 Data modeling39 | | |
      1. 3.8.1 MICROECONOMIC FACTOR ANALYSIS:39 | | |
      2. 3.8.2 DATA MODELING:40 | |
    9. 3.9 Teams and Analyst Contribution41 | |
  4. 4 MARKET DYNAMICS43 | |
    1. 4.1 Introduction43 | |
    2. 4.2 Market Trends and Growth Affecting Factors44 | |
    3. 4.3 Growth Parameters Mapped - Drivers44 | | |
      1. 4.3.1 AUTOMOTIVE PRODUCTION GROWTH AND VEHICLE PLATFORM/PPAP PROGRAM DEMAND (GLOBAL OEM AND SUPPLIER OUTSOURCING)44 | | |
      2. 4.3.2 RISING ADOPTION OF LIGHTWEIGHTING AND HIGH-STRENGTH MATERIALS REQUIRING ADVANCED STAMPING/FORMING TOOLS AND DIES45 | | |
      3. 4.3.3 INDUSTRIAL MANUFACTURING EXPANSION AND RESHORING/NEARSHORING OF PRECISION COMPONENTS (CAPACITY BUILD-OUTS)46 | | |
      4. 4.3.4 AEROSPACE PRODUCTION RECOVERY AND LONG-CYCLE AIRCRAFT PRODUCTION PROGRAMS INCREASING DEMAND FOR HIGH-PRECISION DIES46 | | |
      5. 4.3.5 TECHNOLOGICAL UPGRADES IN TOOLING (AUTOMATION, SIMULATION, ADDITIVE-ASSISTED TOOLING, HIGH-WEAR COATINGS) IMPROVING THROUGHPUT AND REDUCING DOWNTIME47 | |
    4. 4.4 Growth Inhibitors Mapped - Restraints50 | | |
      1. 4.4.1 HIGH UPFRONT CAPEX AND LONG PAYBACK CYCLES FOR ADVANCED TOOLING AND DIE INVESTMENTS50 | | |
      2. 4.4.2 VOLATILE RAW MATERIAL AND STEEL/INSERT PRICING AFFECTING DIE COST AND QUOTING50 | | |
      3. 4.4.3 STRINGENT QUALITY, CERTIFICATION, AND TRACEABILITY REQUIREMENTS INCREASING ENGINEERING AND VALIDATION TIME51 | | |
      4. 4.4.4 SKILLED LABOR SHORTAGES IN TOOLMAKING, MAINTENANCE, AND ADVANCED MACHINING/TRYOUT OPERATIONS52 | | |
      5. 4.4.5 SUPPLY CHAIN DISRUPTIONS FOR PRECISION COMPONENTS (MACHINING BLANKS, CARBIDE INSERTS, COATINGS, TOOLING ACCESSORIES) AND LEAD-TIME UNCERTAINTY52 | |
    5. 4.5 Market Opportunities Mapped54 | | |
      1. 4.5.1 HIGH-MIX, LOW-VOLUME PRODUCTION TOOLING FOR FAST MODEL LAUNCHES AND CUSTOM VARIANTS (NA AND GLOBAL)54 | | |
      2. 4.5.2 DIGITIZED DIE ENGINEERING AND CONNECTED MANUFACTURING FOR SHORTER LEAD TIMES (CAE-TO-SHOPFLOOR INTEGRATION, TOOL TRACEABILITY)54 | | |
      3. 4.5.3 REPLACEMENT AND REFURBISHMENT OF WORN DIES AND MOLDS IN MATURE VEHICLE AND COMPONENT LINES TO RESTORE OEE AND SCRAP RATES55 | | |
      4. 4.5.4 PRECISION TOOLING SUPPLY FOR ELECTRIC-VEHICLE AND POWERTRAIN COMPONENTS (BATTERY ENCLOSURES, THERMAL MANAGEMENT HARDWARE, HIGH-TOLERANCE HOUSINGS)55 | | |
      5. 4.5.5 EXPANSION OF BI-DIRECTIONAL TOOLING FOR HYBRID OPERATIONS (AUTOMATION-READY FIXTURES AND MODULAR DIE SYSTEMS SUPPORTING FLEXIBLE TRANSFER LINES)56 | |
  5. 5 MARKET FACTOR ANALYSIS58 | |
    1. 5.1 VALUE CHAIN ANALYSIS58 | | |
      1. 5.1.1 RAW MATERIAL & COMPONENT SUPPLIERS58 | | |
      2. 5.1.2 TOOL DESIGN, ENGINEERING & SIMULATION59 | | |
      3. 5.1.3 TOOL & DIE MANUFACTURING59 | | |
      4. 5.1.4 DISTRIBUTION, INTEGRATION & OEM COLLABORATION59 | | |
      5. 5.1.5 END USERS & LIFECYCLE SUPPORT SERVICES59 | |
    2. 5.2 Supply Chain Analysis60 | | |
      1. 5.2.1 RAW MATERIAL & PRECISION COMPONENT SUPPLIERS (UPSTREAM)60 | | |
      2. 5.2.2 ENGINEERING, DESIGN & DIGITAL SIMULATION60 | | |
      3. 5.2.3 TOOL & DIE MANUFACTURING (CORE PRODUCTION)60 | | |
      4. 5.2.4 DISTRIBUTION, INTEGRATION & OEM SUPPLY61 | | |
      5. 5.2.5 AFTERMARKET, MAINTENANCE & LIFECYCLE MANAGEMENT (DOWNSTREAM)61 | |
    3. 5.3 PORTER'S FIVE FORCES MODEL61 | | |
      1. 5.3.1 COMPETITIVE RIVALRY – HIGH62 | | |
      2. 5.3.2 THREAT OF NEW ENTRANTS – LOW TO MODERATE62 | | |
      3. 5.3.3 BARGAINING POWER OF SUPPLIERS – MODERATE TO HIGH63 | | |
      4. 5.3.4 BARGAINING POWER OF BUYERS – HIGH63 | | |
      5. 5.3.5 THREAT OF SUBSTITUTES – LOW63 | |
    4. 5.4 Market Trends63 | | |
      1. 5.4.1 RAPID ADOPTION OF INDUSTRY
    5. 4.0 AND DIGITAL TOOLING TECHNOLOGIES63 | | |
      1. 5.4.2 INCREASING ADOPTION OF MODULAR TOOLING AND FLEXIBLE MANUFACTURING SYSTEMS63 | | |
      2. 5.4.3 INCREASING LOCALIZATION, RESHORING, AND REGIONAL SUPPLY CHAIN DEVELOPMENT64 | | |
      3. 5.4.4 GROWING DEMAND FOR HIGH-PRECISION TOOLING FROM AEROSPACE AND DEFENSE MANUFACTURING64 | |
    6. 5.5 Strategic Insights65 | |
    7. 5.6 Product Innovations & Trends65 | | |
      1. 5.6.1 EMERGING PRODUCT FORMATS65 | | |
      2. 5.6.2 INNOVATION CASE STUDIES67 | | | |
        1. 5.6.2.1 CASE STUDY 1: HEADER DIE & TOOL — COMPLETE DIE ASSEMBLY OPTIMIZATION, AUTOMOTIVE FASTENER PRODUCTION67 | | | |
        2. 5.6.2.2 CASE STUDY 2: EXTRUDE HONE — ABRASIVE FLOW MACHINING DIE FINISHING FOR EXTRUSAX (AEROSPACE/AUTOMOTIVE/MARINE EXTRUSION TOOLING)67 | | | |
        3. 5.6.2.3 CASE STUDY 3: OERLIKON BALZERS — BALINIT MAYURA COATING FOR SAXONIA - FRANKE (AUTOMOTIVE/INDUSTRIAL PROGRESSIVE DIE STAMPING)67 | | | |
        4. 5.6.2.4 CASE STUDY 4: TALAN PRODUCTS — PROGRESSIVE DIE RESHORING AND TOOLING CONSOLIDATION ( INDUSTRIAL/BUILDING PRODUCTS)68 | |
    8. 5.7 Regulatory Landscape68 | |
    9. 5.8 Pestle Analysis69 | |
    10. 5.9 Inflation & Cost Impact Analysis70 | |
  6. 6 TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS73 | |
    1. 6.1 Introduction73 | |
    2. 6.2 Stamping or Forming75 | | |
      1. 6.2.1 PROGRESSIVE76 | | |
      2. 6.2.2 TRANSFER76 | | |
      3. 6.2.3 DEEP DRAW76 | | |
      4. 6.2.4 HOT77 | | |
      5. 6.2.5 HYDROFORMING77 | |
    3. 6.3 Die Casting78 | | |
      1. 6.3.1 HPDC78 | | |
      2. 6.3.2 LPDC78 | | |
      3. 6.3.3 GDC + TRIMMING79 | |
    4. 6.4 Extrusion79 | | |
      1. 6.4.1 SOLID80 | | |
      2. 6.4.2 HOLLOW80 | | |
      3. 6.4.3 PORTHOLE80 | | |
      4. 6.4.4 BRIDGE81 | |
    5. 6.5 Forging81 | |
    6. 6.6 Tube or Forming81 | | |
      1. 6.6.1 BENDING82 | | |
      2. 6.6.2 END FORMING82 | | |
      3. 6.6.3 HYDROFORMNG82 | |
  7. 7 TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIAL84 | |
    1. 7.1 Introduction84 | |
    2. 7.2 Ferrous Materials85 | | |
      1. 7.2.1 TOOL STEEL86 | | |
      2. 7.2.2 CARBON STEEL86 | | |
      3. 7.2.3 ALLOY STEEL86 | | |
      4. 7.2.4 CAST IRON87 | |
    3. 7.3 NON-FERROUS MATERIALS87 | | |
      1. 7.3.1 ALUMINUM88 | | |
      2. 7.3.2 ZINC88 | | |
      3. 7.3.3 MAGNESIUM88 | | |
      4. 7.3.4 TITANIUM OR SUPERALLOYS89 | |
  8. 8 TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE90 | |
    1. 8.1 Introduction90 | |
    2. 8.2 Automotive and EV91 | |
    3. 8.3 Aerospace and Defense91 | |
    4. 8.4 Industrial Electrical92 | |
    5. 8.5 Rail or Appliances92 | |
  9. 9 TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER | |
    1. 9.1 INTRODUCTION93 | |
    2. 9.2 Stamping Houses94 | |
    3. 9.3 Die Casters or Foundries94 | |
    4. 9.4 Extruders95 | |
    5. 9.5 Aerospace Primes or Tier | |
    6. 9.6 Contract Tool Rooms96 | |
  10. 10 TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY REGION97 | |
    1. 10.1 Overview97 | |
    2. 10.2 North America98 | | |
      1. 10.2.1 US103 | | |
      2. 10.2.2 CANADA104 | | |
      3. 10.2.3 MEXICO106 | |
    3. 10.3 Europe109 | | |
      1. 10.3.1 GERMANY114 | | |
      2. 10.3.2 UK116 | | |
      3. 10.3.3 FRANCE118 | | |
      4. 10.3.4 RUSSIA119 | | |
      5. 10.3.5 ITALY121 | | |
      6. 10.3.6 SPAIN123 | | |
      7. 10.3.7 REST OF EUROPE125 | |
    4. 10.4 Asia Pacific128 | | |
      1. 10.4.1 CHINA133 | | |
      2. 10.4.2 INDIA134 | | |
      3. 10.4.3 JAPAN136 | | |
      4. 10.4.4 SOUTH KOREA138 | | |
      5. 10.4.5 MALAYSIA140 | | |
      6. 10.4.6 THAILAND142 | | |
      7. 10.4.7 INDONESIA144 | | |
      8. 10.4.8 REST OF APAC146 | |
    5. 10.5 SOUTH AMERICA148 | | |
      1. 10.5.1 BRAZIL152 | | |
      2. 10.5.2 ARGENTINA154 | | |
      3. 10.5.3 REST OF SOUTH AMERICA156 | |
    6. 10.6 Middle EAST & AFRICA158 | | |
      1. 10.6.1 GCC COUNTRIES163 | | |
      2. 10.6.2 SOUTH AFRICA165 | | |
      3. 10.6.3 REST OF MEA167 | |
  11. 11 COMPETITIVE LANDSCAPE170 | |
    1. 11.1 Introduction170 | |
    2. 11.2 competitor dashboard171 | |
    3. 11.3 Company Market Share Analysis, 2025 (Value)172 | |
    4. 11.4 COMPARATIVE ANALYSIS: KEY PLAYERS FINANCIAL173 | |
    5. 11.5 Key Developments & Growth Strategies174 | | |
      1. 11.5.1 PRODUCT LAUNCH/PRODUCT EXPANSION/INVESTMENT/INNOVATIONS174 | | |
      2. 11.5.2 PARTNERSHIP/ACQUISITION/COLLABORATION174 | |
  12. 12 COMPANY PROFILES175 | |
    1. 12.1 PRECIMAX ENGINEERS175 | | |
      1. 12.1.1 COMPANY OVERVIEW175 | | |
      2. 12.1.2 FINANCIAL OVERVIEW176 | | |
      3. 12.1.3 PRODUCTS OFFERED176 | | |
      4. 12.1.4 KEY DEVELOPMENTS177 | | |
      5. 12.1.5 SWOT ANALYSIS177 | | |
      6. 12.1.6 KEY STRATEGIES178 | |
    2. 12.2 Sandhar Technologies Limited179 | | |
      1. 12.2.1 COMPANY OVERVIEW179 | | |
      2. 12.2.2 FINANCIAL OVERVIEW180 | | |
      3. 12.2.3 PRODUCT OFFERED181 | | |
      4. 12.2.4 KEY DEVELOPMENTS182 | | |
      5. 12.2.5 SWOT ANALYSIS182 | | |
      6. 12.2.6 KEY STRATEGIES183 | |
    3. 12.3 RA Global Tech Solutions184 | | |
      1. 12.3.1 COMPANY OVERVIEW184 | | |
      2. 12.3.2 FINANCIAL OVERVIEW185 | | |
      3. 12.3.3 PRODUCTS OFFERED185 | | |
      4. 12.3.4 KEY DEVELOPMENTS185 | | |
      5. 12.3.5 SWOT ANALYSIS186 | | |
      6. 12.3.6 KEY STRATEGIES186 | |
    4. 12.4 Inspire187 | | |
      1. 12.4.1 COMPANY OVERVIEW187 | | |
      2. 12.4.2 FINANCIAL OVERVIEW188 | | |
      3. 12.4.3 PRODUCTS OFFERED188 | | |
      4. 12.4.4 KEY DEVELOPMENTS189 | | |
      5. 12.4.5 SWOT ANALYSIS189 | | |
      6. 12.4.6 KEY STRATEGIES189 | |
    5. 12.5 Bharat Forge190 | | |
      1. 12.5.1 COMPANY OVERVIEW190 | | |
      2. 12.5.2 FINANCIAL OVERVIEW191 | | |
      3. 12.5.3 SERVICES OFFERED191 | | |
      4. 12.5.4 KEY DEVELOPMENTS192 | | |
      5. 12.5.5 SWOT ANALYSIS193 | | |
      6. 12.5.6 KEY STRATEGIES193 | |
    6. 12.6 Raj Tools & Stamping Pvt. Ltd.194 | | |
      1. 12.6.1 COMPANY OVERVIEW194 | | |
      2. 12.6.2 FINANCIAL OVERVIEW195 | | |
      3. 12.6.3 PRODUCT OFFERED195 | | |
      4. 12.6.4 KEY DEVELOPMENTS196 | | |
      5. 12.6.5 SWOT ANALYSIS197 | | |
      6. 12.6.6 KEY STRATEGIES197 | |
    7. 12.7 STAMPITALIA SRL198 | | |
      1. 12.7.1 COMPANY OVERVIEW198 | | |
      2. 12.7.2 FINANCIAL OVERVIEW199 | | |
      3. 12.7.3 PRODUCTS OFFERED199 | | |
      4. 12.7.4 KEY DEVELOPMENTS200 | | |
      5. 12.7.5 SWOT ANALYSIS201 | | |
      6. 12.7.6 KEY STRATEGIES201 | |
    8. 12.8 PCS STAMPI (P.C.S.)202 | | |
      1. 12.8.1 COMPANY OVERVIEW202 | | |
      2. 12.8.2 FINANCIAL OVERVIEW203 | | |
      3. 12.8.3 PRODUCTS OFFERED203 | | |
      4. 12.8.4 KEY DEVELOPMENTS203 | | |
      5. 12.8.5 SWOT ANALYSIS204 | | |
      6. 12.8.6 KEY STRATEGIES204 | |
    9. 12.9 Alto S.R.L.205 | | |
      1. 12.9.1 COMPANY OVERVIEW205 | | |
      2. 12.9.2 FINANCIAL OVERVIEW206 | | |
      3. 12.9.3 PRODUCT OFFERED207 | | |
      4. 12.9.4 KEY DEVELOPMENTS207 | | |
      5. 12.9.5 SWOT ANALYSIS208 | | |
      6. 12.9.6 KEY STRATEGIES208 | |
    10. 12.10 Carlson Tool & Manufacturing Corp.209 | | |
      1. 12.10.1 COMPANY OVERVIEW209 | | |
      2. 12.10.2 FINANCIAL OVERVIEW210 | | |
      3. 12.10.3 PRODUCT OFFERED210 | | |
      4. 12.10.4 KEY DEVELOPMENTS211 | | |
      5. 12.10.5 SWOT ANALYSIS211 | | |
      6. 12.10.6 KEY STRATEGIES211 | |
  13. 13 DATA CITATIONS212 | | LIST OF TABLES | |
    1. TABLE 1LEADING COMPANIES24 | |
    2. TABLE 2QFD MODELING FOR MARKET SHARE ASSESSMENT40 | |
  14. TABLE 3TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)73 | |
  15. TABLE 4TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIAL, 2019-2035 (USD MILLION)84 | |
  16. TABLE 5TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)90 | |
  17. TABLE 6TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USER, 2019-2035 (USD MILLION)93 | |
  18. TABLE 7TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY REGION, 2019-2035 (USD MILLION)97 | |
  19. TABLE 8NORTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2019-2035 (USD MILLION)99 | |
  20. TABLE 9NORTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)100 | |
  21. TABLE 10NORTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)101 | |
  22. TABLE 11NORTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)102 | |
  23. TABLE 12NORTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)102 | |
  24. TABLE 13US TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)103 | |
  25. TABLE 14US TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)103 | |
  26. TABLE 15US TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)104 | |
  27. TABLE 16US TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)104 | |
  28. TABLE 17CANADA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)104 | |
  29. TABLE 18CANADA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)105 | |
  30. TABLE 19CANADA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)106 | |
  31. TABLE 20CANADA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)106 | |
  32. TABLE 21MEXICO TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)106 | |
  33. TABLE 22MEXICO TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)107 | |
  34. TABLE 23US TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)107 | |
  35. TABLE 24US TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)108 | |
  36. TABLE 25EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2019-2035 (USD MILLION)110 | |
  37. TABLE 26EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)111 | |
  38. TABLE 27EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)112 | |
  39. TABLE 28EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)112 | |
  40. TABLE 29EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)113 | |
  41. TABLE 30GERMANY TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)114 | |
  42. TABLE 31GERMANY TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)114 | |
  43. TABLE 32GERMANY TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)115 | |
  44. TABLE 33GERMANY TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)115 | |
  45. TABLE 34 UK TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 116 | |
  46. TABLE 35 UK TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 116 | |
  47. TABLE 36 UK TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 117
  48. TABLE 37 UK TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION) 117 | |
  49. TABLE 38 FRANCE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)118 | |
  50. TABLE 39FRANCE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)118 | |
  51. TABLE 40FRANCE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)119 | |
  52. TABLE 41FRANCE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)119 | |
  53. TABLE 42RUSSIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)119 | |
  54. TABLE 43RUSSIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)120 | |
  55. TABLE 44RUSSIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 121 | |
  56. TABLE 45RUSSIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)121 | |
  57. TABLE 46ITALY TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 121 | |
  58. TABLE 47ITALY TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 122 | |
  59. TABLE 48ITALY TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 123 | |
  60. TABLE 49ITALY TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)123 | |
  61. TABLE 50SPAIN TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 123 | |
  62. TABLE 51SPAIN TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 124 | |
  63. TABLE 52SPAIN TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 124 | |
  64. TABLE 53SPAIN TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)125 | |
  65. TABLE 54REST OF EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)125 | |
  66. TABLE 55REST OF EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)126 | |
  67. TABLE 56REST OF EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)126 | |
  68. TABLE 57REST OF EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)127 | |
  69. TABLE 58 ASIA PACIFIC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2019-2035 (USD MILLION) 129 | |
  70. TABLE 59 ASIA PACIFIC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 131 | |
  71. TABLE 60 ASIA-PACIFIC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 131 | |
  72. TABLE 61ASIA-PACIFIC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 132 | |
  73. TABLE 62ASIA-PACIFIC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)132 | |
  74. TABLE 63CHINA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 133 | |
  75. TABLE 64CHINA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 133 | |
  76. TABLE 65CHINA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 134 | |
  77. TABLE 66CHINA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION) 134 | |
  78. TABLE 67INDIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 134 | |
  79. TABLE 68INDIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 135 | |
  80. TABLE 69INDIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)136 | |
  81. TABLE 70INDIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION) 136 | |
  82. TABLE 71JAPAN TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 136 | |
  83. TABLE 72JAPAN TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 137 | |
  84. TABLE 73JAPAN TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 138 | |
  85. TABLE 74JAPAN TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION) 138 | |
  86. TABLE 75 SOUTH KOREA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 138 | |
  87. TABLE 76 SOUTH KOREA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)139 | |
  88. TABLE 77 SOUTH KOREA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 139 | |
  89. TABLE 78 SOUTH KOREA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)140 | |
  90. TABLE 79MALAYSIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 140 | |
  91. TABLE 80MALAYSIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 141 | |
  92. TABLE 81MALAYSIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 141 | |
  93. TABLE 82MALAYSIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION) 142 | |
  94. TABLE 83THAILAND TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 142 | |
  95. TABLE 84THAILAND TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 143 | |
  96. TABLE 85THAILAND TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 143 | |
  97. TABLE 86THAILAND TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION) 144 | |
  98. TABLE 87INDONESIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION) 144 | |
  99. TABLE 88INDONESIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)145 | |
  100. TABLE 89INDONESIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 145 | |
  101. TABLE 90INDONESIA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)145 | |
  102. TABLE 91REST OF APAC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)146 | |
  103. TABLE 92REST OF APAC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)147 | |
  104. TABLE 93REST OF APAC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)147 | |
  105. TABLE 94REST OF APAC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)147 | |
  106. TABLE 95SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2019-2035 (USD MILLION)149 | |
  107. TABLE 96SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)150 | |
  108. TABLE 97SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)151 | |
  109. TABLE 98SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)151 | |
  110. TABLE 99SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)152 | |
  111. TABLE 100BRAZIL TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)152 | |
  112. TABLE 101BRAZIL TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION) 153 | |
  113. TABLE 102BRAZIL TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION) 153 | |
  114. TABLE 103BRAZIL TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)154 | |
  115. TABLE 104ARGENTINA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)154 | |
  116. TABLE 105ARGENTINA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)155 | |
  117. TABLE 106ARGENTINA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)155 | |
  118. TABLE 107ARGENTINA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)155 | |
  119. TABLE 108REST OF SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)156 | |
  120. TABLE 109REST OF SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)157 | |
  121. TABLE 110REST OF SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)157 | |
  122. TABLE 111REST OF SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)157 | |
  123. TABLE 112MIDDLE EAST & AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2019-2035 (USD MILLION)159 | |
  124. TABLE 113MIDDLE EAST & AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)161 | |
  125. TABLE 114MIDDLE EAST & AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)162 | |
  126. TABLE 115MIDDLE EAST & AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)162 | |
  127. TABLE 116MIDDLE EAST & AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)163 | |
  128. TABLE 117GCC COUNTRIES TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)163 | |
  129. TABLE 118GCC COUNTRIES TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)164 | |
  130. TABLE 119GCC COUNTRIES TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)164 | |
  131. TABLE 120GCC COUNTRIES TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)165 | |
  132. TABLE 121SOUTH AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)165 | |
  133. TABLE 122SOUTH AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)166 | |
  134. TABLE 123SOUTH AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)166 | |
  135. TABLE 124SOUTH AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION)166 | |
  136. TABLE 125REST OF MEA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2019-2035 (USD MILLION)167 | |
  137. TABLE 126REST OF MEA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIALS, 2019-2035 (USD MILLION)168 | |
  138. TABLE 127REST OF MEA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2019-2035 (USD MILLION)168 | |
  139. TABLE 128 REST OF MEA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY CUSTOMER, 2019-2035 (USD MILLION) 169 | |
  140. TABLE 129 COMPARATIVE ANALYSIS: KEY PLAYERS FINANCIAL (USD MILLION) 173 | |
  141. TABLE 130 PRODUCT LAUNCH/PRODUCT EXPANSION/INVESTMENT/INNOVATIONS174 | |
    1. TABLE 131PARTNERSHIP/ACQUISITION/COLLABORATION 174 | |
  142. TABLE 132 PRECIMAX ENGINEERS: PRODUCTS OFFERED 176 | |
  143. TABLE 133 SANDHAR TECHNOLOGIES LIMITED: PRODUCT OFFERED 181 | |
  144. TABLE 134 SANDHAR TECHNOLOGIES LIMITED: KEY DEVELOPMENTS 182 | |
  145. TABLE 135 RA GLOBAL TECH SOLUTIONS: PRODUCTS OFFERED185 | |
  146. TABLE 136 INSPIRE: PRODUCTS OFFERED 188 | |
  147. TABLE 137 BHARAT FORGE: SERVICES OFFERED191 | |
  148. TABLE 138 BHARAT FORGE: KEY DEVELOPMENTS 192 | |
  149. TABLE 139 RAJ TOOLS & STAMPING PVT. LTD.: PRODUCT OFFERED 195 | |
  150. TABLE 140 RAJ TOOLS & STAMPING PVT. LTD.: KEY DEVELOPMENTS196 | |
  151. TABLE 141 STAMPITALIA SRL: PRODUCTS OFFERED 199 | |
  152. TABLE 142 STAMPITALIA SRL: KEY DEVELOPMENTS 200 | |
  153. TABLE 143 PCS STAMPI: PRODUCTS OFFERED 203 | |
    1. TABLE 144ALTO S.R.L.: PRODUCT OFFERED207 | |
    2. TABLE 145CARLSON TOOL & MANUFACTURING CORP.: PRODUCT OFFERED210 | | LIST OF FIGURES | |
    3. FIGURE 1TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET: ESTIMATIONS AND FORECASTS (2019-2035)22 | |
    4. FIGURE 2TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET: STRUCTURE27 | |
    5. FIGURE 3TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET: MARKET GROWTH FACTOR ANALYSIS (2019-2035) 43 | |
    6. FIGURE 4DRIVER IMPACT ANALYSIS (2024-2035)49 | |
    7. FIGURE 5RESTRAINT IMPACT ANALYSIS (2024-2035)53 | |
    8. FIGURE 6OPPORTUNITY IMPACT FORECAST57 | |
    9. FIGURE 7VALUE CHAIN: TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET58 | |
    10. FIGURE 8PORTER'S FIVE FORCES ANALYSIS OF THE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET62 | |
  154. FIGURE 9TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2025 (% SHARE)74 | |
  155. FIGURE 10TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY PROCESS, 2025 & 2035 (USD MILLION)75 | |
  156. FIGURE 11TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIAL, 2025 (% SHARE)85 | |
  157. FIGURE 12TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY MATERIAL, 2025 & 2035 (USD MILLION)85 | |
  158. FIGURE 13TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2025 (% SHARE)90 | |
  159. FIGURE 14TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USE, 2026 & 2035 (USD MILLION)91 | |
  160. FIGURE 15TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USER, 2025 (% SHARE)93 | |
  161. FIGURE 16TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY END USER, 2025 & 2035 (USD MILLION)94 | |
  162. FIGURE 17TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY REGION, 2025 (% SHARE)97 | |
  163. FIGURE 18TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY REGION, 2025 & 2035 (USD MILLION)98 | |
    1. FIGURE 19NORTH AMERICA MARKET ANALYSIS: TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, 2019-2035(USD MILLION)99 | |
  164. FIGURE 20NORTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 (% SHARE) 100 | |
  165. FIGURE 21NORTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 & 2035 (USD MILLION) 100 | |
  166. FIGURE 22 EUROPE MARKET ANALYSIS: TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, 2019-2035(USD MILLION) 109 | |
  167. FIGURE 23 EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 (% SHARE) 110 | |
  168. FIGURE 24EUROPE TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 & 2035 (USD MILLION) 111 | |
    1. FIGURE 25ASIA-PACIFIC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET ANALYSIS: 2019-2035 (USD MILLION) 129 | |
  169. FIGURE 26ASIA PACIFIC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 (% SHARE)130 | |
  170. FIGURE 27ASIA PACIFIC TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 & 2035 (USD MILLION)130 | |
    1. FIGURE 28SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET ANALYSIS: 2019-2035 (USD MILLION)148 | |
  171. FIGURE 29SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 (% SHARE) 149 | |
  172. FIGURE 30SOUTH AMERICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 & 2035 (USD MILLION)150 | |
    1. FIGURE 31MIDDLE EAST & AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET ANALYSIS: 2019-2035 (USD MILLION)159 | |
  173. FIGURE 32MIDDLE EAST & AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 (% SHARE)160 | |
  174. FIGURE 33MIDDLE EAST & AFRICA TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET, BY COUNTRY, 2025 & 2035 (USD MILLION) 161 | |
    1. FIGURE 35GLOBAL TOOLING AND DIES FOR AUTOMOTIVE, AEROSPACE AND INDUSTRIAL MARKET PLAYERS : COMPETITIVE ANALSIS, 2025 (% SHARE)172 | |
    2. FIGURE 36PRECIMAX ENGINEERS : SWOT ANALYSIS177 | |
    3. FIGURE 37SANDHAR TECHNOLOGIES LIMITED : FINANCIAL OVERVIEW SNAPSHOT 180 | |
    4. FIGURE 38SANDHAR TECHNOLOGIES LIMITED : SWOT ANALYSIS182 | |
    5. FIGURE 39RA GLOBAL TECH SOLUTIONS: SWOT ANALYSIS186 | |
    6. FIGURE 40INSPIRE: SWOT ANALYSIS189 | |
    7. FIGURE 41BHARAT FORGE (KALYANI GROUP) : FINANCIAL OVERVIEW SNAPSHOT191 | |
    8. FIGURE 42BHARAT FORGE: SWOT ANALYSIS193 | |
    9. FIGURE 43RAJ TOOLS & STAMPING PVT. LTD.: SWOT ANALYSIS197 | |
    10. FIGURE 44STAMPITALIA SRL : SWOT ANALYSIS201 | |
    11. FIGURE 45PCS STAMPI: SWOT ANALYSIS204 | |
    12. FIGURE 46ALTO S.R.L. (STANDARD LIFE PLC): FINANCIAL OVERVIEW SNAPSHOT 206 | |
    13. FIGURE 47ALTO S.R.L.: SWOT ANALYSIS208 | |
    14. FIGURE 48CARLSON TOOL & MANUFACTURING CORP.: SWOT ANALYSIS211

Market Segmentation Tab

  • Global Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Global Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Global Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Global Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms

Tooling and Dies for Automotive, Aerospace and Industrial Market Regional Outlook (USD Million, 2019-2035)

  • North America Outlook (USD Million, 2019-2035)
  • North America Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • North America Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • North America Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • North America Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • US Outlook (USD Million, 2019-2035)
  • US Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • US Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • US Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • US Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Canada Outlook (USD Million, 2019-2035)
  • Canada Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Canada Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Canada Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Canada Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Mexico Outlook (USD Million, 2019-2035)
  • Mexico Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Mexico Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Mexico Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Mexico Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Europe Outlook (USD Million, 2019-2035)
  • Europe Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Europe Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Europe Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Europe Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Germany Outlook (USD Million, 2019-2035)
  • Germany Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Germany Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Germany Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Germany Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • UK Outlook (USD Million, 2019-2035)
  • Uk Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Uk Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Uk Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Uk Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • France Outlook (USD Million, 2019-2035)
  • France Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • France Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • France Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • France Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Russia Outlook (USD Million, 2019-2035)
  • Russia Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Russia Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Russia Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Russia Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Italy Outlook (USD Million, 2019-2035)
  • Italy Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Italy Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Italy Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Italy Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Spain Outlook (USD Million, 2019-2035)
  • Spain Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Spain Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Spain Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Spain Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Rest Of Europe Outlook (USD Million, 2019-2035)
  • Rest Of Europe Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Rest Of Europe Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Rest Of Europe Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Rest Of Europe Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Asia-Pacific Outlook (USD Million, 2019-2035)
  • Asia-Pacific Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Asia-Pacific Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Asia-Pacific Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Asia-Pacific Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • China Outlook (USD Million, 2019-2035)
  • China Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • China Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • China Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • China Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • India Outlook (USD Million, 2019-2035)
  • India Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • India Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • India Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • India Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Japan Outlook (USD Million, 2019-2035)
  • Japan Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Japan Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Japan Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Japan Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • South Korea Outlook (USD Million, 2019-2035)
  • South Korea Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • South Korea Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • South Korea Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • South Korea Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Malaysia Outlook (USD Million, 2019-2035)
  • Malaysia Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Malaysia Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Malaysia Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Malaysia Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Thailand Outlook (USD Million, 2019-2035)
  • Thailand Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Thailand Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Thailand Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Thailand Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Indonesia Outlook (USD Million, 2019-2035)
  • Indonesia Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Indonesia Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Indonesia Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Indonesia Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Rest of Asia-Pacific Outlook (USD Million, 2019-2035)
  • Rest of Asia-Pacific Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Rest of Asia-Pacific Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Rest of Asia-Pacific Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Rest of Asia-Pacific Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • South America Outlook (USD Million, 2019-2035)
  • South America Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • South America Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • South America Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • South America Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Brazil Outlook (USD Million, 2019-2035)
  • Brazil Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Brazil Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Brazil Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Brazil Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Argentina Outlook (USD Million, 2019-2035)
  • Argentina Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Argentina Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Argentina Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Argentina Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Rest of South America Outlook (USD Million, 2019-2035)
  • Rest of South America Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Rest of South America Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Rest of South America Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Rest of South America Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Middle East & Africa Outlook (USD Million, 2019-2035)
  • Middle East & Africa Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Middle East & Africa Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Middle East & Africa Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Middle East & Africa Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • GCC Countries Outlook (USD Million, 2019-2035)
  • GCC Countries Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • GCC Countries Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • GCC Countries Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • GCC Countries Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • South Africa Outlook (USD Million, 2019-2035)
  • South Africa Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • South Africa Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • South Africa Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • South Africa Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms
  • Rest of Middle East & Africa Outlook (USD Million, 2019-2035)
  • Rest of Middle East & Africa Tooling and Dies for Automotive, Aerospace and Industrial Market, By Process Outlook (USD Million, 2019-2035)
  • Stamping or Forming
  • Progressive
  • Transfer
  • Deep Draw
  • Hot
  • Hydroforming
  • Die Casting
  • HPDC
  • LPDC
  • GDC + trimming
  • Extrusion
  • Solid
  • Hollow
  • Porthole
  • Bridge
  • Forging
  • Tube or Forming
  • Bending Dies
  • End Forming Dies
  • Tube Hydroforming Dies
  • Rest of Middle East & Africa l Tooling and Dies for Automotive, Aerospace and Industrial Market by Material Outlook (USD Million, 2019-2035)
  • Ferrous Materials
  • Tool Steel
  • Carbon steel
  • Alloy Steel
  • Cast Iron
  • Non-Ferrous Materials
  • Aluminum
  • Zinc
  • Magnesium
  • Titanium or Superalloys
  • Rest of Middle East & Africa Tooling and Dies for Automotive, Aerospace and Industrial Market by End Use Outlook (USD Million, 2019-2035)
  • Automotive and EV
  • Aerospace and Defense
  • Industrial Electrical
  • Rail or Appliances
  • Rest of Middle East & Africa Tooling and Dies for Automotive, Aerospace and Industrial Market by Customer Outlook (USD Million, 2019-2035)
  • Stamping Houses
  • Die Casters or Foundries
  • Extruders
  • Aerospace Primes or Tier 1
  • Contract Tool Rooms


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.