Tooling Dies for Automotive Aerospace and Industrial Market Summary
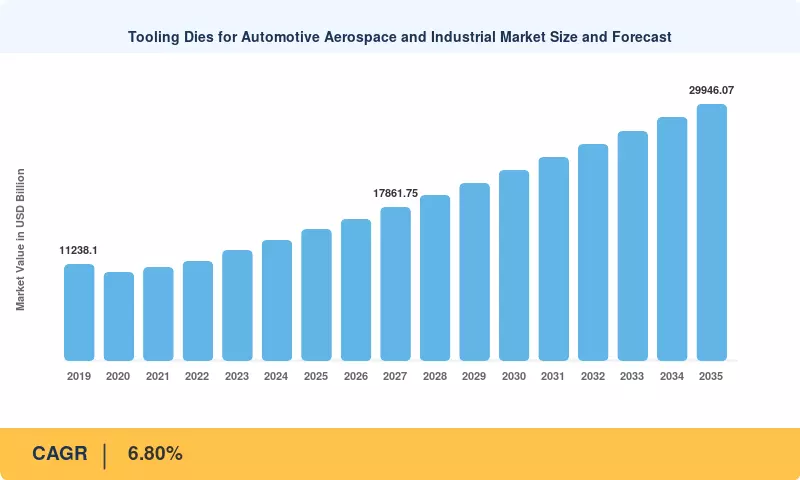
The global Tooling and Dies for Automotive, Aerospace and Industrial Market was valued at USD 15,285.26 Million (USD 15.29 Billion) in 2025, and MRFR estimates the market will open the forecast window at USD 16,538.66 Million in 2026 before reaching USD 29,946.07 Million (USD 29.95 Billion) by 2035, registering a CAGR of 6.80% across 2026–2035. The market has already demonstrated a durable post-pandemic recovery: after contracting 8.60% in 2020 to USD 10,271.62 Million, it compounded at roughly 8.3% annually through the 2023–2025 stretch, with 2023 alone posting 10.76% growth as delayed vehicle platform launches and deferred capital tooling programs released simultaneously. Three structural forces underpin the forecast. First, automotive production growth and vehicle platform/PPAP program demand continues to anchor roughly 60% of tooling consumption, with the Automotive & EV end-use segment worth USD 9,231.01 Million in 2025. Second, rising adoption of lightweighting and high-strength materials is reshaping the tooling mix — non-ferrous tooling applications are expanding at 7.45% against 6.53% for ferrous, and magnesium-related tooling is the single fastest material sub-segment at 8.77%. Third, industrial manufacturing expansion and reshoring/nearshoring of precision components is driving parallel capacity build-outs in North America (7.09% CAGR) and South and Southeast Asia, where India compounds at 9.12% and Indonesia at 7.70%. Corroborating deal activity is visible in the record: Sandhar Technologies infused EUR 915,000 into its Barcelona subsidiary in March 2026 to expand aluminium die-casting capability, while Bharat Forge closed the AAM India Manufacturing acquisition at an equity value of approximately USD 86.73 Million in July 2025.
The defining technology transition in this Tooling and Dies for Automotive, Aerospace and Industrial Market is the migration of value from conventional sheet-metal stamping toward die casting and extrusion tooling built for lightweight structural components. Stamping or forming dies remain the dominant process segment at USD 6,289.90 Million in 2025 (41.15% share), growing at a solid but sub-market 6.52%. Die casting tooling, however, is the fastest-growing top-level process at 8.35% CAGR from USD 3,784.12 Million, led by high-pressure die casting (HPDC) tooling at 8.64% and USD 2,606.79 Million — the direct tooling consequence of megacasting and large structural aluminium castings replacing multi-piece stamped-and-welded assemblies. Extrusion tooling follows at 7.85%, with hollow-profile dies at 8.83% and porthole dies at 8.49%, reflecting demand for battery-enclosure and thermal-management extrusions. Forging dies, by contrast, grow at just 4.38% — the slowest major process — as powertrain forging volumes flatten under electrification. Commercial evidence for this shift is unambiguous in the transaction record: Sandhar Ascast's March 2025 Business Transfer Agreement to acquire Sundaram-Clayton Limited's high- and low-pressure aluminium die casting business at Hosur for USD 19.07 Million marked the group's first entry into HPDC tooling and casting, and Sandhar had already consolidated its dedicated tooling arm into a wholly owned subsidiary in January 2024 to internalise die-development capability.
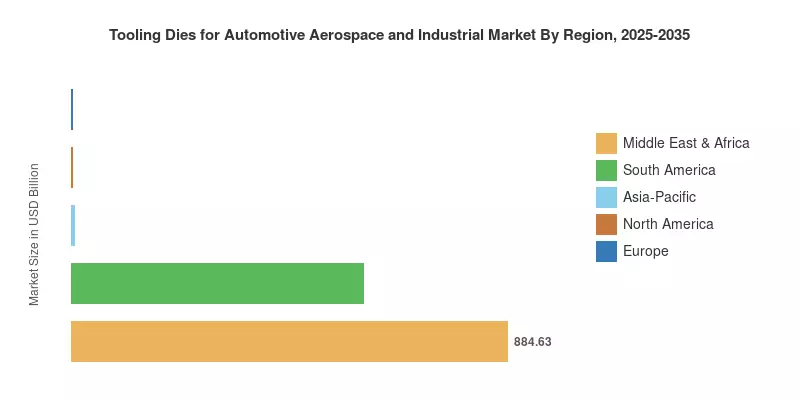
Regionally, Asia-Pacific Tooling and Dies for Automotive, Aerospace and Industrial Market dominates and accelerates simultaneously — an unusual configuration that concentrates both scale and growth in one geography. APAC accounted for USD 7,270.05 Million in 2025, or 47.56% of global revenue, and is the fastest-growing region at 7.44% CAGR, reaching an estimated USD 15,118.6 Million by 2035. Within it, China contributes USD 3,329.68 Million, growing at 8.34%, and India — the fastest-growing country in the study at 9.12% — contributes USD 1,149.58 Million. Europe Tooling and Dies for Automotive, Aerospace and Industrial Market is the second-largest region at USD 3,490.77 Million (22.84% share), but grows most slowly among the majors at 5.59%, weighed down by the UK (3.92%) and Russia (3.12%) even as Germany (6.49%) and Italy (6.01%) hold up. North America ranks third at USD 3,047.50 Million (19.94%) but posts the second-highest regional CAGR at 7.09%, with the US at 7.60% as reshoring incentives pull precision tooling demand back onshore. Looking forward, MRFR expects the APAC revenue share to expand toward 50% by 2035 while Europe's share compresses below 21%, leaving the competitive centre of gravity in the market decisively in Asia even as the highest-margin, highest-tolerance work remains contested between German, Italian, Japanese and North American tool rooms.
Key Report Takeaways
| Segment Dimension | Key Metric | Notes |
|---|---|---|
| Global Market | USD 15,285.26 Mn (2025) → USD 29,946.07 Mn (2035); 6.80% CAGR | Market nearly doubles across the forecast window; 2025 is the base year [1] |
| By Process — Dominant | Stamping or Forming: USD 6,289.90 Mn; 41.15% share (2025) | Progressive dies alone contribute USD 2,461.71 Mn (16.11%) [2] |
| By Process — Fastest | Die Casting: 8.35% CAGR (2026–2035) | HPDC sub-segment fastest at 8.64%; hollow extrusion dies fastest overall sub-segment at 8.83% [2] |
| By Process — Laggard | Forging: 4.38% CAGR from USD 2,127.21 Mn | Slowest major process; exposed to ICE powertrain decline [2] |
| By Material — Dominant | Ferrous Materials: USD 10,984.62 Mn; 71.86% share | Tool steel alone is USD 5,900.11 Mn (38.60%), the largest single sub-segment in the study [3] |
| By Material — Fastest | Non-Ferrous Materials: 7.45% CAGR | Magnesium fastest at 8.77%; aluminium largest non-ferrous at USD 2,542.76 Mn [3] |
| By End Use — Dominant | Automotive & EV: USD 9,231.01 Mn; 60.39% share | Also the fastest end use at 7.18% — scale and growth coincide [4] |
| By End Use — Secondary | Industrial & Electrical: USD 3,049.35 Mn; 19.95% share; 6.11% CAGR | Slower than market average; provides cyclical ballast [4] |
| By Customer — Dominant | Stamping Houses: USD 5,632.46 Mn; 36.85% share; 7.34% CAGR | Largest and fastest customer class simultaneously [5] |
| By Customer — Slowest | Contract Tool Rooms: 5.87% CAGR from USD 2,599.50 Mn | Margin pressure from OEM in-sourcing of die development [5] |
| Regional — Dominant & Fastest | Asia-Pacific: USD 7,270.05 Mn (47.56%); 7.44% CAGR | China USD 3,329.68 Mn; India fastest country at 9.12% [6] |
| Regional — Slowest | South America: 4.07% CAGR from USD 592.30 Mn | Argentina slowest country in study at 2.97% [6] |
| Competitive Structure | Top four players ≈ 37.8% combined share | Highly fragmented; estimated HHI in the 450–600 band [7] |
Market Size and Forecast (2019–2035)
MRFR sizes the Tooling and Dies for Automotive, Aerospace and Industrial Market using a bottom-up market engineering approach anchored on end-use consumption. Tooling demand is modelled as a derived function of downstream unit output — vehicle assembly volumes and platform launch cadence, aerospace build rates, industrial equipment shipments — multiplied by tooling intensity per platform and adjusted for die life, refurbishment cycles and replacement frequency. These bottom-up estimates are triangulated top-down against company revenue disclosures, trade association shipment data, customs trade flows for tool steel and carbide inserts, and capital expenditure disclosures from Tier 1 suppliers. Historical years 2019–2024 are reconstructed from reported and verified data; 2025 is the base year; 2026–2035 are modelled forecasts. Year-on-year growth decelerates gradually across the forecast as the post-pandemic catch-up in deferred tooling programs is absorbed and the base effect compounds.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA