Solar Panel Recycling Market (2026 - 2035)

Solar Panel Recycling Market Research Report By Process (Thermal, Mechanical, Laser), By Panel Type (Crystalline Silicon, Thin Film), By Shelf Life (Normal Loss, Early Loss), By Material Recovered (Glass, Silicon Wafers, Silver, Aluminum, Other Metals) - Forecast to 2035
ID: MRFR/EnP/5238-CR 128 Pages Anshula Mandaokar Last Updated: September 15, 2026
Solar Panel Recycling Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)9.8%
2025 Market SizeUSD 451.5 Million
2035 Market SizeUSD 1,144.6 Million
Key Players
Veolia Environnement SA
First Solar, Inc.
SOLARCYCLE, Inc.
Reiling GmbH & Co. KG
Rinovasol Global Services B.V.
ROSI SAS
Opportunities
  • High-Purity Silicon for Semiconductor-Adjacent Buyers
  • India and Southeast Asia as Greenfield Territory
  • Decommissioning-as-a-Service Bundles

Solar Panel Recycling Market Summary

The Solar Panel Recycling Market closed 2025 at USD 451.5 Million and enters the forecast window at USD 493.4 Million in 2026, expanding to USD 1,144.6 Million by 2035 at a 9.8% CAGR. Two catalysts anchor that trajectory. Europe's producer-responsibility enforcement has converted disposal from a cost centre into a documented material stream, while the U.S. Inflation Reduction Act's 10% domestic-content bonus has made recovered aluminium frames and silicon commercially interesting to module assemblers for the first time [1][3].

Recovery technology is changing quickly. Crushing-and-screening lines built for flat glass are giving way to sequential delamination trains that separate encapsulant, wafer and busbar before shredding, lifting silver capture from roughly 40% to above 85% [4]. Investment follows: European operators committed over USD 310 million to new treatment capacity between 2023 and 2025, much of it targeting end-of-life PV module recycling volumes arriving from 2010-vintage utility farms [2]. The Solar Panel Recycling Market is, in effect, shifting from waste handling to secondary mining.

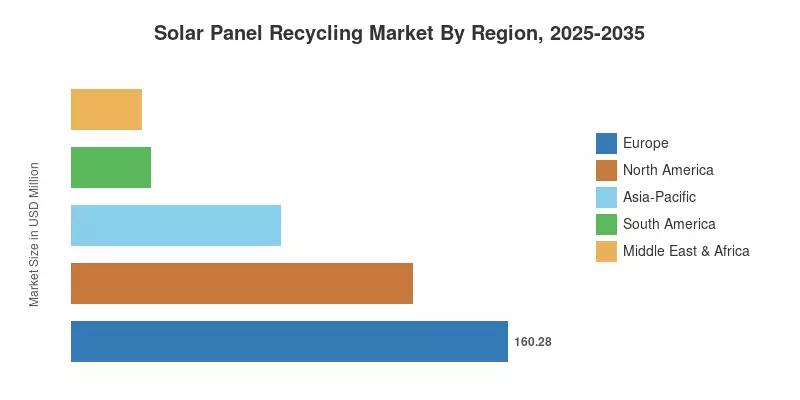
Europe holds 35.5% of global value, built on two decades of mandated collection infrastructure. Asia-Pacific grows fastest at a 17.0% CAGR as China and India confront their first large retirement cohorts. North America ranks second with USD 125.5 million in 2025 revenue, driven by state-level landfill restrictions rather than federal rules [10]. Through 2035, the balance of value migrates toward whoever controls feedstock, not whoever owns the furnace.


Key Report Takeaways

• By Process

  • Mechanical processing held 68.2% of the Solar Panel Recycling Market in 2025, reflecting its low capital intensity and proven throughput.
  • Laser-assisted delamination is forecast to advance at a 15.9% CAGR through 2035 as high-purity silicon commands premium offtake.
  • Thermal treatment generated USD 99.3 million in 2025, concentrated in facilities co-located with existing waste-to-energy assets.

• By Panel Type

  • Crystalline silicon modules represented 82.2% of processed volume in 2025.
  • Thin-film feedstock is projected to grow at an 18.7% CAGR, tracking cadmium telluride retirement schedules.

• By Material Recovered

  • Crystalline silicon modules represented 82.2% of processed volume in 2025.
  • Thin-film feedstock is projected to grow at an 18.7% CAGR, tracking cadmium telluride retirement schedules.
  • Silver recovery within the Solar Panel Recycling Market is expected to rise at a 14.0% CAGR, the fastest of any recovered material.

• By Region

  • Europe led the Solar Panel Recycling Market with a 35.5% share in 2025.
  • Asia-Pacific is forecast to compound at 17.0% between 2026 and 2035.
  • Middle East & Africa contributed USD 25.7 million in 2025, an early-stage but policy-active base.


Market Size and Forecast (2021–2035)

Estimates draw on installed-capacity vintage curves, national waste-registry filings, treatment-plant throughput disclosures, and commodity price series, triangulated against operator interviews and reconciled bottom-up by region. Historical figures reflect reported gate-fee and material-sales revenue; forecast values apply retirement-cohort modelling to the Solar Panel Recycling Market across all five regions.
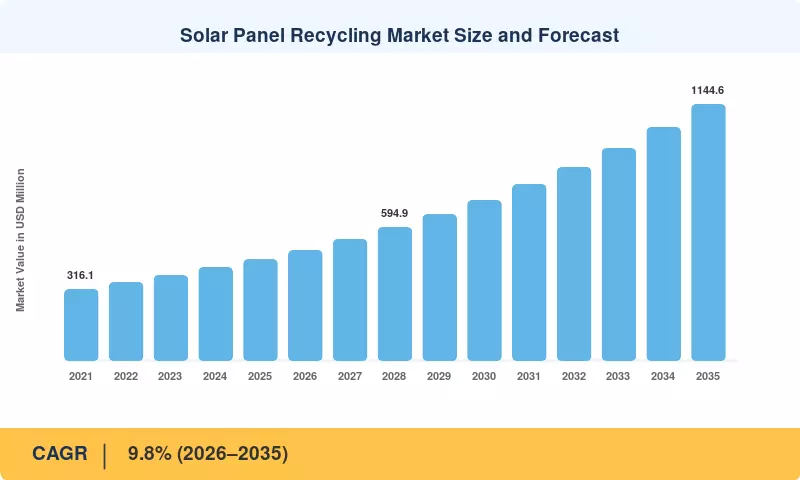
Solar Panel Recycling Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Producer-responsibility enforcement ~2.1 Europe Short-term (≤2 yr)
First-generation module retirement wave ~1.9 Global Medium-term (2–4 yr)
Inflation Reduction Act incentives ~1.6 North America Medium-term (2–4 yr)
Silver and aluminium price strength ~1.5 Global Short-term (≤2 yr)
Critical-mineral reshoring policy ~1.3 North America, Europe Long-term (≥4 yr)
Landfill bans and hazardous classification ~1.1 Europe, Asia-Pacific Medium-term (2–4 yr)
Decommissioning insurance products ~0.9 Global Long-term (≥4 yr)


Regulatory Mandates Convert Waste into Contracted Feedstock

Europe's WEEE solar panel recycling directive obliges producers to fund collection and treatment, and sets a minimum 80% recycling/reuse rate threshold for photovoltaic equipment [1]. That single provision underwrites roughly a third of the Solar Panel Recycling Market by giving processors bankable volume commitments rather than spot tonnage. France's national scheme processed more than 5,500 tonnes in 2023, with eco-fees averaging EUR 0.70 to 0.85 per panel.

The Retirement Cohort Finally Arrives

Modules installed during Europe's 2008–2012 feed-in-tariff boom are reaching the end of 25-year warranties. IRENA projects cumulative global photovoltaic waste of 4 million tonnes by 2030, rising sharply thereafter [2]. Volume, not technology, has been the binding constraint on plant utilisation, and utilisation is what separates profitable operators from stranded capital.

Commodity Economics Improve the Bill of Materials

A ton of crystalline modules contains around 700 kg of glass, 130 kg of aluminum, 30 kg of silicon and about 500 grams of silver. With silver averaging above USD 30 per ounce through 2025, the metal alone supplied almost 28% of revenue from recovered materials [4]. Price exposure cuts both ways. That’s why skilled operators hedge these days.


Industrial Policy Rewards Domestic Loops

The U.S. Department of Energy allocated USD 20 million through its Photovoltaics End-of-Life Action Plan to de-risk recovery technology, and 45X manufacturing credits indirectly reward assemblers who source secondary aluminium [3][5]. Policy has effectively created a buyer for output that previously had none.


Restraints Impact Analysis

Restraint impacts are directional drag estimates, not subtractive coefficients. They quantify relative resistance to growth within the Solar Panel Recycling Market and should be read alongside the drivers in Section 4 rather than netted against them.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Weak unit economics on mechanical lines ~-1.4 Global Medium-term (2–4 yr)
Fragmented collection logistics ~-1.2 North America, South America Short-term (≤2 yr)
No federal producer mandate in the U.S. ~-1.0 North America Long-term (≥4 yr)
Encapsulant delamination limits wafer yield ~-0.8 Global Medium-term (2–4 yr)
Cullet contamination depresses glass value ~-0.6 Europe, Asia-Pacific Short-term (≤2 yr)


Transport Cost Eats the Margin

Materials recovered from a normal 400 W module are worth approximately USD 3 to USD 6, but haulage beyond 400 kilometers can cost USD 2 of that. NREL research puts full-service recycling at USD 15 to USD 45 per module versus landfill expenses near USD 1 to USD 5 [8]. In dispersed areas, viability is not determined by furnace performance but by the density of collecting points.


Voluntary Regimes Produce Volatile Volumes

Only a handful of U.S. states — Washington, California, and New Jersey among them — impose photovoltaic-specific end-of-life obligations, leaving processors to chase unpredictable decommissioning tenders [10]. Capital markets discount that volatility heavily, and several announced facilities have been deferred as a result.

Ethylene Vinyl Acetate Remains Stubborn

The cross-linked encapsulant attaches the glass so securely to the cells that most wafers are broken mechanically. Published pilot data demonstrate that the intact wafer recovery on traditional lines is below 15 % while it is above 85 % on optimized thermal-laser sequences [11]. Mid-tier operators don’t have the capital to close that gap yet.


Solar Panel Recycling Market Opportunities

High-Purity Silicon for Semiconductor-Adjacent Buyers

Recovered wafers refined to 6N purity fetch four to six times the price of metallurgical-grade silicon. Operators who qualify output against solar-grade polysilicon specifications capture margin currently exported to primary producers, and the Solar Panel Recycling Market rewards that qualification with long-term offtake.

India and Southeast Asia as Greenfield Territory

India's CPCB e-waste amendments brought photovoltaic modules into formal registration from 2023, creating regulated volume where none existed [6]. With cumulative installations above 100 GW and a large 2011–2015 vintage cohort maturing, first-mover processors face little incumbent competition.

Decommissioning-as-a-Service Bundles

Asset owners want a single counterparty for de-racking, logistics, treatment and certification. Bundled contracts priced per megawatt rather than per tonne shift risk to the processor but lift realised revenue 20% to 30% versus gate-fee-only models [7].

Recycled-Content Data as a Product

Buyers increasingly demand auditable verification of recycled content for green governmental procurement and business reporting. Selling the verified mass-balance certifications together with the physical material provides a second income line at near-zero marginal cost, and puts participants in the Solar Panel Recycling Market as compliance infrastructure, rather than garbage handlers.


Module Resale Ahead of Material Recovery

Roughly a fifth of retired modules still perform above 80% of nameplate output. Testing-and-resale channels into off-grid African and South American demand generate higher unit value than shredding, while deferring treatment cost.


Solar Panel Recycling Market Future Outlook

Automation Reshapes Plant Economics

Vision-guided sorting and robotic de-framing have reduced labor content per module by about 50% in commissioned pilots, which is significant as labor is the biggest controllable expense in mechanical treatment. According to IEA [2], photovoltaic waste streams are expanding faster than any other renewable-asset category and by 2030, automated lines are expected to be table stakes, and not differentiators, in the Solar Panel Recycling Market.


Feedstock Contracts Become the Real Asset

Capacity is easy to build; supply is not. Expect processors to secure ten-year retirement rights from utility portfolios in the same way smelters contract ore, converting balance-sheet risk into a defensible position and pushing consolidation among operators without such agreements [7].

Recycled Content Enters Product Standards

Draft European ecodesign requirements for photovoltaic modules point toward mandatory recycled-content thresholds later this decade [1]. Once thresholds bind, secondary aluminium and glass gain a regulatory premium independent of commodity cycles, changing how recovery projects are financed.

Critical Minerals Reframe the Conversation

IRENA and DOE analyses both position recovered silicon, silver and indium as domestic supply rather than waste [2][5]. That framing unlocks strategic-reserve funding and offtake guarantees unavailable to conventional recycling, and it is the single most likely source of upside to the 2035 forecast.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
Europe 35.5% share Mandated collection, high-purity silicon, glass loops
North America USD 125.5 Million State mandates, repowering, domestic-content credits
Asia-Pacific 17.0% CAGR (2026–2035) Greenfield capacity, e-waste formalisation
South America 6.4% share Module resale, distributed-generation retirement
Middle East & Africa USD 25.7 Million Utility-scale decommissioning funds, second-life trade
Total USD 451.5 Million

Regional performance across the Solar Panel Recycling Market tracks two variables almost perfectly: the age of the installed base and the presence of an enforceable producer obligation. Where both align, treatment capacity follows within three years.


North America

Country Metric Key Driver
US 86.4% share of region State landfill restrictions and repowering volume
Canada USD 11.7 Million Provincial stewardship programmes
Mexico 12.6% CAGR Utility-scale retirements in Sonora and Baja


Washington State's stewardship rule and California's universal-waste classification have done more to move volume than any federal action, and both create documented chain-of-custody obligations that processors can price. Repowering is the quieter driver: replacing 300 W modules with 600 W units at existing interconnections generates large, clean, single-vintage batches that are far cheaper to treat than mixed feedstock [3][9].

Europe

Country Metric Key Driver
Germany 24.8% share of region Largest legacy installed base
UK USD 19.4 Million Producer compliance schemes
France 11.3% CAGR National collection network density
Italy 13.9% share of region Conto Energia vintage retirements
Spain USD 14.1 Million Utility repowering programmes
Nordic Countries 10.6% CAGR High recovery-rate enforcement
Russia 2.1% share of region Limited formal treatment infrastructure
Rest of Europe USD 18.6 Million Cross-border treatment flows


Europe's advantage in the Solar Panel Recycling Market is procedural. Registration, financing, and reporting obligations were built decades ago for other electrical waste, so photovoltaics slotted into an existing machine. Germany alone hosts several dedicated treatment lines, and CENELEC EN 50625 treatment standards give buyers a common audit reference that reduces contracting friction [1][12].

Asia-Pacific

Country Metric Key Driver
China 41.2% share of region Vast installed base and pilot recovery mandates
India 19.4% CAGR E-waste rules extended to modules
Japan USD 21.8 Million Voluntary industry take-back schemes
South Korea 9.7% share of region Mandatory EPR for photovoltaic equipment
ASEAN 16.1% CAGR Manufacturing scrap and early retirements
Rest of Asia-Pacific USD 8.9 Million Emerging pilot facilities


Growth here is a volume story rather than a policy one. China's cumulative installations passed 600 GW, and even modest early-loss rates produce feedstock exceeding Europe's entire annual throughput. Korea's producer-responsibility scheme, in force since 2023, gives the region its most mature regulatory template, and the Solar Panel Recycling Market in Asia-Pacific will likely converge on that model [6].

South America

Country Metric Key Driver
Brazil 62.8% share of region Distributed-generation fleet ageing
Argentina USD 4.3 Million Utility projects reaching mid-life
Rest of South America 12.4% CAGR Chilean and Colombian pipeline growth


Brazil's distributed-generation boom created millions of rooftop modules with no formal end-of-life pathway, and informal collection currently captures most of the value. Formalisation is the opportunity: national e-waste policy discussions now explicitly reference photovoltaic equipment, which would convert an informal trade into a contracted one [9].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.4% share of region Vision 2030 utility-scale asset base
UAE USD 6.2 Million Early decommissioning funds
South Africa 14.8% CAGR Municipal and mining solar retirements
Egypt 11.7% share of region Benban complex maintenance cycles
Rest of MEA USD 5.8 Million Second-life module imports


Gulf utilities have begun writing decommissioning reserves into new power-purchase agreements, which is unusual for such young fleets and signals institutional learning from wind. Africa, meanwhile, functions largely as a second-life destination, absorbing tested modules that would otherwise be shredded in Europe [7].


Solar Panel Recycling Market By Region, 2025-2035

Solar Panel Recycling Market Segmentation

By Process

Segment Metric (2025) Primary Demand Driver
Mechanical 68.2% share Lowest capital cost per tonne
Thermal USD 99.3 Million Encapsulant removal for higher yields
Laser 15.9% CAGR Intact wafer and busbar recovery


Mechanical processing dominates the Solar Panel Recycling Market with a 68.2% share, as it works with equipment already present at glass and metal recyclers. Its ceiling is quality: crushed output yields mixed cullet and metal fines that fetch commodity-floor pricing. The laser system with a 15.9% CAGR is the fastest-growing. It attacks precisely using selective ablation to lift silver and silicon out intact, and early adopters report material revenue per module two to three times higher despite meaningfully greater capital intensity [5][11].

By Panel Type

Segment Metric Primary Demand Driver
Crystalline Silicon 82.2% share (2025) Dominant share of global installed base
Thin Film 18.7% CAGR Cadmium telluride handling obligations


Crystalline silicon defines the Solar Panel Recycling Market with 82.2% market share as it defines the installed base. Thin film, with a CAGR of 18.7%, grows faster from a small base for a different reason: cadmium content triggers hazardous-waste handling rules that force modules into regulated channels regardless of economics, guaranteeing volume that crystalline streams must compete for [6].

By Shelf Life

Segment Metric Primary Demand Driver
Normal Loss 67.4% share (2025) Warranty-expiry retirement cohorts
Early Loss 14.5% CAGR Hail, transport, and manufacturing defects


Normal Loss modules dominate the Solar Panel Recycling Market by shelf life, accounting for a 67.4% share in 2025. This primary volume is driven by natural end-of-life retirement cohorts—photovoltaic (PV) systems installed during early commercial adoption waves reaching the end of their standard 25-to-30-year operational life and warranty periods. Meanwhile, Early Loss panels represent the fastest-growing recycling stream, projecting a market-leading CAGR of 14.5%.

By Material Recovered

Segment Metric Primary Demand Driver
Glass 51.9% share (2025) Mass dominance in module composition
Silicon Wafers USD 71.2 Million Secondary polysilicon demand
Silver 14.0% CAGR Price strength and contact-paste recovery
Aluminium 11.4% share (2025) Frame recovery with established smelter routes
Other Metals 12.1% CAGR Copper, indium and tin recovery


Glass with 51.9% market share carries the tonnage but not the margin within the Solar Panel Recycling Market, and contamination frequently pushes it toward construction fill rather than container manufacture. Silver, with a 14.0% CAGR, is the fastest-growing, which inverts that relationship entirely — under half a percent of mass, close to a third of recoverable value — which explains why every process innovation of the past three years has targeted busbars and contact paste [4][12].


Competitive Benchmarking

Concentration is moderate. The estimated Herfindahl-Hirschman Index sits near 680, with the top five participants holding roughly 38% to 44% of global revenue. The Solar Panel Recycling Market remains structurally fragmented below that tier, populated by regional operators whose advantage is proximity to feedstock rather than technology. Consolidation is accelerating as scale becomes necessary to fund delamination equipment.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Veolia Environnement SA ~9–12% Dedicated treatment plants, compliance services European incumbent with WEEE-scale logistics
First Solar, Inc. ~8–11% Closed-loop thin-film recovery Vertically integrated manufacturer-recycler
SOLARCYCLE, Inc. ~6–9% High-value material extraction, glass remanufacture U.S. technology leader with utility offtake
Reiling GmbH & Co. KG ~5–8% Glass and silicon separation lines Glass-recycling heritage, German base
Rinovasol Global Services B.V. ~4–6% Module refurbishment and resale Second-life specialist
ROSI SAS ~3–5% High-purity silicon and silver recovery Advanced pyrolysis and metallurgy
We Recycle Solar, Inc. ~3–5% Decommissioning and testing services Full-service North American provider
Envaris GmbH ~2–4% Take-back and treatment engineering Compliance-led European operator
Silrec Corporation ~2–4% Delamination and metals reclamation Mid-scale processor with OEM partnerships
PV Industries Pty Ltd ~2–3% Low-emission separation technology Asia-Pacific capacity builder
Echo Environmental Holdings ~1–3% Electronics and photovoltaic recovery Diversified downstream refiner


Recent News & Developments


  • Veolia (November 2024): Extended its French treatment agreement with the national producer-responsibility scheme, adding capacity for early-loss and storm-damaged modules [1].
  • U.S. Department of Energy (September 2024): Awarded funding under the Photovoltaics End-of-Life Action Plan to projects improving silver and silicon recovery yields [3].


  • First Solar (October 2023): Reported continued expansion of its in-house recycling programme, recovering the majority of semiconductor material for reuse in new modules [14].
  • Reiling Group (July 2023): Increased throughput at its German module-treatment site following sustained growth in decommissioned volumes from feed-in-tariff-era installations [12].


Solar Panel Recycling Market Report Scope

Parameter Detail
Market Scope Global collection, treatment and material recovery from retired photovoltaic modules
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 9.8% (2026–2035)
Market Size Checkpoints USD 451.5 Million (2025); USD 493.4 Million (2026); USD 1,144.6 Million (2035)
Fastest Growing Segments Laser process; Thin film panel type; Silver recovery; Asia-Pacific region
Companies Profiled 11 leading participants in the Solar Panel Recycling Market
Valuation Currency USD Million

FAQs

How should asset owners structure vendor contracts in the Solar Panel Recycling Market?
Tie payment to certified mass-balance recovery rates rather than tonnage collected, and require downstream smelter audits. Multi-year framework agreements typically reduce per-module cost by 15% to 20% versus spot decommissioning tenders [7].
Does laser processing justify its capital premium over mechanical lines?
Laser delamination costs roughly 2.5 times more per installed line but lifts wafer-grade silicon yield above 90% and recovers busbar silver intact. Payback depends on silver holding above USD 28 per ounce [15].
Which certifications matter most for buyers entering the Solar Panel Recycling Market?
R2v3 and e-Stewards remain the baseline for downstream due diligence, while EN 50625 governs European treatment quality. Insurers increasingly require at least one before underwriting decommissioning liability [16].
How do repowering projects change feedstock quality?
Repowered modules arrive undamaged in large uniform batches, raising resale value and cutting sorting labour sharply. Roughly 30% of repowering volume is diverted to tested resale rather than material recovery [17].
What slows commissioning of new treatment facilities?
Permitting for thermal off-gas abatement is the usual bottleneck, adding nine to fourteen months in most European jurisdictions. Industrial grid connections for high-temperature furnaces compound the delay [18].
Are there viable business models beyond material sales in the Solar Panel Recycling Market?
Yes. Compliance-fee services, warranty-backed module resale and verified recycled-content certificates now deliver steadier margins than commodity resale, insulating operators from metal price swings [19].
What should investors examine before committing capital?
Feedstock security is the single largest risk. Facilities without contracted multi-year module supply typically run below 45% utilisation, which destroys unit economics regardless of process technology chosen [20].    
Author
Author Author Profile Anshula Mandaokar LinkedIn Team Lead - Research
Anshula Mandaokar holds an academic degree in Chemical Engineering and has been contributing to the field for more than 5 years. She has expertise in Market Research and Business Consulting and serves as a Team Lead for a reputed Market Research firm under the Chemicals and Materials domain spectrum. She has worked on multiple projects, generating explicit results in a quick turnaround time. Her understanding of data interpretation justifies her role as a leader.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory frameworks, technical standards, peer-reviewed engineering journals, and authoritative energy & environmental organizations. Key sources included the US Environmental Protection Agency (EPA) Resource Conservation and Recovery Act (RCRA) databases, EU Waste Electrical and Electronic Equipment (WEEE) Directive 2012/19/EU and national transposition registers, International Renewable Energy Agency (IRENA) End-of-Life Management protocols, International Energy Agency Photovoltaic Power Systems Programme (IEA-PVPS) Task 12 circular economy working groups, Solar Energy Industries Association (SEIA) National PV Recycling Program standards, SolarPower Europe sustainability directives, National Renewable Energy Laboratory (NREL) recycling technology publications, Fraunhofer Institute for Solar Energy Systems (ISE) lifecycle assessment studies, IEEE Journal of Photovoltaics, Progress in Photovoltaics: Research and Applications (Wiley), ScienceDirect Renewable Energy journal archives, World Bank Energy Sector Management Assistance Program (ESMAP) circular economy databases, OECD Environment Directorate hazardous waste statistics, UN Environment Programme International Environmental Technology Centre (IETC) reports, and national environmental protection agency filings from China (MEE), Japan (MOEJ), and India (CPCB). These sources were utilized to collect decommissioning statistics, regulatory compliance data, material recovery efficiency studies, technology process analyses, and waste stream quantification for crystalline silicon (mono/multi), thin-film (CdTe, CIGS, a-Si), and emerging perovskite photovoltaic technologies.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources comprised CEOs, VPs of Sustainability, heads of recycling operations, chief technology officers, and regulatory compliance directors from photovoltaic module manufacturers (First Solar, Hanwha Q Cells, Canadian Solar, Trina Solar, JinkoSolar), dedicated recycling technology providers (ROSI Solar, Reiling Group, SOLARCYCLE, Veolia Environmental Services), and materials recovery specialists (Aurubis, Umicore). Demand-side sources consist of asset managers and decommissioning directors from utility-scale solar farm operators (NextEra Energy, Ørsted, Enel Green Power), EPC contractors specializing in solar repowering (Bechtel, Sterling, and Wilson), procurement leads from independent power producers (IPPs), and environmental compliance officers from commercial and industrial (C&I) rooftop solar portfolio managers. Primary research verified market segmentation in the mechanical, thermal, chemical, and laser recycling processes, verified technology deployment timelines, and obtained insights on the economics of collection logistics, the pricing dynamics of recovered materials (high-purity silicon, silver, aluminum, and tellurium), and the costs of extended producer responsibility (EPR) compliance.

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (32%), Others (28%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and end-of-life (EOL) panel volume analysis. The methodology included:

Identification of 50+ key recycling operators and technology developers across North America, Europe, Asia-Pacific, and Latin America

Process mapping across mechanical shredding/delamination, thermal pyrolysis, chemical etching/leaching, and laser-enabled delamination technologies

Panel-type segmentation analysis covering crystalline silicon (monocrystalline/polycrystalline) representing ~95% of waste stream, and thin-film (CdTe, CIGS) representing specialized high-value recovery streams

Shelf-life categorization distinguishing "early loss" panels (damage, manufacturing defects, repowering cycles <10 years) from "normal loss" panels (standard 25-30 year operational lifecycle)

Material recovery valuation analysis for aluminum frames, glass cullet, high-purity silicon wafers, silver metallization, copper interconnects, and rare earth elements (indium, gallium, tellurium)

Analysis of reported and modeled annual revenues specific to recycling service providers and integrated OEM take-back programs

Coverage of recycling operators representing 65-70% of global installed processing capacity in 2024

Extrapolation using bottom-up (EOL panel volume by country × processing cost per ton/recovered material value by type) and top-down (recycler revenue validation) approaches to derive segment-specific valuations across thermal, mechanical, chemical, and laser process categories

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















