Shopping Application Market Summary
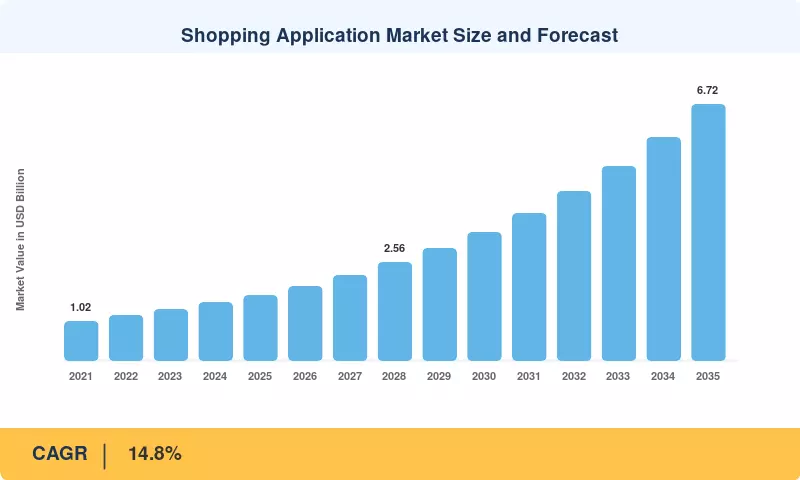
The Shopping Application Market was valued at USD 1.71 Billion in 2025 and is projected to reach USD 1.94 Billion in 2026 before climbing to USD 6.72 Billion by F2035, a CAGR of 14.8% over 2026–2035. Two catalysts anchor that trajectory. The EU Digital Markets Act, enforceable since March 2024, forced gatekeepers to permit alternative app distribution and payment routes, with fines of up to 10% of global turnover for non-compliance [8]. In the United States, the April 2025 Epic v. Apple order barred commissions on external purchase links, reshaping app economics for retailers [9].
Underneath the regulatory shift, the technology stack is being rebuilt. Monolithic, on-premise storefront software is giving way to cloud-native, API-first architectures, cross-platform frameworks, and generative AI assistants that handle discovery and support. Shopify alone processed USD 292.3 billion in gross merchandise volume in 2024, much of it through apps and headless storefronts built on its platform [7]. Retailers now treat the app as a data-rich loyalty channel rather than a mobile copy of the website.
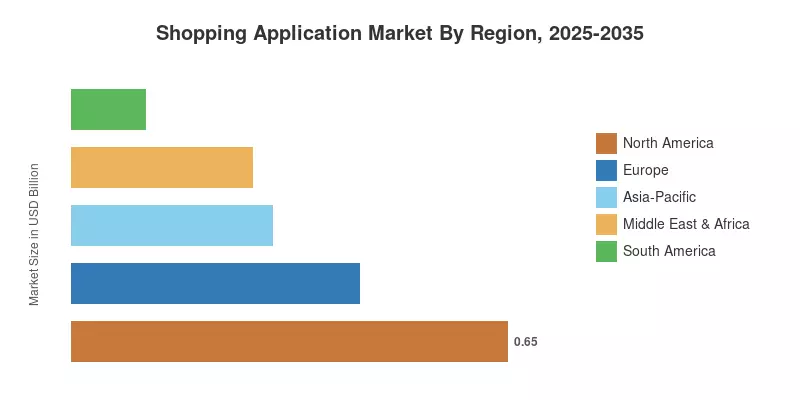
North America leads the Shopping Application Market with a 37.8% share in 2025, supported by high smartphone spend per user and mature retail media budgets. Asia-Pacific is the fastest-growing region at a 17.3% CAGR, driven by real-time payments and super-app ecosystems in India, China, and Southeast Asia. Europe ranks second at USD 0.43 billion, shaped by privacy and platform regulation. Over the forecast window, growth will tilt steadily toward emerging economies and AI-native buying journeys.
Key Report Takeaways
• By Platform
- Android held a 59.9% share of the Shopping Application Market in 2025, supported by affordable handsets across emerging economies.
- Web/Progressive Web Apps are forecast to expand at a 17.1% CAGR as merchants seek fee-free direct funnels.
• By Business Model
- B2C Marketplace accounted for a 50.6% share in 2025 on the strength of network effects and deep catalogs.
- Subscription and Fee-Based Apps lead growth at a 17.2% CAGR through 2035.
• By End User
- Large Enterprises captured a 53.4% share of the Shopping Application Market in 2025.
- Small and Medium Enterprises post the fastest expansion at a 16.4% CAGR, enabled by no-code storefront tools.
• By Deployment Model
- Cloud-Based deployments held a 64.5% share in 2025.
- Hybrid configurations are set to grow at a 16.3% CAGR as data-sovereignty rules tighten.
• By Region
- North America led with a 37.8% share in 2025.
- Asia-Pacific is the fastest-growing region at a 17.3% CAGR.
- Europe generated USD 0.43 Billion in 2025.
Market Size and Forecast (2021–2035)
Market Research Future sized the Shopping Application Market by combining vendor revenue mapping for platform, licensing, and subscription income with demand-side indicators such as app installs, active users, and retailer technology budgets. Historical values were reconciled against public filings and national e-commerce statistics, including US Census quarterly retail data [17], while forecasts reflect scenario modeling of payment adoption, regulation, and AI integration.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



