School Bus Market (2026 - 2035)

School Bus Market Research Report By Propulsion Type (Diesel, Battery-Electric, Gasoline, CNG / Propane, Hybrid / Other), By Body Type (Type A, Type B, Type C (Conventional), Type D (Transit-Style)), By End User (Public School Districts, Private Contractors, Private and Charter Schools), By Seating Capacity (Less than or equal to 30 Seats, 31–60 Seats, More than 60 Seats) - Forecast to 2035
ID: MRFR/AT/24929-HCR 100 Pages Shubham Munde, Swapnil Palwe Last Updated: October 05, 2026
School Bus Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.8%
2025 Market SizeUSD 22.4 Billion
2035 Market SizeUSD 39.6 Billion
Key Players
Blue Bird Corporation
Thomas Built Buses
IC Bus
Lion Electric
Yutong Bus
Zhengzhou Nissan / Ankai
Opportunities
  • Vehicle-to-Grid Revenue Streams
  • Emerging Market First-Fleet Demand
  • Data and Subscription Services

School Bus Market Summary

The School Bus Market closed 2025 at roughly USD 22.4 billion and enters the forecast window at USD 23.7 billion in 2026, tracking toward USD 39.6 billion by 2035 at a 5.8% CAGR. Two catalysts anchor that trajectory. The U.S. Environmental Protection Agency's Clean School Bus Program committed USD 5 billion between 2022 and 2026 under the Infrastructure Investment and Jobs Act [1], while India's PM e-Bus Sewa scheme and China's provincial fleet renewal mandates pulled procurement forward across Asia. Aging fleets do the rest of the work — the average North American yellow bus is over ten years old, and replacement cycles are non-negotiable when safety codes tighten.

Diesel remains the workhorse, but the powertrain mix is shifting faster than most fleet managers expected a decade ago. Districts are retiring pre-2010 diesel units and replacing them with battery-electric and gaseous-fuel platforms, and the School Bus Market now sees electrified units account for a meaningful slice of new orders. Roughly USD 3.2 billion in EPA rebate awards had been obligated by late 2025 [1], with vehicle-to-grid pilots in Virginia and California turning parked fleets into dispatchable storage assets.

Regionally, the picture is lopsided. North America commands 61.5% of the School Bus Market on the strength of a 480,000-plus vehicle installed base and statutory yellow-bus requirements. Asia-Pacific grows fastest at 7.4% CAGR as urban school transport formalizes across India, China, and Southeast Asia. Europe, the second-largest region, is driven less by dedicated yellow buses and more by contracted municipal transport under Clean Vehicles Directive procurement quotas [4]. The next decade rewards manufacturers who can serve both a replacement market and a first-time-buyer market at once.


Key Report Takeaways

• By Propulsion Type

  • Diesel powertrains retain 68.4% of School Bus Market volume in 2025, though the share erodes each forecast year
  • Battery-electric units post the strongest expansion in the School Bus Market at 19.6% CAGR through 2035
  • Alternative gaseous-fuel platforms generate USD 2.1 billion in 2025 revenue

• By End User

  • Public school district procurement contributes USD 15.9 billion in 2025
  • Private contractor and charter operators expand at 6.6% CAGR
  • Aftermarket safety retrofit and telematics services hold 8.2% of total value

• By Region

  • North America holds 61.5% share, anchored by federal rebate cycles
  • Asia-Pacific advances at 7.4% CAGR on urban transport formalization
  • Middle East & Africa contributes USD 0.7 billion in 2025


Market Size and Forecast (2021–2035)

Sizing blends OEM unit shipments, average selling prices by body class, government procurement disclosures, and district-level fleet registries, reconciled against public filings from listed manufacturers and cross-checked with federal grant obligation data. Historical values reflect actual delivered units rather than orders booked, which matters because chassis backlogs distorted 2022–2023 order books well beyond delivery reality.
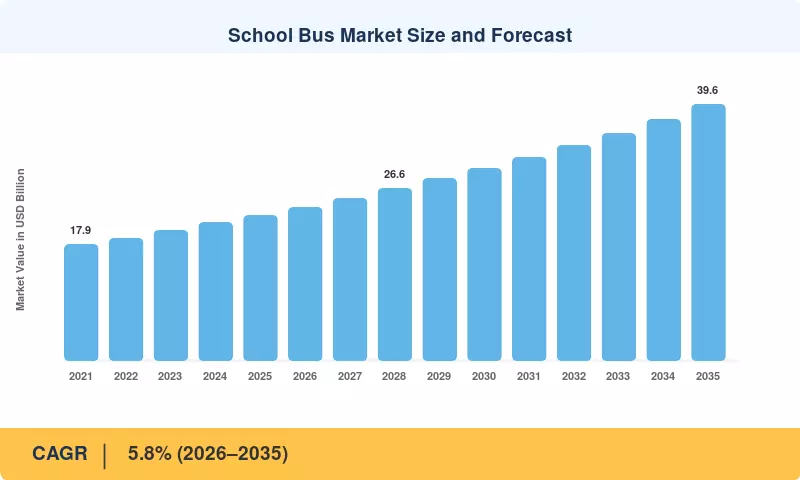
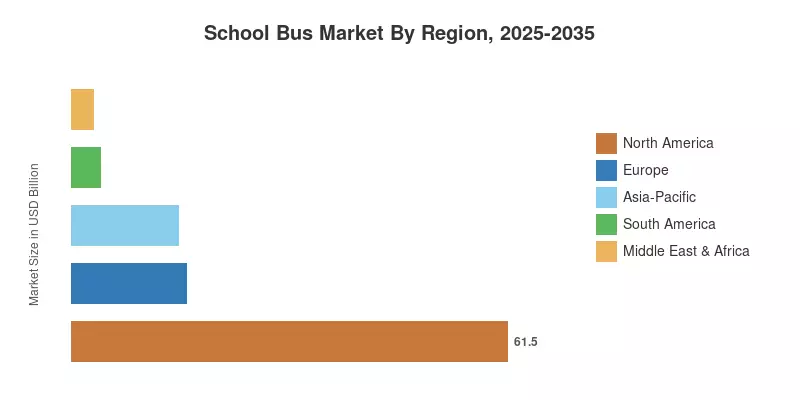
School Bus Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Federal and state zero-emission funding 1.4 North America Short-term (≤2 yr)
Aging fleet replacement obligations 1.2 Global Medium-term (2–4 yr)
Student safety regulation tightening 0.9 North America, Europe Medium-term (2–4 yr)
Urban school transport formalization 0.8 Asia-Pacific Long-term (≥4 yr)
Total cost of ownership improvement 0.7 Global Long-term (≥4 yr)
Telematics and routing software adoption 0.5 North America, Europe Short-term (≤2 yr)
Driver shortage automation response 0.3 North America Long-term (≥4 yr)


Zero-Emission Funding Programs

Fleets are moved by money. Between 2022 and 2025, the EPA's Clean School Bus Program committed over USD 3.2 billion to about 1,300 school districts, financing almost 9,000 replacement vehicles [1]. California's Hybrid and Zero-Emission Truck and Bus Voucher Incentive Project, which provides vouchers that cover a large portion of the acquisition premium for a battery-electric Type C unit, was piled on top. When a 70% grant arrives, districts that would never pass a USD 400,000 capital line item do so with ease.


Aging Fleet Replacement

Every day, some 480,000 buses travel U.S. routes; according to data, a significant portion of these vehicles predate the 2010 emissions regulations [2]. Replacement is mandated by insurance companies, state inspection policies, and maintenance economics. When unplanned downtime is included, the average operating cost difference between a fifteen-year-old diesel unit and a new one surpasses USD 0.28 per mile.


Safety Regulation Tightening

NHTSA's stability control and emergency braking rulemakings, combined with state-level illegal-passing camera statutes now active in more than 25 states, push safety content per vehicle upward [6]. Lane departure warning, 360-degree camera arrays, and child-check systems that once sat on option sheets now ship standard on flagship trims, adding an estimated USD 7,000–12,000 of content value per unit.

Total Cost of Ownership

Electric units cost more upfront and less to run. DOE analysis puts electric school bus energy costs at roughly 60% below diesel equivalents on typical 70-mile daily duty cycles, with maintenance savings of USD 2,500–4,000 annually per vehicle [3]. Where electricity rates stay under USD 0.12/kWh and duty cycles are predictable, payback lands inside eight years even without incentives.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Acquisition price premium on electrified units -1.1 Global Short-term (≤2 yr)
Charging infrastructure and grid interconnection delays -0.8 North America, Europe Medium-term (2–4 yr)
District budget constraints and bond dependency -0.7 Global Medium-term (2–4 yr)
Driver shortages limiting route expansion -0.5 North America Short-term (≤2 yr)
Cold-weather range degradation -0.3 North America, Europe Long-term (≥4 yr)


The Acquisition Premium

The price of a typical Type C diesel bus is close to $135,000. Depending on the size of the pack, its battery-electric counterpart usually costs between $320,000 and $420,000 [3]. Although grant pools are limited and often oversubscribed—the EPA's 2023 rebate round had applications that were several times the available funding—grants help close the gap for early adopters. Districts outside of the winners' circle just have to repurchase diesel.


Infrastructure and Interconnection

The easy part is buses. Utility connection lines in some jurisdictions extend beyond eighteen months, and depot charging for a twenty-vehicle electric fleet frequently necessitates a service upgrade costing between USD 500,000 and USD 1.5 million [12]. This mismatch has hampered follow-on orders and made procurement authorities wary of committing to full-fleet conversion timeframes. Several districts have accepted deliveries of vehicles that they are not yet able to charge at scale.


Budget Structure

School transport budgets are politically exposed and bond-dependent. Per-pupil transportation spending has risen sharply since 2020 while enrollment in many districts declined, squeezing the cost base [10]. When a bond referendum fails, the bus order is among the first line items deferred — often by two to three budget cycles.


School Bus Market Opportunities

Vehicle-to-Grid Revenue Streams

School buses sit idle roughly 90% of the year. Utilities in Virginia, California, and Massachusetts now compensate districts for discharging bus batteries during peak demand events, with pilot participants reporting USD 3,000–6,000 in annual per-vehicle value [12]. Scale that across a 50-bus depot and the economics of electrification change materially.

Emerging Market First-Fleet Demand

India, Indonesia, Vietnam, and Brazil are formalizing school transport that previously ran on informal vans and shared autos. India's school bus fleet has expanded alongside private school enrollment growth, and state safety rules mandating GPS tracking and speed governors create a specification floor that informal operators cannot meet [11]. This is greenfield demand, not replacement demand.

Data and Subscription Services

Routing optimization, ridership verification, and predictive maintenance are migrating to recurring-revenue software sold per vehicle per month. Districts running RFID student check-in and dynamic routing report 8–14% reductions in route mileage [9]. Manufacturers who bundle hardware with multi-year data contracts capture margin that pure vehicle sales cannot deliver.

Retrofit and Repower Programs

Not every district can afford a new vehicle. Repowering a mid-life diesel chassis with an electric drivetrain costs roughly 40–50% of a new electric unit and preserves the existing body [3]. A handful of specialist integrators have built businesses here, and several states now allow repowers to qualify for clean-vehicle incentive dollars.

Advanced Safety Content Upgrades

The installed base is large and under-equipped. Retrofitting exterior stop-arm cameras, interior child-detection sensors, and collision mitigation onto existing fleets addresses a market of hundreds of thousands of vehicles at USD 4,000–9,000 per unit — far cheaper than replacement and increasingly mandated by state statute [6].


School Bus Market Future Outlook

Electrification Reaches Cost Parity

Battery pack prices have fallen roughly 85% since 2013, and BloombergNEF projects continued decline through the early 2030s [3]. Once packs approach USD 75/kWh, an electric Type C bus reaches acquisition parity with diesel on a total-cost basis without subsidy — a threshold most analysts place in the 2030–2032 window. That inflection, not any single policy, determines whether electrification becomes default or stays niche.

Depots Become Energy Assets

School districts will find themselves operating megawatt-scale storage without having planned to. A 50-bus electric fleet represents roughly 7 MWh of capacity, and IEA modeling of commercial fleet flexibility suggests aggregated depot resources could become meaningful grid services providers by the early 2030s [12]. Districts that structure utility agreements early will capture value; those that don't will simply pay demand charges.

Automation Arrives Slowly, Assistance Arrives Fast

Fully driverless school buses face a regulatory and public-acceptance wall that will not fall this decade. Driver-assistance content, though, scales quickly — automatic emergency braking, blind-spot intervention, and pedestrian detection are already migrating from option to standard [6]. Expect near-universal Level 2 assistance content on new units well before any meaningful autonomous deployment.

Reporting Obligations Reshape Procurement

Sustainability disclosure is reaching public entities. School districts in California and several EU member states now report fleet emissions as part of broader municipal climate accounting, and bond investors increasingly ask about transition plans [4]. Procurement decisions once made purely on price now carry a reporting dimension that favors low-emission platforms even where the financial case remains marginal.


Regional Market Share Analysis

Region Share of Global Market (2025) Primary Investment Themes
North America 61.5% Fleet electrification, safety content, federal rebates
Europe 16.2% Clean procurement quotas, contracted municipal transport
Asia-Pacific 15.1% First-fleet build-out, safety mandates, urbanization
South America 4.1% Rural access programs, public tender cycles
Middle East & Africa 3.1% Private school expansion, donor-funded rural transport
Total 100.0% —

The School Bus Market remains structurally concentrated in North America, where dedicated yellow-bus infrastructure is a legal requirement rather than a transport option. Elsewhere, school transport rides on contracted coaches, municipal transit, or informal operators — which caps addressable value but leaves substantial headroom as regulation formalizes.


North America

Country Share of Region Key Driver
United States 87.4% EPA Clean School Bus Program funding cycles
Canada 10.8% Provincial zero-emission fleet targets
Mexico 1.8% Private school and contractor demand


Federal money set the tempo here. Beyond the EPA program, Canada's Zero Emission Transit Fund has extended eligibility to school transport in several provinces, and Quebec's electrification targets are among the most aggressive in North America [5]. U.S. demand is unusually predictable because roughly 25 million students ride daily and route structures change slowly, giving OEMs multi-year visibility that few commercial vehicle segments enjoy [2].

Europe

Country CAGR (2026–2035) Key Driver
United Kingdom 5.4% Home-to-school transport contract renewals
Germany 5.1% Clean Vehicles Directive procurement quotas
France 5.6% Regional transport authority electrification
Rest of Europe 4.9% Nordic zero-emission fleet policies


European school transport rarely uses a dedicated yellow-bus format. Instead, regional authorities contract coach operators, which routes demand through public tender processes governed by the Clean Vehicles Directive's minimum clean-vehicle procurement shares [4]. That structure favors established coach manufacturers over dedicated school bus specialists and keeps average selling prices closer to standard midibus economics.

Asia-Pacific

Country USD Million (2025) Key Driver
China 1,180 Provincial fleet renewal and safety standards
India 890 Private school enrollment and GPS mandates
Japan 340 Rural consolidation and route restructuring
Australia 295 State contract electrification pilots
Rest of Asia-Pacific 675 Urban transport formalization


Growth here is about formalization more than replacement. China's mandatory school bus safety standard established chassis, seating, and stop-signal requirements that informal operators cannot satisfy, effectively creating a compliant-vehicle category overnight [11]. India's pattern differs — demand follows private school expansion in tier-two cities, and state transport departments have layered speed governors, tracking devices, and attendant requirements onto registration renewal.

South America

Country Share of Region Key Driver
Brazil 62.0% Caminho da Escola federal procurement program
Argentina 15.5% Provincial rural transport contracts
Chile 11.0% Urban route safety upgrades
Rest of South America 11.5% Municipal tender activity


Brazil's Caminho da Escola program has procured tens of thousands of vehicles for rural districts since inception, making the federal government the single largest buyer on the continent [13]. Tender cycles are lumpy and politically timed, which produces volatile annual volumes — a good year can double a weak one, complicating capacity planning for local assemblers.

Middle East & Africa

Country CAGR (2026–2035) Key Driver
Saudi Arabia 8.1% Vision 2030 education infrastructure investment
United Arab Emirates 7.3% Private school growth and safety regulation
South Africa 5.2% Provincial scholar transport programs
Rest of MEA 6.4% Donor-funded rural access initiatives


Gulf demand is private-sector led. International school enrollment across the UAE and Saudi Arabia has grown steadily, and both markets enforce dedicated school transport licensing with cabin monitoring and air conditioning requirements that push specifications well above regional bus norms [14]. Sub-Saharan volumes remain small and heavily dependent on development finance.


School Bus Market By Region, 2025-2035

School Bus Market Segmentation

By Propulsion Type

The School Bus Market splits most consequentially along propulsion lines, where regulation and fuel economics collide.

Segment Metric Primary Demand Driver
Diesel 68.4% share (2025) Lowest acquisition cost, mature service network
Battery-Electric 19.6% CAGR (2026–2035) Grant funding and operating cost savings
Gasoline USD 2.6 Billion (2025) Simple maintenance, low-mileage routes
CNG / Propane USD 2.1 Billion (2025) Fuel cost stability, established fueling infrastructure
Hybrid / Other 4.2% CAGR (2026–2035) Transitional option for range-constrained routes


Diesel's dominance is not sentimental — it reflects unmatched cost-per-mile at scale, a service network in every county, and route flexibility that battery range does not yet match in cold climates. The segment nonetheless loses share every forecast year as grant-funded electric units displace replacement diesel orders. Battery-electric growth is the headline story of the School Bus Market, but the base is small; a 19.6% CAGR from roughly 6% of 2025 volume still leaves diesel as the plurality powertrain in 2035.

By Bus Type

Segment Metric Primary Demand Driver
Type C (Conventional) 51.8% share (2025) Standard full-size route workhorse
Type D (Transit-Style) USD 6.3 Billion (2025) High-capacity urban and consolidated routes
Type A 6.9% CAGR (2026–2035) Special-needs and small-route flexibility
Type B USD 1.1 Billion (2025) Niche capacity and access requirements


Type C remains the default full-size configuration across the School Bus Market, favored for its familiar service architecture and lower unit cost. Type D units command premium pricing on high-density routes and are disproportionately represented in electric conversions because flat-front packaging accommodates larger battery packs beneath the floor. Type A demand tracks special-needs enrollment, which has grown faster than general enrollment in most U.S. states.

By End User

Segment Metric Primary Demand Driver
Public School Districts USD 15.9 Billion (2025) Statutory transport obligations
Private Contractors 6.6% CAGR (2026–2035) Outsourcing of district fleet operations
Private and Charter Schools 12.4% share (2025) Enrollment growth and parent expectations


District-owned fleets still account for the majority of School Bus Market value, but contractor outsourcing is the faster-moving segment as districts confront driver shortages and maintenance overhead they would rather not staff internally.


Competitive Benchmarking

The School Bus Market is a moderate-to-high concentration industry — an estimated HHI near 2,200, with the top five manufacturers holding approximately 78–85% of global volume. North American body-on-chassis production is effectively a three-way contest, while electric entrants and international specialists compete at the edges. Barriers are meaningful: federal safety certification, dealer service networks, and district procurement relationships take years to build.

Company Est. Revenue Share Range Key Offerings for School Bus Market Strategic Positioning
Blue Bird Corporation ~22–27% Vision, All American, electric and propane variants Broadest alternative-fuel portfolio
Thomas Built Buses (Daimler) ~19–24% Saf-T-Liner C2, Jouley electric Daimler powertrain and service leverage
IC Bus (Navistar / Traton) ~18–23% CE Series, chargE electric Integrated chassis and engine control
Lion Electric ~2–4% LionC, LionD purpose-built electric Pure-play electric specialist
GreenPower Motor Company ~1–3% BEAST, Nano BEAST Low-volume purpose-built EV
Yutong Bus ~5–8% China-market school bus platforms Domestic scale and export reach
Zhengzhou Nissan / Ankai ~3–5% Regional compliant school bus models China safety-standard compliance
Tata Motors ~3–5% Starbus school variants India volume leadership
Ashok Leyland ~2–4% School bus chassis and body packages Cost-competitive India platform
Marcopolo ~2–4% Volare and school-configured bodies South America tender specialist


Recent News & Developments

  • U.S. EPA (January 2024): Announced approximately USD 900 million in Clean School Bus rebate selections covering roughly 280 districts, with priority weighting toward rural and low-income applicants — sustaining order visibility into 2026 [1].
  • Blue Bird Corporation (March 2024): Opened a dedicated electric vehicle assembly and battery integration facility in Fort Valley, Georgia, targeting a substantial annual electric unit capacity increase [15].
  • Thomas Built Buses (September 2024): Expanded Jouley electric deliveries and announced enhanced vehicle-to-grid capability in partnership with fleet electrification providers [16].
  • Lion Electric (November 2024): Restructured operations amid liquidity pressure, prompting several districts to reassess supplier risk in long-cycle electric procurements [17].
  • NHTSA (April 2025): Advanced rulemaking activity on school bus occupant protection and automatic emergency braking requirements, signaling higher standard safety content [6].
  • IC Bus (June 2025): Announced expanded telematics integration across its CE Series lineup with subscription-based routing and diagnostics [18].
  • Government of India (August 2025): State transport departments strengthened school vehicle safety compliance enforcement, including tracking and speed limitation requirements for registration renewal [11].
  • Caminho da Escola / FNDE Brazil (October 2025): Issued a renewed federal procurement round for rural school transport vehicles, extending multi-year delivery commitments to domestic assemblers [13].


School Bus Market Report Scope

Parameter Detail
Market Scope Global manufacture and sale of dedicated school transport vehicles, including chassis, bodies, propulsion systems, and integrated safety and telematics content
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.8% (2026–2035)
Market Size Checkpoints USD 22.4 Billion (2025); USD 23.7 Billion (2026); USD 29.7 Billion (2030); USD 39.6 Billion (2035)
Fastest Growing Segments Battery-Electric propulsion; Type A body class; Private contractor end users
Companies Profiled Blue Bird, Thomas Built Buses, IC Bus, Lion Electric, GreenPower Motor, Yutong, Ankai, Tata Motors, Ashok Leyland, Marcopolo
Valuation Currency USD, constant 2025 dollars

FAQs

What contract structures should districts use when procuring for the School Bus Market's electric segment?
Multi-year firm-fixed-price agreements with delivery milestones protect against supplier insolvency risk. Include battery performance warranties tied to retained capacity and require escrowed spare-parts commitments [17].
How do insurance costs differ between diesel and electric units?
Electric units typically carry higher physical-damage premiums because battery replacement drives up total-loss valuations. Liability premiums are broadly comparable, and some insurers discount for advanced safety content [15].
What resale values should buyers assume for the School Bus Market's electrified vehicles?
Secondary markets remain thin, so residual assumptions should stay conservative — well below diesel comparables at the same age. Battery state-of-health documentation materially improves realized resale outcomes [3].
Which technicians and training investments does electrification require?
High-voltage certification is mandatory, and most districts underestimate the training lead time. Budget six to twelve months before first delivery to certify in-house staff or contract qualified service coverage [9].
How should fleets evaluate propane against battery-electric options?
Propane wins on upfront cost and refueling simplicity for long rural routes. Electric wins on operating cost and grant eligibility where duty cycles stay under 100 miles daily [19].
What drives supplier selection in the School Bus Market beyond price?
Dealer service density within a reasonable radius matters more than list price over a fifteen-year life. Parts availability and technician response time dominate real ownership economics [22].
Are there grant compliance obligations after award?
Yes. Federal awards typically require scrapping the replaced vehicle, retaining the new unit for a minimum service period, and submitting utilization reporting. Non-compliance can trigger fund recovery [1].    
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, transportation authority records, and authoritative automotive organizations. Key sources included the US Department of Transportation (DOT), National Highway Traffic Safety Administration (NHTSA), Federal Motor Carrier Safety Administration (FMCSA), Environmental Protection Agency (EPA), National Transportation Safety Board (NTSB), American School Bus Council (ASBC), National Association of State Directors of Pupil Transportation Services (NASDPTS), National School Transportation Association (NSTA), European Automobile Manufacturers Association (ACEA), International Energy Agency (IEA) Global EV Outlook, International Council on Clean Transportation (ICCT), Bureau of Transportation Statistics (BTS), National Center for Education Statistics (NCES), World Bank Transport Data, OECD International Transport Forum, and national ministry of transportation reports from key markets. These sources were used to collect vehicle registration statistics, safety compliance data, emissions regulations, school enrollment trends, electrification policies, and competitive landscape analysis for Type A, Type B, Type C, Type D buses, and transporter body styles across gasoline, diesel, electric, hybrid, and CNG fuel categories.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources comprised CEOs, VPs of Manufacturing, Chief Technology Officers, fleet sales directors, and regulatory compliance leaders from school bus OEMs, chassis manufacturers, and electric powertrain suppliers. School district transportation directors, fleet managers, procurement officers from educational institutions, state pupil transportation directors, and safety compliance officers from public and private school administrators were all included in the demand-side sources. Primary research verified market segmentation across bus types and fuel categories, confirmed electric vehicle implementation timelines, and collected insights on fleet replacement cycles, total cost of ownership analysis, charging infrastructure requirements, and safety technology adoption patterns.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through production volume analysis and fleet procurement data assessment. The methodology included:

Identification of 40+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America specializing in Type A through Type D school buses

Product mapping across diesel, gasoline, electric, hybrid, and CNG fuel types, with segmentation by 4x2, 4x4, 6x4, and 6x6 drive systems

Analysis of reported and modeled annual revenues specific to school bus manufacturing portfolios, including safety feature integration (ADAS, ESC, ABS, seatbelts, camera systems)

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (fleet procurement volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for seating capacity categories (less than 10, 10-20, 21-30, 31-40, 40 or more passengers)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















