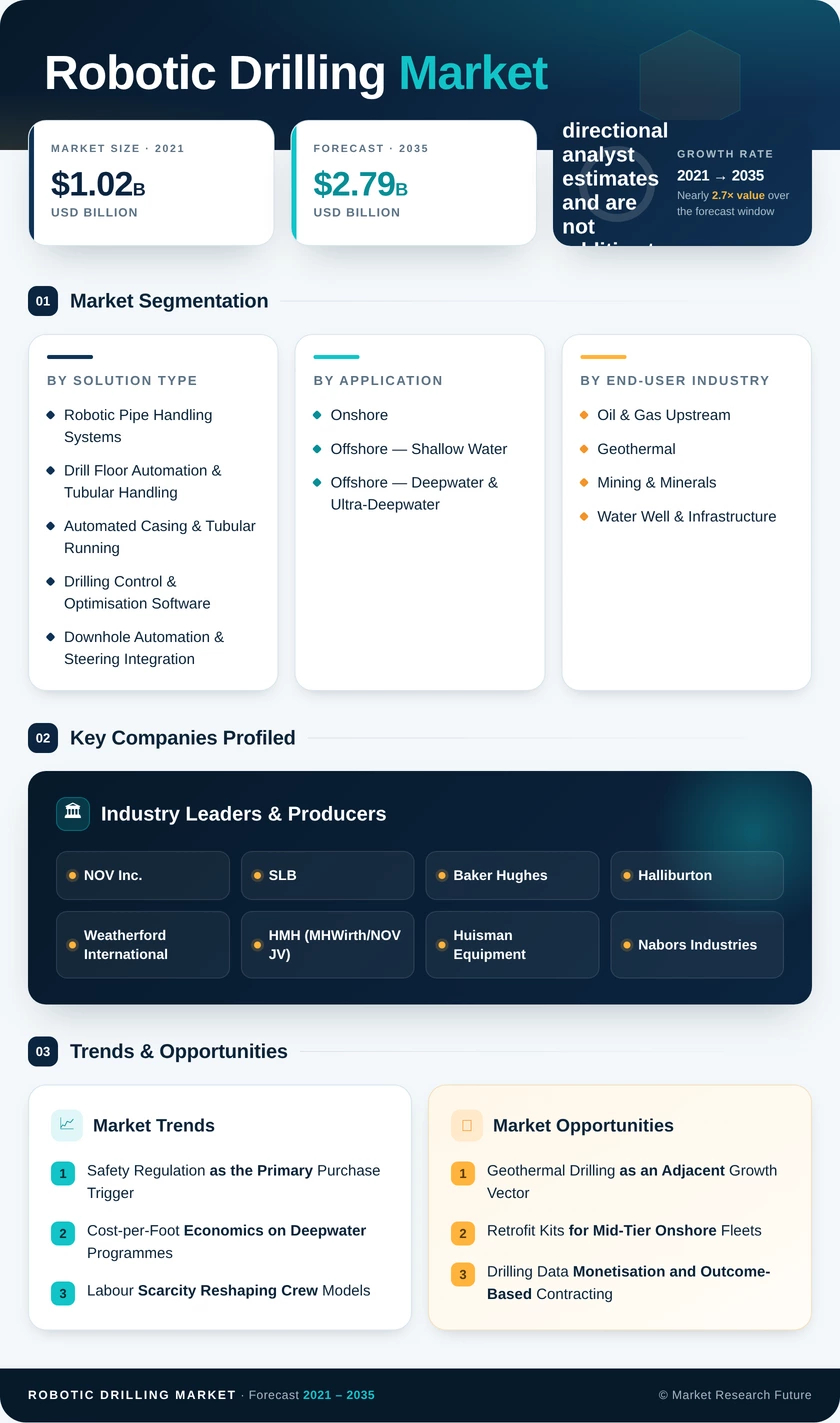
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Solution Type | Robotic Pipe Handling Systems; Drill Floor Automation & Tubular Handling; Automated Casing & Tubular Running; Drilling Control & Optimisation Software; Downhole Automation & Steering Integration | Robotic Pipe Handling Systems | Drilling Control & Optimisation Software |
| By Application | Onshore; Offshore — Shallow Water; Offshore — Deepwater & Ultra-Deepwater | Onshore | Offshore — Deepwater & Ultra-Deepwater |
| By End-User Industry | Oil & Gas Upstream; Geothermal; Mining & Minerals; Water Well & Infrastructure | Oil & Gas Upstream | Geothermal |
| By Component | Hardware; Software; Services | Hardware | Software |
| By Region | North America; Europe; Asia-Pacific; Middle East & Africa; South America | North America | Asia-Pacific |
Market Segmentation Overview
By Solution Type
| Sub-Segment | Key Trend |
| Robotic Pipe Handling Systems | Standardisation of unmanned red zones on offshore and premium land rigs |
| Drill Floor Automation & Tubular Handling | Modular retrofit packages entering mid-tier onshore fleets |
| Automated Casing & Tubular Running | Torque-and-drag control tied to well-integrity assurance requirements |
| Drilling Control & Optimisation Software | Shift from perpetual licence to subscription and performance-linked pricing |
| Downhole Automation & Steering Integration | Convergence of rotary steerable control with surface command systems |
Hardware still captures the largest revenue pool, but the strategic centre of gravity is migrating toward the control layer. Vendors that own the software interface increasingly dictate which third-party tools can participate in a drilling programme.
By Application
| Sub-Segment | Key Trend |
| Onshore | Pad drilling repetition rewarding consistent machine-executed sequences |
| Offshore — Shallow Water | Adoption gated by jack-up fleet renewal versus retirement decisions |
| Offshore — Deepwater & Ultra-Deepwater | High day rates producing the shortest automation payback in the industry |
Onshore volume and offshore value pull in different directions. Deepwater installations command far higher revenue per rig and set the technical benchmark that eventually migrates down to land fleets.
By End-User Industry
| Sub-Segment | Key Trend |
| Oil & Gas Upstream | Safety compliance overtaking pure efficiency as the purchase justification |
| Geothermal | High-temperature qualification opening a new equipment category |
| Mining & Minerals | Remote operation centres driving underground rig automation |
| Water Well & Infrastructure | Slow adoption limited by project scale and price sensitivity |
Upstream oil and gas will remain the revenue anchor throughout the forecast, yet the incremental growth story increasingly sits in geothermal. Vendors treating that vertical as a genuine engineering programme rather than a marketing extension will capture the premium.
By Component
| Sub-Segment | Key Trend |
| Hardware | Longest replacement cycles, highest unit revenue, most capital-intensive |
| Software | Fastest growth, highest gross margin, increasingly subscription-based |
| Services | Integration, commissioning and training becoming a distinct revenue line |
Services deserve more attention than their share suggests. Integration engineering and crew retraining now represent a meaningful share of total project cost, and contractors that industrialise those functions turn a cost centre into recurring margin.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA