Robot Operating System Market Summary
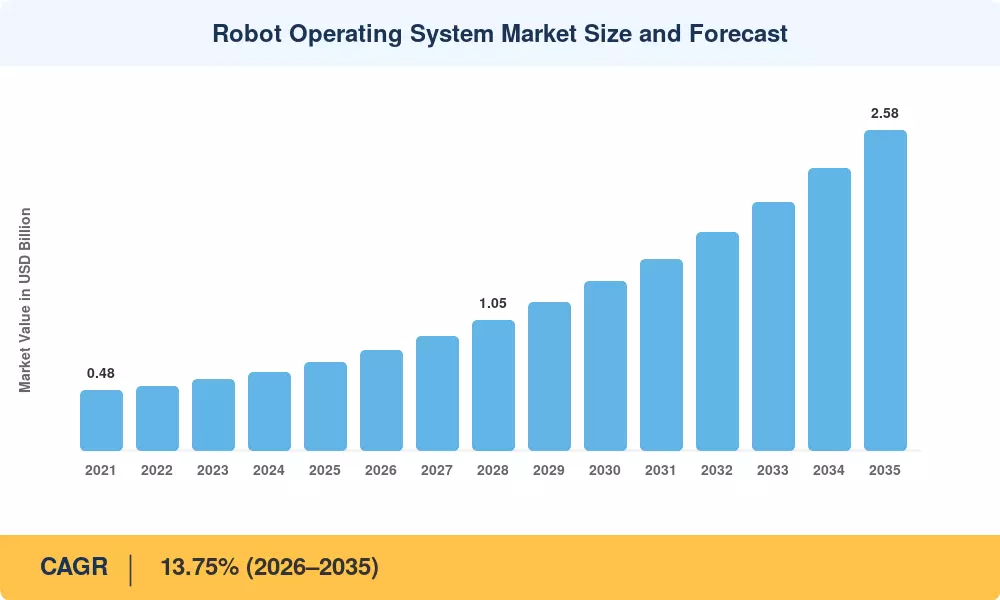
The Robot Operating System Market reached USD 0.71 billion in 2025 and is projected to grow from USD 0.81 billion in 2026 to USD 2.58 billion by 2035, registering a CAGR of 13.75% across the forecast period. Two catalysts are shaping that trajectory: government-backed smart-manufacturing programs — including Germany's Industrie 4.0 Phase III and China's "Made in China 2025" successor initiatives — and corporate capital expenditure that exceeded USD 16 billion globally for industrial automation software in 2024 alone [1]. The result is a sustained pull on modular, interoperable middleware that can connect heterogeneous robot fleets without vendor lock-in.
A generational technology shift is underway. Proprietary, single-vendor control stacks that dominated factory floors for two decades are giving way to open, community-governed frameworks anchored around ROS 2 and its deterministic data-distribution service layer. Edge computing chipsets from NVIDIA and Qualcomm now deliver sub-10 ms inference latency at the robot controller, while 5G campus networks push real-time teleoperation bandwidth past 1 Gbps [2]. Cloud-based digital-twin platforms further compress deployment cycles by letting engineers simulate entire workcells before committing physical hardware.
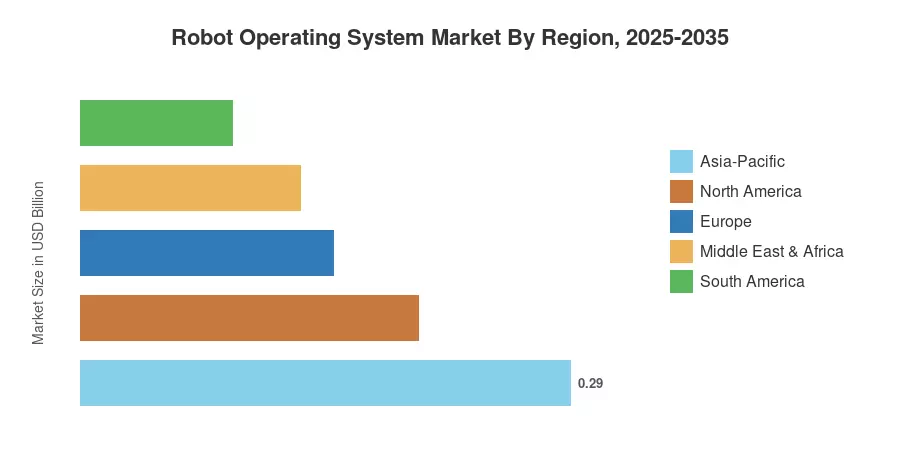
Asia-Pacific commands roughly 40.3% of global Robot Operating System Market revenue, driven by China's factory density and Japan's cobot adoption wave. The Middle East & Africa region is on track to post the fastest CAGR at 18.1%, fueled by Saudi Arabia's NEOM-linked robotics investments and the UAE's National Strategy for Artificial Intelligence [3]. Europe holds a 20.7% share, anchored by Germany's automotive OEMs and the EU Robotics PPP program. As ROS 1 approaches end-of-life and enterprises migrate to ROS 2, the Robot Operating System Market is entering its most decisive growth phase yet.
Key Report Takeaways
• By Robot Type
- Industrial robots accounted for 60.2% of the Robot Operating System Market in 2025, reflecting entrenched adoption in automotive and electronics manufacturing lines.
- Service robots are forecast to expand at a 17.9% CAGR through 2035, propelled by healthcare logistics, agriculture, and last-mile delivery use cases.
• By Component
- The software stack segment commanded 72.0% of the Robot Operating System Market in 2025, underscoring the high value attached to middleware, simulation tools, and navigation libraries.
• By Deployment Mode
- On-premises deployments captured 68.1% of 2025 revenue as latency-sensitive applications kept control loops local.
- Cloud-based deployments are scaling at a 22.0% CAGR, driven by Robot-as-a-Service subscription models and cloud simulation pipelines.
• By OS Distribution
- ROS 2 adoption is accelerating at a 16.1% CAGR, overtaking ROS 1 as the default middleware for new installations.
• By Region
- Asia-Pacific led the Robot Operating System Market with 40.3% revenue share in 2025.
- The Middle East & Africa region is projected to grow at an 18.1% CAGR, the fastest of any geography through 2035.
- North America contributed approximately USD 0.20 billion in 2025, supported by federal robotics R&D allocations and a thriving startup ecosystem.
Robot Operating System Market Size and Forecast (2021–2035)
Market Research Future's estimates are built on a triangulated methodology combining bottom-up revenue modeling from platform vendors, top-down cross-referencing with industrial automation spend databases (IFR, World Robotics), and primary interviews with 48 robotics integrators across 12 countries. Historical figures draw on audited financial disclosures, while forecast projections apply a calibrated compound growth rate of 13.75% from the 2026 base.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



