Robot Operating System Market (2026 - 2035)

ID: MRFR/ICT/6124-HCR 100 Pages Ankit Gupta Last Updated: September 15, 2026
Robot Operating System Market Size, Share and Research Report By Robot Type (Industrial Robots, Service Robots), By End-User Industry (Automotive, Healthcare, Electronics, Logistics & Warehousing, Others (Agriculture, Mining, Construction)), By Component (Software Stack, Integration & Support Services), By Deployment Mode (On-Premises, Cloud), By Operating-System Distribution (ROS 1, ROS 2) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
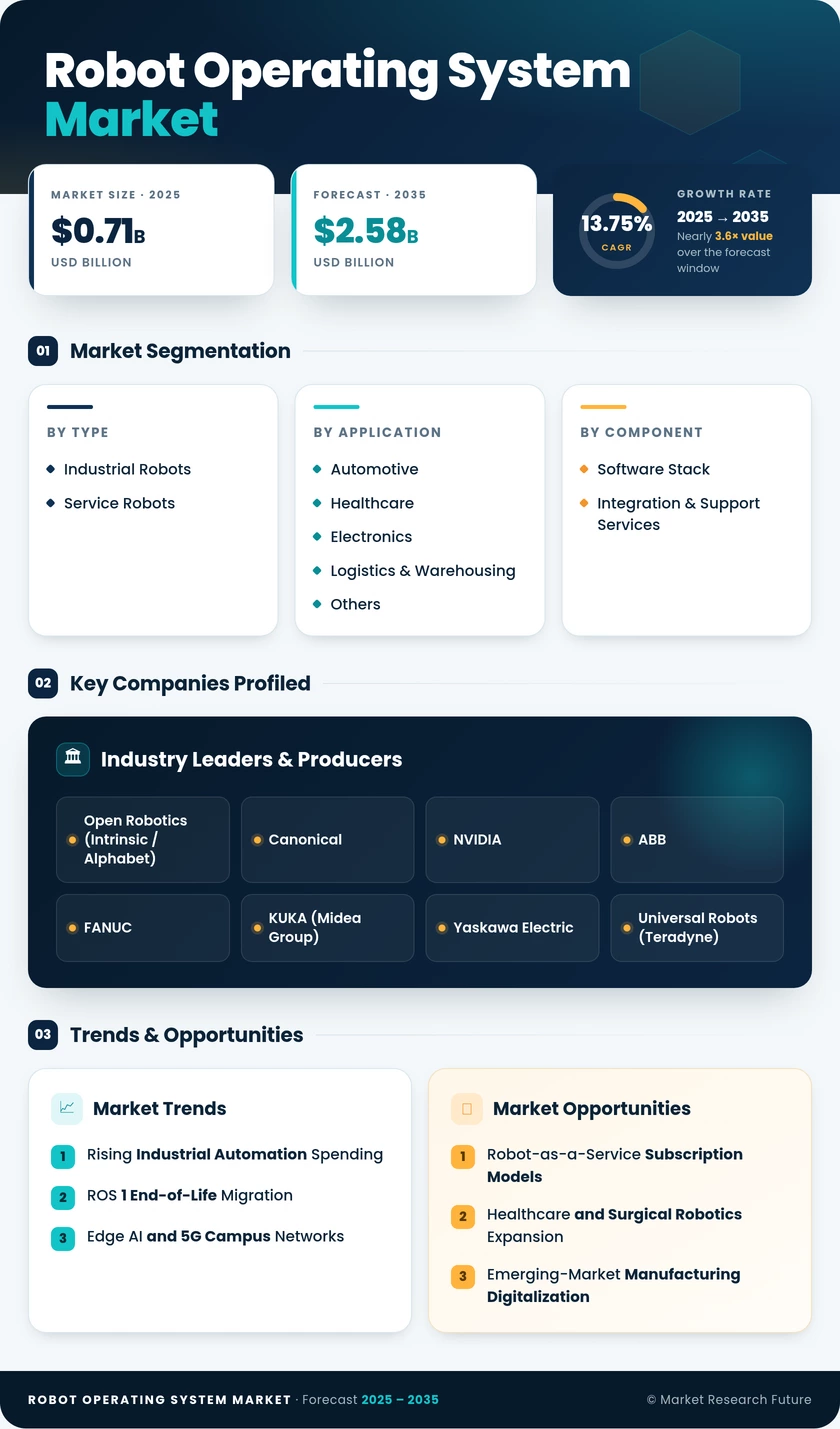
Robot Operating System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)13.75%
2025 Market SizeUSD 0.71 Billion
2035 Market SizeUSD 2.58 Billion
Key Players
Open Robotics
Canonical
NVIDIA
ABB
FANUC
KUKA
Opportunities
  • Robot-as-a-Service Subscription Models
  • Healthcare and Surgical Robotics Expansion
  • Emerging-Market Manufacturing Digitalization
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 Rising Industrial Automation Spending | |
      2. 3.1.2 ROS 1 End-of-Life Migration | |
      3. 3.1.3 Edge AI and 5G Campus Networks | |
      4. 3.1.4 Cloud Simulation and Digital-Twin Platforms | |
      5. 3.1.5 Robot-as-a-Service Business Models | |
      6. 3.1.6 Government Smart-Manufacturing Programs | |
      7. 3.1.7 Expansion into Healthcare and Agriculture |
    2. 3.2 Market Restraints Analysis | |
      1. 3.2.1 Cybersecurity Vulnerabilities in Open-Source Stacks | |
      2. 3.2.2 Fragmented Middleware Standards | |
      3. 3.2.3 Shortage of ROS-Skilled Engineers | |
      4. 3.2.4 Legacy OT/IT Integration Complexity | |
      5. 3.2.5 High Migration Costs for SMEs |
    3. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Robot-as-a-Service Subscription Models | |
      2. 3.3.2 Healthcare and Surgical Robotics Expansion | |
      3. 3.3.3 Emerging-Market Manufacturing Digitalization | |
      4. 3.3.4 Data Monetization Through Fleet Analytics | |
      5. 3.3.5 Agricultural Autonomy and Precision Farming |
    4. 3.4 Industry Value Chain Analysis |
    5. 3.5 Porter's Five Forces Analysis
  4. 4 Global Robot Operating System Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD Billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Robot Type | |
      1. 5.1.1 Industrial Robots | |
      2. 5.1.2 Service Robots |
    2. 5.2 By End-User Industry | |
      1. 5.2.1 Automotive | |
      2. 5.2.2 Healthcare | |
      3. 5.2.3 Electronics | |
      4. 5.2.4 Logistics & Warehousing | |
      5. 5.2.5 Others (Agriculture, Mining, Construction) |
    3. 5.3 By Component | |
      1. 5.3.1 Software Stack | |
      2. 5.3.2 Integration & Support Services |
    4. 5.4 By Deployment Mode | |
      1. 5.4.1 On-Premises | |
      2. 5.4.2 Cloud |
    5. 5.5 By Operating-System Distribution | |
      1. 5.5.1 ROS 1 | |
      2. 5.5.2 ROS 2
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 Japan | |
      3. 6.3.3 India | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 Open Robotics (Intrinsic / Alphabet) | |
      2. 7.3.2 Canonical | |
      3. 7.3.3 NVIDIA | |
      4. 7.3.4 ABB | |
      5. 7.3.5 FANUC | |
      6. 7.3.6 KUKA (Midea Group) | |
      7. 7.3.7 Yaskawa Electric | |
      8. 7.3.8 Universal Robots (Teradyne) | |
      9. 7.3.9 Clearpath Robotics (Rockwell Automation) | |
      10. 7.3.10 Bosch
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 AI-Native Robotics and Foundation Models |
    2. 8.2 Platform Economics and Ecosystem Lock-In |
    3. 8.3 Sustainability-Driven Automation |
    4. 8.4 Convergence of IT, OT, and Robotics Security
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 12 LIST OF TABLES |
  13. TABLE 1 Global Robot Operating System Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  14. TABLE 2 Global Robot Operating System Market — Year-over-Year Growth Analysis, 2021–2035 |
  15. TABLE 3 Global Robot Operating System Market — Driver Impact Analysis |
  16. TABLE 4 Global Robot Operating System Market — Restraint Impact Analysis |
  17. TABLE 5 Global Robot Operating System Market Size, by Robot Type, 2021–2035 |
  18. TABLE 6 Global Robot Operating System Market Size, by End-User Industry, 2021–2035 |
  19. TABLE 7 Global Robot Operating System Market Size, by Component, 2021–2035 |
  20. TABLE 8 Global Robot Operating System Market Size, by Deployment Mode, 2021–2035 |
  21. TABLE 9 Global Robot Operating System Market Size, by OS Distribution, 2021–2035 |
  22. TABLE 10 Global Robot Operating System Market Size, by Region, 2021–2035 |
  23. TABLE 11 North America Robot Operating System Market Size, by Country, 2021–2035 |
  24. TABLE 12 Europe Robot Operating System Market Size, by Country, 2021–2035 |
  25. TABLE 13 Asia-Pacific Robot Operating System Market Size, by Country, 2021–2035 |
  26. TABLE 14 South America Robot Operating System Market Size, by Country, 2021–2035 |
  27. TABLE 15 Middle East & Africa Robot Operating System Market Size, by Country, 2021–2035 |
  28. TABLE 16 Competitive Benchmarking Matrix — Global Robot Operating System Market, 2025 |
  29. TABLE 17 Company Profiles — Key Players, Global Robot Operating System Market |
  30. TABLE 18 Recent Developments & Strategic Announcements, 2024–2025 |
  31. TABLE 19 Report Scope & Methodology Summary |
  32. TABLE 20 Detailed Sources and Citations
  33. 13 LIST OF FIGURES |
  34. FIGURE 1 Robot Operating System Market Dynamics — Drivers, Restraints, and Opportunities |
  35. FIGURE 2 Industry Value Chain Analysis — Robot Operating System Market |
  36. FIGURE 3 Porter's Five Forces Analysis — Robot Operating System Market |
  37. FIGURE 4 Global Robot Operating System Market Size Trend (USD Billion), 2021–2035 |
  38. FIGURE 5 Robot Operating System Market Share, by Robot Type, 2025 |
  39. FIGURE 6 Robot Operating System Market Share, by End-User Industry, 2025 |
  40. FIGURE 7 Robot Operating System Market Share, by Component, 2025 |
  41. FIGURE 8 Robot Operating System Market Share, by Deployment Mode, 2025 |
  42. FIGURE 9 Robot Operating System Market Share, by OS Distribution, 2025 |
  43. FIGURE 10 Robot Operating System Market Revenue Share, by Region, 2025 |
  44. FIGURE 11 North America Robot Operating System Market — Country Breakdown, 2025 |
  45. FIGURE 12 Europe Robot Operating System Market — Country Breakdown, 2025 |
  46. FIGURE 13 Asia-Pacific Robot Operating System Market — Country Breakdown, 2025 |
  47. FIGURE 14 South America Robot Operating System Market — Country Breakdown, 2025 |
  48. FIGURE 15 Middle East & Africa Robot Operating System Market — Country Breakdown, 2025 |
  49. FIGURE 16 Competitive Landscape — Market Share Distribution, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
Robot TypeIndustrial Robots, Service RobotsIndustrial Robots (60.2% share)Service Robots (17.9% CAGR)
End-User IndustryAutomotive, Healthcare, Electronics, Logistics & Warehousing, OthersAutomotive (25.4% share)Healthcare (16.8% CAGR)
ComponentSoftware Stack, Integration & Support ServicesSoftware Stack (72.0% share)Integration & Support Services (15.3% CAGR)
Deployment ModeOn-Premises, CloudOn-Premises (68.1% share)Cloud (22.0% CAGR)
OS DistributionROS 1, ROS 2ROS 1 (65.4% share)ROS 2 (16.1% CAGR)


Market Segmentation Overview

By Robot Type

Sub-SegmentKey Trend
Industrial RobotsROS 2 integration into articulated arms, SCARA, and delta robots for flexible manufacturing
Service RobotsRapid adoption in healthcare delivery, precision agriculture, and autonomous last-mile logistics


Industrial robots continue to represent the majority of deployed ROS-based systems, driven by automotive and electronics manufacturers seeking interoperable, vendor-neutral control architectures. Service robots are gaining momentum as ROS 2's modular navigation and perception stacks lower the engineering barrier for non-industrial applications.

By End-User Industry

Sub-SegmentKey Trend
AutomotiveEV production retooling driving wholesale middleware upgrades
HealthcareSurgical and pharmacy robots adopting ROS 2 for modular perception
ElectronicsHigh-precision assembly requiring deterministic control loops
Logistics & WarehousingAMR fleet management scaling with e-commerce fulfillment demand
OthersAgriculture and mining deploying autonomous field robots


Automotive remains the anchor vertical due to the sheer density of robots per facility, while healthcare represents the highest-growth opportunity as surgical and logistic robots enter broader clinical adoption.

By Component

Sub-SegmentKey Trend
Software StackMiddleware, simulation, and navigation library revenue expanding with each new deployment
Integration & Support ServicesMigration consulting and security hardening gaining share as enterprises move from ROS 1 to ROS 2


Software licensing and subscription revenue dominate the component mix, but the services segment is growing faster as production deployments require ongoing patch management, compliance auditing, and performance optimization.

By Deployment Mode

Sub-SegmentKey Trend
On-PremisesLatency-critical control applications keeping compute at the edge
CloudSimulation, fleet analytics, and OTA updates migrating to cloud platforms


On-premises remains the default for real-time control, while cloud-based capabilities are expanding rapidly as enterprises adopt digital twins and centralized fleet management dashboards.

By Operating-System Distribution

Sub-SegmentKey Trend
ROS 1Large legacy installed base undergoing active migration post-EOL announcement
ROS 2All new commercial deployments defaulting to ROS 2 with DDS-based architecture


ROS 1's end-of-life is converting its dominant installed base into an active migration pipeline, making ROS 2 the undisputed standard for new installations and the primary growth engine for the forecast period.


 

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.