Risk-based Authentication Market (2026 - 2035)

Risk-based Authentication Market Size, Share and Research Report By Offering (Solution and Service), By Deployment (On-Premise and Cloud), By Authentication Method (Knowledge-Based Authentication, Possession-Based Authentication, Inherence-Based (Biometric) Authentication, Multi-Factor and Composite Authentication, and Adaptive Behavioral Authentication), By Organization Size (Large Enterprises and Small and Medium Enterprises), By End-User Vertical (Banking and Financial Services, Retail, Government, Healthcare, IT and Telecom, and Others) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) –Industry Forecast Till 2035
ID: MRFR/ICT/31095-HCR 100 Pages Aarti Dhapte Last Updated: October 24, 2026
Risk-based Authentication Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.1%
2025 Market SizeUSD 5.92 Billion
2035 Market SizeUSD 11.75 Billion
Key Players
Microsoft Corporation
Okta, Inc.
Ping Identity
IBM Corporation
Broadcom Inc.
Cisco Systems
Opportunities
  • Real-Time Payment Rails in Emerging Markets
  • Risk Signals as a Service
  • Digital Identity Wallet Integration

Risk-based Authentication Market Summary

The Risk Based Authentication Market was valued at USD 5.92 Billion in 2025 and is projected to reach USD 6.34 Billion in 2026, then climb to USD 11.75 Billion by 2035, a CAGR of 7.1% over 2026–2035. Two catalysts anchor that path. Payment regulators keep tightening strong customer authentication rules, and identity has become the main attack surface: Microsoft observes roughly 600 million identity attacks every day [4], while cybercrime losses reported to the FBI reached USD 16.6 billion in 2024 [3].

Static login controls are being retired. Password-plus-token designs and blanket multi-factor prompts are giving way to risk engines that score device posture, network reputation, location and behavioral signals before deciding whether to allow, challenge or block a session. Federal policy accelerated the shift when OMB memorandum M-22-09 required agencies to adopt phishing-resistant authentication by the end of fiscal 2024 [8]. With the average breach costing USD 4.88 million in 2024 [2], buyers now judge the Risk Based Authentication Market by fraud prevented per login, not by token counts.

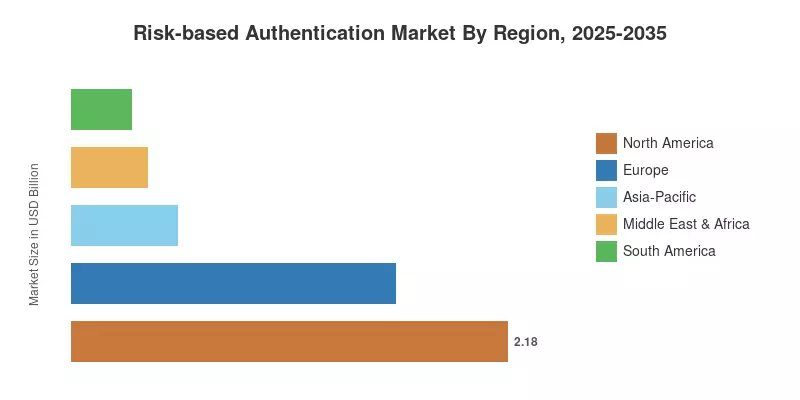
Regionally, North America leads with a 36.8% share, supported by zero trust mandates and mature digital banking. Asia-Pacific is the fastest-growing region at an 8.9% CAGR as real-time payment volumes explode, and Europe ranks second at USD 1.62 Billion, propelled by PSD2 and the Digital Operational Resilience Act [12]. Over the forecast window, growth in the Risk Based Authentication Market will increasingly come from cloud-delivered, behavior-driven controls embedded in every transaction rather than every login.

Key Report Takeaways

Six findings frame the Risk Based Authentication Market for buyers, vendors and investors.

• By Offering

  • Solution licenses hold a 71.4% share of the Risk Based Authentication Market in 2025, reflecting entrenched platform contracts in banking and government
  • Service is the faster-growing offering at an 8.6% CAGR, as managed tuning and compliance advisory replace in-house administration

• By Deployment

  • Cloud deployment is expanding at an 8.8% CAGR, driven by SaaS identity platforms and multi-cloud zero trust programs
  • On-Premise retains a 33.5% share, concentrated in defense, public sector and air-gapped environments

• By Authentication Method

  • Multi-Factor and Composite Authentication commands a 40.1% share thanks to long-standing compliance recognition
  • Adaptive Behavioral Authentication grows at a 7.4% CAGR as invisible, context-aware checks replace static prompts

• By Organization Size

  • Large Enterprises account for a 61.5% share of the Risk Based Authentication Market, backed by larger budgets and stricter audit regimes
  • Small and Medium Enterprises expand at an 8.7% CAGR through pay-as-you-grow SaaS tiers and MSP bundles

• By End-User Vertical

  • Banking and Financial Services holds a 27.6% share, the largest of any vertical
  • Healthcare is the fastest-growing vertical at a 7.3% CAGR as telehealth and patient portals multiply access points

• By Region

  • North America leads with a 36.8% share
  • Asia-Pacific posts the highest growth at an 8.9% CAGR
  • Europe reaches USD 1.62 Billion in 2025

Market Size and Forecast (2021–2035)

Estimates for the Risk Based Authentication Market combine vendor revenue mapping across 40+ identity and fraud-prevention suppliers, primary interviews with CISOs and fraud leaders, and demand-side modeling of authenticated digital transactions. Historical values were reconciled with public filings and regulatory adoption timelines; forecasts apply scenario-weighted assumptions on regulation, cloud migration and fraud-loss trends.
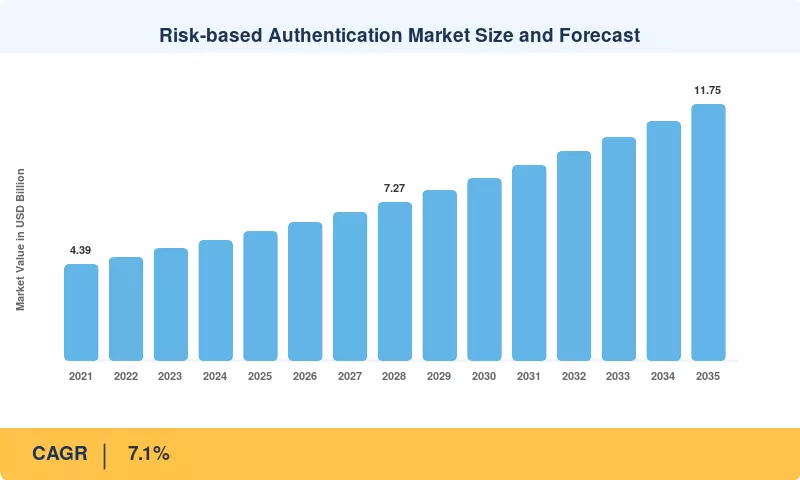
Risk-based Authentication Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Escalating account takeover and credential fraud +1.6% Global Short-term (≤2 yr)
Strong customer authentication regulation +1.3% Europe, Asia-Pacific Medium-term (2–4 yr)
Zero trust mandates in government and critical sectors +1.1% North America, Europe Medium-term (2–4 yr)
Cloud and SaaS migration of identity stacks +0.9% Global Long-term (≥4 yr)
AI-driven behavioral analytics maturity +0.8% Global Long-term (≥4 yr)
Healthcare digitization and HIPAA security updates +0.6% North America Medium-term (2–4 yr)

Escalating Account Takeover and Credential Fraud

Stolen and phished credentials remain the cheapest route into enterprise and consumer accounts. Verizon found a non-malicious human element in 68% of breaches analyzed in its 2024 report [1], and the FBI logged USD 16.6 billion in reported losses for 2024 [3]. Because attackers now replay valid credentials, static checks fail by design. Risk scoring that weighs device fingerprint, velocity and session behavior is the practical counter, making fraud-loss reduction the strongest near-term budget justification.

Strong Customer Authentication Regulation

Payment regulators are writing risk-based logic directly into law. The EU's regulatory technical standards on strong customer authentication allow exemptions only when providers run real-time transaction risk analysis within defined fraud-rate thresholds [5]. India's Reserve Bank followed with 2025 directions that permit risk-based additional factors for digital payments [7]. Each rule converts authentication from a fixed step into a scored decision, which creates recurring demand for analytics engines among banks and payment service providers.

Zero Trust Mandates

Zero trust programs require every session to be evaluated continuously rather than trusted after login. OMB memorandum M-22-09 set phishing-resistant authentication targets for all US federal agencies [8], and CISA's Zero Trust Maturity Model v2.0 lists dynamic, risk-informed access decisions as an advanced-stage identity capability [9]. Defense contractors and critical-infrastructure operators are adopting the same framework, extending procurement well beyond civilian agencies across the medium term.

Cloud and SaaS Migration of Identity Stacks

Enterprises are moving directories, single sign-on and policy engines to SaaS platforms, where risk scoring arrives as a native feature rather than a bolt-on. Okta reported more than 19,000 customers in its fiscal 2025 annual filing [22], illustrating the installed base available for upsell. Cloud delivery also lets vendors pool threat signals across tenants, improving model accuracy with every login and widening the performance gap over appliance-based tools.

AI-Driven Behavioral Analytics Maturity

Machine learning has made passive signals usable at scale. Typing cadence, swipe pressure, navigation patterns and device telemetry can now be scored in milliseconds. Microsoft reports blocking thousands of password attacks every second across its identity cloud [4], a volume no rules-based system could triage. As models improve, organizations can step up challenges only for genuinely risky sessions, cutting friction while raising detection rates.

Healthcare Digitization and HIPAA Security Updates

The US Department of Health and Human Services proposed HIPAA Security Rule changes in January 2025 that would make multi-factor authentication a baseline requirement for electronic protected health information [11]. Telehealth, patient portals and connected devices multiply access points, while clinicians need near-zero friction during emergencies. That combination favors silent risk evaluation paired with smart badges, positioning healthcare as the fastest-growing vertical through 2035.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Privacy limits on behavioral and biometric data -0.7% Europe, Asia-Pacific Long-term (≥4 yr)
Integration complexity with legacy IAM -0.6% Global Medium-term (2–4 yr)
Cybersecurity skills shortage -0.5% Global Medium-term (2–4 yr)
False positives and customer friction -0.4% Global Short-term (≤2 yr)
Budget constraints among smaller buyers -0.3% Emerging markets Short-term (≤2 yr)

Privacy Limits on Behavioral and Biometric Data

Risk engines depend on collecting granular behavioral data, and privacy law constrains how long and why it can be stored. India's Digital Personal Data Protection Act 2023 requires purpose limitation and explicit consent [20], while the EU AI Act places strict obligations on biometric categorization [21]. Vendors must localize data and document lawful bases, lengthening sales cycles in regulated jurisdictions.

Integration Complexity with Legacy IAM

Many organizations run several directories, homegrown single sign-on and mainframe applications that cannot expose session context. CISA's maturity model acknowledges that most agencies remain at "initial" identity maturity [9]. Feeding clean signals into a risk engine often requires directory consolidation first, adding months and consulting spend before any fraud benefit appears.

Cybersecurity Skills Shortage

Tuning risk thresholds, examining flagged sessions, checking model bias all call for scarce knowledge. The global cybersecurity workforce shortfall was 4.8 million workers as of 2024, according to ISC2 [15]. Organizations that don't have analysts prefer to leave policies at vendor defaults, which limits value and slows expansion into new use cases.

False Positives and Customer Friction

Overly-sensitive models obstruct legitimate customers, increase call-center loads and cause cart abandonment. Under EU standards, fraud rates over thresholds mean providers lose exemption privileges yet tighter controls increase challenge rates [5]. But the balance of these factors makes some merchants unwilling to extend risk-based flows beyond high-value transactions.

Budget Constraints Among Smaller Buyers

Small banks, cooperatives and merchants in emerging economies often lack budgets for enterprise-grade platforms. Supervisory frameworks such as the Saudi Central Bank's Cyber Security Framework raise expectations without funding implementation [25]. Price sensitivity pushes these buyers toward basic one-time-password tools, slowing upgrade cycles.

Risk-based Authentication Market Opportunities

Five opportunity areas stand out for vendors and investors in the Risk-Based Authentication Market.

Real-Time Payment Rails in Emerging Markets

India's UPI processed more than 170 billion transactions in 2024 [18], and Brazil's Pix now serves well over 150 million users [19]. Instant, irrevocable payments leave no window for manual review, so issuers need sub-second risk decisions on every transfer. Vendors offering lightweight SDKs priced per transaction can capture banks and fintechs across South Asia, Latin America and Southeast Asia.

Risk Signals as a Service

It’s turning the consortium data into a commodity itself. Organizations too small to train their own models can use Fraud Risk Scoring Systems from providers that aggregate anonymized device, mule-account, and session intelligence across banks. This transfers revenue from licensing fees to high gross margin, usage-based data subscriptions, assuming privacy-preserving techniques pass muster with authorities.

Digital Identity Wallet Integration

The revised eIDAS Regulation requires every EU member state to offer a European Digital Identity Wallet [17]. Relying parties will need to evaluate wallet presentations alongside device and behavioral risk, creating demand for orchestration layers that combine verified credentials with real-time scoring.

Managed Services for SMEs

Small enterprises want enterprise-grade protection without the analyst. Risk Based Authentication Market is estimated to witness 8.7% CAGR growth for Small and Medium Enterprises. Managed service providers that bundle risk-based login with email security and endpoint monitoring can tap into this market at scale.

Machine and Agent Identities

Software agents increasingly initiate payments, API calls and data transfers on behalf of users. Extending risk scoring to non-human identities, including delegated AI agents, opens a new category where few incumbents have mature products.

Risk-based Authentication Market Future Outlook

Four themes will shape the Risk Based Authentication Market over the next decade.

AI Versus AI: Deepfakes and Agentic Identities

Generative AI lets attackers clone voices, faces and writing styles, eroding trust in help-desk resets and video verification. Defenders are responding with liveness detection and behavioral models that look for machine-generated patterns. In parallel, AI agents acting for users will need scoped delegation and per-action risk checks, turning authentication into a continuous negotiation between humans, agents and services [4].

Passwordless by Default

The FIDO Alliance reports that more than 15 billion online accounts can now use passkeys [16]. As passwords disappear, risk engines shift focus from the login moment to account recovery, device enrollment and in-session behavior. Vendors that pair phishing-resistant credentials with session-level scoring will capture the architecture that replaces passwords entirely.

Platform Consolidation

Buyers want one policy layer across workforce, customer and machine identities. Acquisitions such as Thales–Imperva and Cisco–Splunk show large vendors assembling identity, data-security and telemetry assets under one roof [23][24]. Over the forecast period, standalone point tools will either specialize deeply or be absorbed into broader identity security platforms.

Regulatory Convergence and Digital Identity Wallets

NIST SP 800-63-4 [10], the EU digital identity wallet [17] and payment rules in India and the Gulf are converging on the same principle: authentication strength should match transaction risk. That convergence lowers compliance fragmentation for global vendors and makes risk-based logic the default expectation rather than an optional enhancement.

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America 36.8% share Zero trust mandates, banking fraud, healthcare access
Europe USD 1.62 Billion PSD2 SCA, DORA, NIS2, digital identity wallets
Asia-Pacific 8.9% CAGR Real-time payments, mobile banking, data localization
South America 5.1% share Pix fraud controls, mobile-first banking
Middle East & Africa USD 0.38 Billion Central bank cyber frameworks, digital government
Total USD 5.92 Billion —

Regional performance in the Risk Based Authentication Market tracks regulatory intensity, digital payment penetration and cloud maturity.

North America

Country Key Metric (2025) Key Driver
United States 84.5% share of region Federal zero trust mandates and bank fraud losses
Canada 7.6% CAGR OSFI technology and cyber risk guideline B-13
Mexico USD 0.12 Billion Digital banking growth and CNBV security rules

United States demand rests on three pillars: federal zero trust deadlines [8], card-not-present and authorized-push-payment fraud, and proposed HIPAA updates requiring stronger access controls [11]. Canada's OSFI guideline B-13, effective January 2024, pushed federally regulated banks to formalize identity risk controls. Mexico's growth reflects rapid uptake of digital accounts and a rising volume of SIM-swap fraud that defeats SMS codes.

Europe

Country Key Metric (2025) Key Driver
Germany 22.8% share of region BaFin supervisory expectations and NIS2 transposition
United Kingdom USD 0.34 Billion APP scam reimbursement rules
France 7.3% CAGR ACPR enforcement of SCA and e-commerce growth
Italy 9.6% share of region Public digital identity (SPID) integration
Spain USD 0.12 Billion Instant payment adoption via Bizum
Nordic Countries 7.8% CAGR BankID ecosystems and mobile-first banking
Russia 5.2% share of region Domestic vendor substitution and payment fraud
Rest of Europe USD 0.21 Billion DORA compliance among mid-sized institutions

European spending is regulation-led. DORA, applicable since January 2025, obliges financial entities to manage ICT risk, including access controls [12], while NIS2 exposes essential entities to fines of up to EUR 10 million or 2% of turnover [13]. The UK's reimbursement requirement, capped at GBP 85,000 per claim since October 2024, shifted fraud liability onto payment providers and accelerated behavioral analytics purchases [14].

Asia-Pacific

Country Key Metric (2025) Key Driver
China 33.5% share of region Super-app payments and PIPL-compliant analytics
India 11.2% CAGR RBI authentication directions and UPI volumes
Japan USD 0.27 Billion Brokerage account-takeover incidents prompting MFA mandates
South Korea 10.4% share of region Financial supervisory rules and mobile banking
ASEAN 10.1% CAGR Real-time payment links and MAS technology risk guidance
Rest of Asia-Pacific USD 0.10 Billion Digital banking licenses in Australia and New Zealand

India is the growth engine: RBI's 2025 directions explicitly allow risk-based additional factors [7], and UPI volume exceeding 170 billion transactions in 2024 creates enormous scoring demand [18]. Japan saw a wave of brokerage account hijackings in 2025 that led securities firms to mandate stronger login verification. Singapore's technology risk guidelines continue to set the regional benchmark for ASEAN banks.

South America

Country Key Metric (2025) Key Driver
Brazil 58.0% share of region Pix fraud controls and Central Bank security rules
Argentina 7.9% CAGR Fintech wallet expansion
Rest of South America USD 0.06 Billion Mobile banking growth in Chile, Colombia and Peru

Brazil dominates because Pix made instant transfers ubiquitous and fraudsters followed [19]. The Central Bank responded with device-registration requirements and nighttime transaction limits, pushing banks toward device-bound risk scoring. Argentina's growth tracks the rise of digital wallets amid high inflation, where users shift funds rapidly, and fraud windows are short.

Middle East & Africa

Country Key Metric (2025) Key Driver
Saudi Arabia 9.6% CAGR SAMA Cyber Security Framework and Vision 2030 digitization
United Arab Emirates 26.5% share of region Central bank phase-out of SMS and email OTPs
South Africa USD 0.07 Billion Banking fraud and POPIA compliance
Egypt 8.4% CAGR Instapay instant payment growth
Rest of Middle East & Africa 18.0% share of region Mobile money security in East and West Africa

Gulf regulators are moving fastest. The Saudi Central Bank's framework sets mandatory identity and access controls for financial institutions [25], and the Central Bank of the UAE directed banks to phase out SMS and email one-time passwords in favor of in-app and behavioral methods. South Africa's market reflects persistent banking-app fraud, while Egypt's instant payment network is lifting demand among retail banks.

Risk-based Authentication Market By Region, 2025-2035

Risk-based Authentication Market Segmentation

By Offering

Segment Key Metric (2025) Primary Demand Driver
Solution 71.4% share Platform licenses in banking and government
Service 8.6% CAGR Managed tuning, integration and compliance advisory

Within the Risk-Based Authentication Market, Solution licenses remain the revenue core because banks and agencies buy risk engines as part of multi-year identity platform contracts. Service is growing faster as organizations outsource model tuning, bias audits and regulatory mapping rather than hiring scarce analysts. Advisory demand is strongest where rules change quickly, such as PSD2 exemption management in Europe and HIPAA alignment in US hospitals, and vendors increasingly bundle SLA-backed managed detection into software subscriptions.

By Deployment

Segment Key Metric (2025) Primary Demand Driver
On-Premise 33.5% share Defense, public sector and air-gapped networks
Cloud 8.8% CAGR SaaS identity platforms and multi-cloud zero trust

Cloud is both the dominant and the fastest-growing deployment model in the Risk-Based Authentication Market. Elastic scaling, cross-tenant threat intelligence and geographic redundancy suit zero trust programs that validate every session wherever users sit. On-Premise persists in classified and sovereignty-sensitive environments but faces slower refresh cycles and higher maintenance costs. Vendors are narrowing the gap by offering data-residency controls and deployable policy engines that run identically on public clouds and private Kubernetes clusters.

By Authentication Method

Segment Key Metric (2025) Primary Demand Driver
Knowledge-Based Authentication 3.9% CAGR Legacy fallback and account recovery
Possession-Based Authentication USD 1.12 Billion Hardware tokens in defense and critical infrastructure
Inherence-Based (Biometric) Authentication 14.2% share Mobile biometrics in consumer banking
Multi-Factor and Composite Authentication 40.1% share Compliance recognition across regulated sectors
Adaptive Behavioral Authentication 7.4% CAGR Invisible, context-aware checks reducing friction

Multi-Factor and Composite Authentication leads the Risk Based Authentication Market because auditors and regulators recognize it explicitly. Adaptive Behavioral Authentication is gaining fastest as vendors blend device telemetry, location and micro-behavioral cues to trigger step-up only when needed, cutting login time materially compared with blanket prompts. Knowledge-Based Authentication grows slowest as phishing exposes static secrets, while possession-based tokens hold steady in defense and utilities.

By Organization Size

Segment Key Metric (2025) Primary Demand Driver
Large Enterprises 61.5% share Extensive IT budgets and strict audit regimes
Small and Medium Enterprises 8.7% CAGR SaaS tiers, low-code connectors and MSP bundles

Large Enterprises control the majority of Risk Based Authentication Market revenue, reflecting complex workforces, regulated data and dedicated security operations teams. Small and Medium Enterprises are expanding faster because SaaS dashboards, templated rule sets and usage-based pricing now deliver controls once reserved for global firms. Managed service providers amplify the shift by packaging risk-based login with email and endpoint protection, giving smaller firms an integrated defense without full-time analysts.

By End-User Vertical

Segment Key Metric (2025) Primary Demand Driver
Banking and Financial Services 27.6% share SCA, AML and fraud-loss liability
Retail USD 0.91 Billion Checkout fraud and account takeover in loyalty programs
Government 15.8% share Zero trust mandates and citizen e-services
Healthcare 7.3% CAGR EHR portals, telehealth and HIPAA updates
IT and Telecom 7.0% CAGR SIM-swap fraud and workforce access
Others USD 0.55 Billion Education, energy and manufacturing access control

Banking and Financial Services anchors the Risk Based Authentication Market because payment regulation and fraud reimbursement rules make losses directly visible on the balance sheet. Healthcare grows fastest as clinicians need low-friction access during emergencies and pharmacies embed risk checks into prescription authorization to detect diversion. Retail spending concentrates on checkout and loyalty-account protection, while government demand follows zero trust deadlines.

Competitive Benchmarking

The Risk Based Authentication Market is moderately concentrated, with an estimated HHI near 850 and the top five vendors holding roughly 38–44% of revenue. Large identity platforms compete with specialist fraud and behavioral-analytics firms, and consolidation continues as buyers favor unified policy layers.

Company Est. Revenue Share Range Key Offerings for Risk Based Authentication Strategic Positioning
Microsoft Corporation ~9–12% Entra ID Protection, Conditional Access Bundled identity risk across Microsoft 365 and Azure
Okta, Inc. ~8–11% Adaptive MFA, Identity Threat Protection Independent cloud identity leader for workforce and customer
Ping Identity ~6–8% PingOne Protect, ForgeRock Autonomous Access Enterprise and hybrid identity after ForgeRock combination
IBM Corporation ~5–7% IBM Security Verify, Trusteer Fraud analytics strength in global banking
Broadcom Inc. ~5–7% Symantec VIP, Advanced Authentication Large-enterprise and mainframe installed base
Cisco Systems (Duo Security) ~4–6% Duo Trust Monitor, Risk-Based Authentication Zero trust access with Splunk telemetry
RSA Security LLC ~4–6% RSA ID Plus, Risk AI Regulated and public-sector workforce identity
Thales Group ~4–6% SafeNet Trusted Access, OneWelcome Identity plus data security after Imperva acquisition
OneSpan Inc. ~3–5% Intelligent Adaptive Authentication Banking-focused transaction risk and signing
OpenText (Micro Focus) ~2–4% NetIQ Advanced Authentication Hybrid IAM for legacy-heavy enterprises

Recent News & Developments

  • Okta (October 2023): Announced Identity Threat Protection with Okta AI, extending risk evaluation beyond login to continuous session monitoring and automated revocation [22]
  • Thales (December 2023): Completed its acquisition of Imperva, combining application and data security with its identity portfolio to deepen cross-sell into authentication buyers [23]
  • Cisco (March 2024): Closed its acquisition of Splunk, giving Duo access to rich security telemetry for identity risk decisions [24]
  • UK Payment Systems Regulator (October 2024): Mandatory reimbursement for authorized push payment fraud took effect, shifting liability to banks and accelerating behavioral fraud analytics [14]
  • European Union (January 2025): DORA became applicable, formalizing ICT risk and access-control obligations for financial entities [12]
  • US Department of Health and Human Services (January 2025): Published proposed HIPAA Security Rule updates making multi-factor authentication a baseline requirement [11]
  • NIST (August 2025): Released final SP 800-63-4 Digital Identity Guidelines, endorsing risk-based assurance and phishing-resistant options [10]
  • Reserve Bank of India (September 2025): Issued directions on authentication for digital payments that permit risk-based additional factors beyond SMS OTP [7]

Risk-based Authentication Market Report Scope

Parameter Details
Market Scope The Risk Based Authentication Market covers solutions and services, cloud and on-premise deployment, and authentication methods used by enterprises of all sizes across banking, retail, government, healthcare and other verticals
Study Period 2021–2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 5.92 Billion
Market Size in 2035 USD 11.75 Billion
CAGR (2026–2035) 7.1%
Fastest Growing Segments Cloud (8.8% CAGR); Small and Medium Enterprises (8.7% CAGR); Service (8.6% CAGR); Healthcare (7.3% CAGR)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled Microsoft Corporation, Okta Inc., Ping Identity, IBM Corporation, Broadcom Inc., Cisco Systems, RSA Security LLC, Thales Group, OneSpan Inc., OpenText
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

How should buyers shortlist vendors in the Risk Based Authentication Market?
Run a 30–60 day pilot and measure false-positive and step-up rates on your own traffic, not vendor benchmarks. Contracts should also guarantee model retraining frequency and exportable risk logs for audits [10].
What integration problem delays most deployments?
Fragmented directories and legacy single sign-on stacks are the usual bottleneck, because risk engines need clean identity and session data. Consolidating directories before rollout typically shortens implementation by several months.
Will passkeys make risk-based authentication unnecessary?
No. Passkeys harden the login itself, but session hijacking, account recovery and push-payment scams still need scoring after sign-in, which keeps demand in the Risk Based Authentication Market intact [16].
How does the EU AI Act treat behavioral risk engines?
Biometric verification used only to confirm a claimed identity sits outside the Act's high-risk list. Vendors that extend behavioral data into emotion recognition or categorization face far stricter obligations [21].
Which emerging use cases attract investment in the Risk Based Authentication Market?
AI agents that initiate payments and API calls for users are the newest frontier. Vendors are building delegation tokens and agent-level risk scores to verify these machine identities.
Which pricing models dominate procurement?
Per-monthly-active-user subscriptions lead workforce and consumer deals across the Risk Based Authentication Market. Banks often negotiate per-transaction pricing linked to fraud-loss outcomes instead.
What should investors watch in the Risk Based Authentication Market over the next three years?
Consolidation is the key signal, as platform vendors acquire behavioral-analytics and identity threat detection specialists. Net revenue retention above 110% marks vendors successfully cross-selling risk scoring into existing identity contracts [22].
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Global Diameter Signaling Market
Case Study
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















