Renewable Aviation Fuel Market (2026 - 2035)

Renewable Aviation Fuel Market Research Report Information By Feedstock (Used Cooking Oil and Waste Fats, Industrial CO₂ and Green H₂, Municipal Solid Waste, Agricultural Residues and Energy Crops, Others (Algae, Forestry Residues)), By Technology (Hydroprocessed Esters and Fatty Acids (HEFA), Alcohol-to-Jet (ATJ), Power-to-Liquid / E-SAF, Gasification + Fischer-Tropsch, Others (DSHC, CHJ)), By Blending Level (Up to 10% Blend, 10 to 50% Blend, 50 to 100% Blend), By Application (Commercial Airlines, Cargo and Freight, Business and General Aviation, Military and Government) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035
ID: MRFR/EnP/39922-HCR 128 Pages Chitranshi Jaiswal Last Updated: September 17, 2026
Renewable Aviation Fuel Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)33.8%
2025 Market SizeUSD 2.38 Billion
2035 Market SizeUSD 52.68 Billion
Key Players
Neste Oyj
TotalEnergies SE
Phillips 66
Gevo Inc.
World Energy
Montana Renewables
Opportunities
  • SAF from Municipal Solid Waste ATJ Pathways
  • Emerging-Market Production Hubs
  • Data-Driven SAF Procurement and Lifecycle Analytics
 

Renewable Aviation Fuel Market Summary

The Renewable Aviation Fuel Market reached an estimated USD 2.38 billion in 2025, with the forecast period opening at USD 3.42 billion in 2026 and climbing to USD 52.68 billion by 2035 at a CAGR of 33.8%. This rapid expansion reflects a decisive shift from voluntary sustainability pledges to binding compliance frameworks — the European Union's ReFuelEU Aviation regulation now mandates a 2% sustainable aviation fuel blending obligation from 2025 rising to 6% by 2030, while the U.S. Inflation Reduction Act's Section 45Z production tax credits have unlocked over USD 5 billion in announced SAF plant investments across the Gulf Coast and Midwest[2]. Airlines are no longer treating SAF procurement as a reputational exercise; it has become a strategic imperative backed by multi-decade offtake agreements.

The technology landscape within the Renewable Aviation Fuel Market is undergoing a generational transition. Hydroprocessed esters and fatty acids pathways still dominate production, converting used cooking oil and tallow into drop-in jet fuel, but alcohol-to-jet and power-to-liquid e-fuel aviation platforms are scaling rapidly. Solid-oxide electrolysis paired with modular Fischer-Tropsch reactors has cut the SAF cost premium vs jet fuel from 4× to roughly 2.5× at demonstration-scale facilities, and the first commercial power-to-liquid plants in Norway and Chile are targeting final investment decisions in 2026 [3][4].

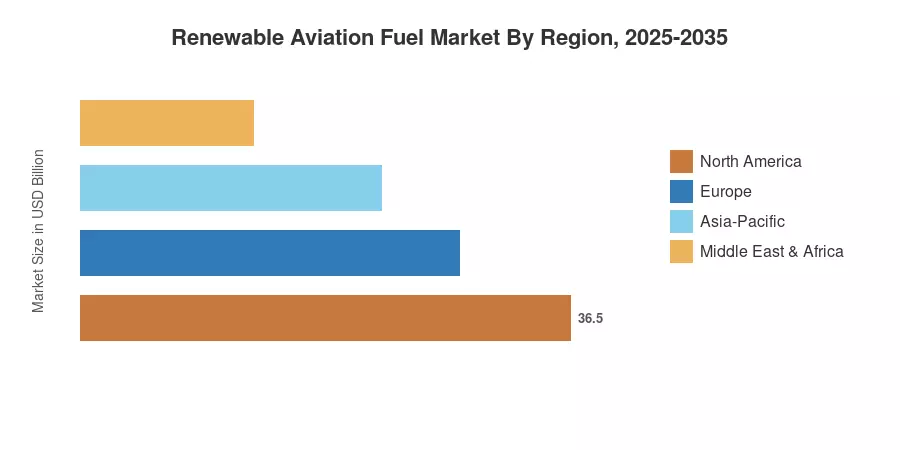
North America commanded a 45.2% share of the Renewable Aviation Fuel Market in 2025, anchored by production capacity in Louisiana, Texas, and California. Europe is the fastest-growing region with a projected CAGR of 39.5% through 2035, propelled by the ReFuelEU SAF blending mandate that airline operators must satisfy. Asia-Pacific held the second-largest share at approximately 18.4%, with Japan and South Korea introducing national blend targets that will reshape Pacific Rim supply chains over the coming decade [5][6].


Key Report Takeaways

• By Feedstock

  • Used cooking oil and waste fats captured 43.1% of the Renewable Aviation Fuel Market in 2025, reflecting mature HEFA supply chains and favorable feedstock economics
  • Industrial CO₂ and green hydrogen feedstocks are projected to register a 54.6% CAGR from 2026 to 2035, driven by falling electrolyzer costs and carbon capture deployment


• By Technology

  • Hydroprocessed esters and fatty acids accounted for 74.2% share of the Renewable Aviation Fuel Market in 2025, underscoring the pathway's ASTM D7566 certification advantage
  • Power-to-liquid e-fuel aviation technology is anticipated to grow at a 51.3% CAGR through 2035, making it the fastest-expanding conversion pathway

• By Region

  • North America generated a 45.2% share of the Renewable Aviation Fuel Market in 2025, led by U.S. refinery conversions and blender's tax credits
  • Europe is projected to record a 39.5% CAGR through 2035, fueled by mandatory SAF blending mandate airline compliance schedules across 27 member states


Market Size and Forecast (2021–2035)

MRFR's sizing methodology combines bottom-up production capacity modeling with top-down demand estimates from IATA fuel-burn statistics, cross-validated against SAF certification ASTM D7566 approved volumes, and import/export trade data. Historical figures reflect actual production and offtake, while forecast values incorporate announced capacity, policy mandates, and technology cost curves.
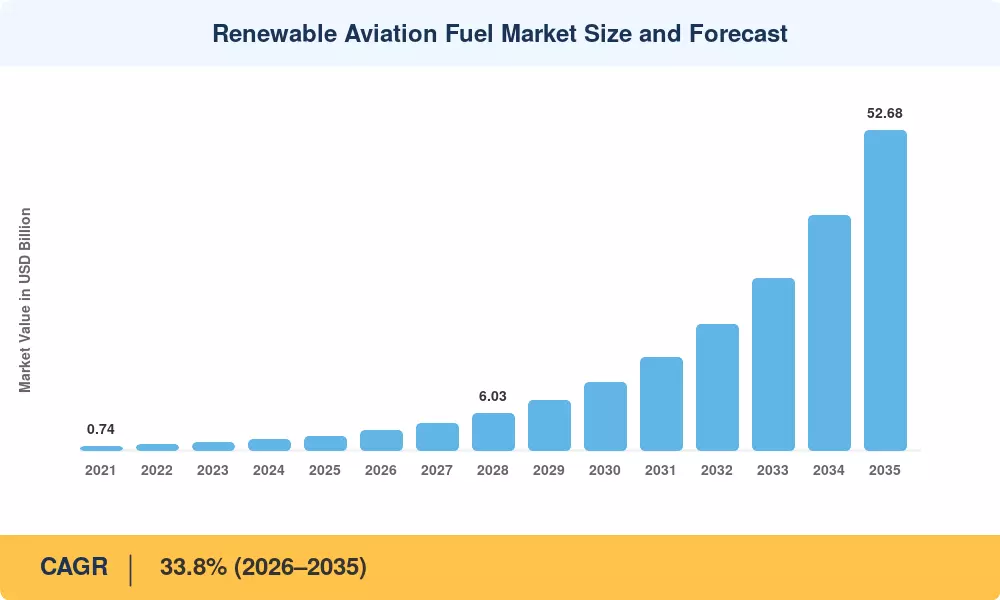
Renewable Aviation Fuel Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry


Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Mandatory SAF blending mandates (ReFuelEU, U.S. SAF Grand Challenge) ~22% Global Short-term (≤2 yr)
Section 45Z / IRA production tax credits ~18% North America Short-term (≤2 yr)
Corporate net-zero pledges and Scope 3 reporting ~15% Global Medium-term (2–4 yr)
Power-to-liquid cost reduction via solid-oxide electrolysis ~14% Europe, Asia-Pacific Medium-term (2–4 yr)
Airport SAF blending infrastructure investment ~12% Europe, North America Long-term (≥4 yr)
CORSIA Phase 2 compliance requirements ~10% Global Long-term (≥4 yr)
Feedstock diversification (MSW, forestry residues, algae) ~9% Asia-Pacific, South America Long-term (≥4 yr)


Mandatory SAF Blending Mandates

The ReFuelEU Aviation rule is the most prominent policy driver for the Renewable Aviation Fuel Market. Starting from 2025 with a 2% volumetric requirement, the obligation will increase to 6% in 2030 and 70% in 2050, establishing a legally enforced demand floor that de-risks SAF investment across Europe. The U.S. SAF Grand Challenge aims for 3 billion gallons of domestic annual production by 2030, with a total of USD 4.3 billion in financing pledges from the DOE, USDA, and DOT [2][10]. The mandates turn uncertain voluntary demand into bankable contracted volumes.


Production Tax Credits and Fiscal Incentives

U.S. SAF tax credit the U.S. Inflation Reduction Act’s Section 45Z clean-fuel production credit gives up to USD 1.75 per gallon for SAF that achieves a minimum 50% lifecycle greenhouse-gas reduction over petroleum jet fuel. This incentive has attracted more than USD 5 billion of announced investment for refinery conversions and greenfield SAF plants along the Gulf Coast since 2023. Similarly, Canada’s Clean Fuel Regulations and the UK’s Revenue Certainty Mechanism progressively offset the SAF cost premium vs jet fuel by fiscal transfers rather than airline ticket surcharges alone [4][15].


Airport Infrastructure Build-Out

Dedicated SAF blending and storage infrastructure at key hubs, such as Amsterdam Schiphol, Los Angeles International, Frankfurt, Paris-CDG, and Singapore Changi, can replace truck-in blending and storage and save last-mile logistics costs by 8–12%. There’s a network effect to SAF adoption, where upgrades have been committed to airport fuel systems of more than $1.2 billion through 2028, making SAF adoption self-reinforcing as more airports come into the infrastructure footprint [13].


Restraints Impact Analysis

The restraint impacts below are directional estimates of headwinds that temper the headline CAGR. They represent dampening forces, not absolute subtractions from the growth rate.

Restraint ~% Negative Impact on CAGR Geographic Relevance Impact Timeline
SAF cost premium vs jet fuel (2–3× conventional) ~(–8%) Global Short-term (≤2 yr)
Feedstock supply bottleneck (used cooking oil, tallow) ~(–6%) Europe, Asia-Pacific Medium-term (2–4 yr)
SAF certification ASTM D7566 pathway approval lag ~(–5%) Global Medium-term (2–4 yr)
Green hydrogen electrolyzer capacity constraints ~(–4%) Europe Long-term (≥4 yr)
Indirect land-use change (ILUC) sustainability scrutiny ~(–3%) Global Long-term (≥4 yr)


Feedstock Availability and Competition

The biodiesel, renewable diesel, and oleochemical industries are all vying for the major HEFA feedstock, used cooking oil. European UCO imports from Asia have increased by 40% from 2022 to 2024, creating worries about traceability and fraud. Tallow supplies are limited by animal populations and are naturally limited. This feedstock rivalry limits the possibility of the Renewable Aviation Fuel Market to develop the HEFA capacity beyond roughly 8 million tonnes per year globally without diversification into SAF from municipal solid waste, ATJ, and lignocellulosic sources [11].


Certification Bottlenecks

Only eleven SAF production pathways have received SAF certification ASTM D7566 approval to date, and the qualification process for new feedstock-technology combinations typically requires 18–36 months of testing. Alcohol-to-jet pathways using ethanol from cellulosic biomass and power-to-liquid e-fuel aviation routes employing novel catalysts face extended timelines, slowing commercial deployment even when the underlying process economics are favorable [12][17].


Renewable Aviation Fuel Market Opportunities


SAF from Municipal Solid Waste ATJ Pathways

Gasification of municipal solid waste followed by alcohol-to-jet conversion provides two benefits: waste diversion from landfills and ASTM-certified fuel. Tokyo and London have piloted MSW-to-SAF plants with a total capacity of 60,000 tonnes per year. The economics improve dramatically when gate fees (tipping charges) are used to offset feedstock costs. The Renewable Aviation Fuel Market will see benefits from the convergence of waste management policies across Asia-Pacific and Europe


Emerging-Market Production Hubs

Brazil's abundant sugarcane ethanol surplus and India's rapidly growing agricultural-residue base create feedstock-advantaged production sites for alcohol-to-jet SAF. Both governments offer fiscal incentives for biofuel producers, and proximity to fast-growing domestic aviation markets reduces logistics costs. The Renewable Aviation Fuel Market could see South America and South Asia emerge as net SAF exporters by the early 2030s

Data-Driven SAF Procurement and Lifecycle Analytics

Airlines and fuel suppliers are investing in digital platforms that track SAF lifecycle emissions, feedstock provenance, and regulatory compliance in real time. These analytics tools enable dynamic SAF blending optimization and generate monetizable sustainability data for corporate ESG reporting. The Renewable Aviation Fuel Market benefits as data transparency reduces greenwashing risk and builds buyer confidence


Renewable Aviation Fuel Market Future Outlook


Feedstock Diversification and Waste-to-Fuel Scale (2028–2032)

As used cooking oil supplies tighten, the Renewable Aviation Fuel Market will pivot toward SAF from municipal solid waste ATJ, forestry residues, and algal lipids. The IEA estimates that global municipal solid waste generation will reach 3.4 billion tonnes by 2030, of which 15–20% is technically convertible to syngas for jet-fuel production. Successful SAF certification ASTM D7566 approvals for novel feedstocks will determine whether these pathways contribute 10% or 30% of the 2035 supply [12][21].

Regulatory Convergence and Global Harmonization (2030–2035)

ICAO's CORSIA scheme transitions from voluntary to mandatory phases in 2027, covering over 80% of international aviation emissions. If major jurisdictions harmonize SAF sustainability criteria — aligning EU RED III, U.S. GREET models, and ICAO's CORSIA Eligible Fuels framework — the resulting regulatory clarity will accelerate cross-border SAF trade and investment. The Renewable Aviation Fuel Market's long-term trajectory depends on whether this harmonization occurs by 2030 or is delayed by geopolitical fragmentation [10][22].


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 45.2% share (2025) Refinery conversions, Section 45Z credits, SAF Grand Challenge
Europe 39.5% CAGR (2026–2035) ReFuelEU mandate, power-to-liquid e-fuel aviation, airport blending
Asia-Pacific USD 0.44 Billion (2025) National blend targets, ATJ from agricultural residues
South America 12.8% CAGR (2026–2035) Sugarcane ethanol-to-jet, biofuel policy integration
Middle East & Africa USD 0.05 Billion (2025) Oil-major SAF pivots, solar-powered hydrogen
Total USD 2.38 Billion (2025) —

The Renewable Aviation Fuel Market exhibits pronounced geographic concentration today, with North America and Europe accounting for a combined 75% of global production and consumption. However, Asia-Pacific governments are rapidly introducing SAF blending mandate airline compliance timelines, and emerging regions are positioning around feedstock advantages.


North America

Country Key Metric Key Driver
US 82.4% of regional share Section 45Z credits, Gulf Coast HEFA refinery conversions
Canada CAGR 35.8% Clean Fuel Regulations, forestry-residue ATJ pilots
Mexico USD 0.02 Billion (2025) Pemex biorefinery partnerships, CORSIA compliance


The United States drives the bulk of North American Renewable Aviation Fuel Market activity through a combination of production tax credits, low-carbon fuel standard programs in California and Washington, and strategic SAF offtake agreements signed by Delta, United, and American Airlines. Montana Renewables' 300-million-gallon HEFA facility in Great Falls became the world's largest dedicated SAF plant in 2024, while Phillips 66's Rodeo Renewed refinery in California began co-processing renewable feedstocks at commercial scale [4][6].

Europe

Country Key Metric Key Driver
Germany USD 0.11 Billion (2025) PtL mandates, Lufthansa SAF commitments
UK 41.2% CAGR Revenue Certainty Mechanism, Altalto Immingham plant
France 18.3% of regional share Air France–KLM SAF surcharge, TotalEnergies HEFA
Italy CAGR 36.4% ENI biorefinery conversions, Fiumicino blending hub
Spain USD 0.04 Billion (2025) Repsol e-SAF pilot, Bilbao synthetic fuels plant
Nordic Countries 44.7% CAGR Offshore wind hydrogen, SAS and Finnair offtake
Russia USD 0.01 Billion (2025) Limited domestic activity; sanctions constrain investment
Rest of Europe CAGR 33.9% Diverse national implementation of ReFuelEU


Europe's Renewable Aviation Fuel Market growth is structurally anchored by the ReFuelEU Aviation regulation, which creates a mandatory SAF blending mandate that airline operators cannot circumvent through carbon offsets alone. Germany's dedicated power-to-liquid sub-mandate — requiring 0.5% e-SAF by 2030 — is the world's first technology-specific obligation and has catalyzed investment in Haru Oni–style synthetic fuel plants. Airports in Amsterdam, Paris, and Frankfurt have invested a combined EUR 650 million in dedicated SAF storage and hydrant blending infrastructure [2].

Asia-Pacific

Country Key Metric Key Driver
China 28.6% of regional share CAAC SAF pilot program, Sinopec HEFA refinery
India CAGR 42.3% National biofuel policy, ethanol-to-jet from sugarcane
Japan USD 0.09 Billion (2025) ACT-for-SAF consortium, MSW gasification pilots
South Korea 38.7% CAGR Korean Air SAF mandate roadmap, SK Innovation plants
ASEAN USD 0.04 Billion (2025) Palm oil HEFA, Singapore Changi blending hub
Rest of Asia-Pacific CAGR 29.1% Early-stage policy development


Asia-Pacific represents the Renewable Aviation Fuel Market's most dynamic growth frontier. Japan's ACT-for-SAF public-private consortium has committed JPY 300 billion to domestic SAF production, targeting 10% blend by 2030. India's plan to integrate SAF into its existing ethanol blending infrastructure leverages the country's 1,200+ sugar mills as potential alcohol-to-jet feedstock suppliers [11].

South America

Country Key Metric Key Driver
Brazil 71.5% of regional share Sugarcane ethanol surplus, LATAM Airlines SAF offtake
Argentina CAGR 15.2% Soybean oil HEFA, national biofuel mandates
Rest of South America USD 0.01 Billion (2025) Early policy exploration


Brazil's abundant sugarcane ethanol production — exceeding 35 billion litres annually — positions the country as a natural alcohol-to-jet SAF hub. LATAM Airlines signed a 500,000 tonne offtake agreement with local producers in 2024, and Petrobras is exploring integration of SAF production into existing biorefinery complexes [9].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 34.8% of regional share NEOM green hydrogen, Aramco SAF ventures
UAE CAGR 28.5% Masdar clean energy, Abu Dhabi SAF hub
South Africa USD 0.008 Billion (2025) Sasol FT expertise, green corridor ambitions
Egypt CAGR 21.3% Green hydrogen strategy, Suez Canal logistics
Rest of MEA USD 0.005 Billion (2025) Limited current activity


The Middle East & Africa region within the Renewable Aviation Fuel Market is transitioning from negligible activity to strategic positioning. Saudi Arabia's NEOM project envisions large-scale green hydrogen production that could feed power-to-liquid e-fuel aviation synthesis, while the UAE's Masdar has partnered with Etihad Airways to develop a 50,000-tonne SAF plant near Al in using solar-powered electrolysis [13].


Renewable Aviation Fuel Market By Region, 2025-2035
 

Renewable Aviation Fuel Market Segmentation

By Feedstock

Segment Key Metric Primary Demand Driver
Used Cooking Oil and Waste Fats 43.1% share (2025) Established HEFA supply chains, low feedstock cost
Industrial CO₂ and Green H₂ 54.6% CAGR (2026–2035) Electrolyzer cost decline, e-SAF mandates
Municipal Solid Waste USD 0.19 Billion (2025) Waste diversion incentives, dual-revenue model
Agricultural Residues and Energy Crops 31.4% CAGR (2026–2035) Ethanol-to-jet pathway maturation
Others (Algae, Forestry Residues) USD 0.07 Billion (2025) R&D-stage; long-term potential


The Renewable Aviation Fuel Market's feedstock landscape is shifting decisively. Used cooking oil and waste fats remain the dominant input today because they plug directly into proven HEFA refinery configurations with minimal pretreatment. However, supply constraints — UCO availability is capped at roughly 15 million tonnes globally — are forcing producers to diversify. Industrial CO₂ combined with green hydrogen represents the fastest-growing feedstock category, powered by the expansion of power-to-liquid e-fuel aviation plants that capture CO₂ from point sources or direct air capture units and combine it with electrolytic hydrogen via Fischer-Tropsch synthesis.

SAF from municipal solid waste ATJ pathways offer a compelling alternative in densely populated regions where landfill diversion policies create economic incentives. Japan and the UK lead deployment, with combined operational and planned MSW-to-SAF capacity exceeding 120,000 tonnes/year by 2027 [11].

By Technology

Segment Key Metric Primary Demand Driver
Hydroprocessed Esters and Fatty Acids (HEFA) 74.2% share (2025) Drop-in compatibility, mature SAF certification ASTM D7566
Alcohol-to-Jet (ATJ) USD 0.26 Billion (2025) Ethanol feedstock abundance, cellulosic breakthroughs
Power-to-Liquid / E-SAF 51.3% CAGR (2026–2035) Green hydrogen economics, e-SAF sub-mandates
Gasification + Fischer-Tropsch 28.7% CAGR (2026–2035) MSW and biomass valorization
Others (DSHC, CHJ) USD 0.04 Billion (2025) Niche pathways under development


HEFA technology dominates the Renewable Aviation Fuel Market because it leverages existing petroleum-refinery infrastructure with relatively modest capital expenditure for conversion. Major oil companies, including Neste, TotalEnergies, and Phillips 66, have converted brownfield assets to HEFA production, delivering SAF that meets all current sustainable aviation fuel SAF HEFA specifications. The pathway's primary limitation is feedstock dependence on lipid-based inputs whose supply ceiling is approaching.

Power-to-liquid e-fuel aviation technology is the market's most transformative growth vector. By combining direct air capture or industrial CO₂ with green hydrogen, PtL produces synthetic kerosene with lifecycle carbon reductions exceeding 90%. Germany's dedicated 0.5% PtL sub-mandate within ReFuelEU has catalyzed a pipeline of announced European PtL projects totaling 1.8 million tonnes of annual capacity by 2032 [3][7].

By Blending Level

Segment Key Metric Primary Demand Driver
Up to 10% Blend USD 0.38 Billion (2025) Entry-level compliance, CORSIA Phase 1
10 to 50% Blend 82.4% share (2025) ReFuelEU and airline offtake agreement structures
50 to 100% Blend 48.3% CAGR (2026–2035) 100% SAF flight demonstrations, engine OEM approvals


The 10–50% SAF blending mandate airline compliance band captures the dominant share of the Renewable Aviation Fuel Market because most regulatory frameworks and offtake contracts are structured around mid-range blending ratios. The 50–100% blend segment is growing explosively as engine manufacturers — led by Rolls-Royce, CFM International, and Pratt & Whitney — certify powerplants for 100% sustainable aviation fuel SAF HEFA operation by 2030.

By Application

Segment Key Metric Primary Demand Driver
Commercial Airlines 85.1% share (2025) Regulatory mandates, Scope 3 reporting, passenger demand
Cargo and Freight 29.3% CAGR (2026–2035) E-commerce logistics, shipper sustainability requirements
Business and General Aviation USD 0.06 Billion (2025) Corporate travel policies, FBO blending availability
Military and Government 24.8% CAGR (2026–2035) Defense energy security, NATO SAF readiness targets


Commercial airlines dominate the Renewable Aviation Fuel Market by application, reflecting their outsized share of global jet-fuel consumption and direct exposure to SAF blending mandate airline obligations. Major carriers, including United, Delta, Lufthansa, and Singapore Airlines, have signed multi-year offtake agreements collectively exceeding 10 million tonnes through 2035.


Competitive Benchmarking

The Renewable Aviation Fuel Market exhibits medium concentration, with the top five producers accounting for an estimated 52–58% of global SAF output. An approximate HHI of 650–800 indicates a moderately competitive structure, though significant consolidation is expected as integrated oil majors scale refinery conversions and acquire technology-stage entrants. Competitive dynamics increasingly hinge on feedstock security, offtake agreement portfolios, and SAF certification, ASTM D7566 pathway breadth.

Company Est. Revenue Share Range Key Offerings for Renewable Aviation Fuel Market Strategic Positioning
Neste Oyj ~18–22% MY Sustainable Aviation Fuel (HEFA); UCO and animal-fat feedstock Global leader; Singapore, Rotterdam, and Porvoo refineries
TotalEnergies SE ~8–11% La Mède and Grandpuits HEFA; PtL R&D European major leveraging integrated refining assets
Phillips 66 ~6–9% Rodeo Renewed (California); co-processed SAF U.S. refinery conversion pioneer
Gevo Inc. ~3–5% Alcohol-to-jet Net-Zero 1 (South Dakota) First commercial-scale ATJ producer in North America
World Energy ~4–6% Paramount, California HEFA facility Longest-operating commercial SAF plant in the world
Montana Renewables ~3–5% Great Falls HEFA mega-facility (300M gal/yr) Scale-focused; feedstock diversification strategy
SkyNRG ~2–4% SAF procurement, DSL-01 (Netherlands) Demand aggregation and supply-chain orchestration
Twelve (formerly Opus 12) ~1–3% CO₂-to-SAF electrochemistry; E-Jet platform Deep-tech PtL; backed by Microsoft and Alaska Airlines
LanzaJet ~2–4% ATJ (Freedom Pines, Georgia); Lanzanol technology Ethanol-to-jet pathway leader
bp Plc ~3–5% Cherry Point conversion (Washington); Air bp SAF supply Global fuel distributor with refinery conversion assets


Recent News & Developments

  • Neste (March 2025): Completed its 1.6 billion EUR Singapore refinery expansion, lifting total site capacity to 2.6 million tonnes annually. This milestone includes a dedicated 1.0 million tonnes/year allocation specifically for Sustainable Aviation Fuel, establishing a massive regional export hub to service global mandates.
  • European Commission (January 2025): Published implementing rules for ReFuelEU Aviation, finalizing reporting obligations and sustainability criteria for the SAF blending mandate airline operators must meet starting 2025 [2].


  • LanzaJet (September 2024): Confirmed full operational status and successfully produced ASTM on-spec fuels at its flagship LanzaJet Freedom Pines Fuels plant in Soperton, Georgia. The commercial milestone launched the world's first industrial-scale alcohol-to-jet facility capable of processing alternative ethanol feedstocks.
  • Twelve (June 2024): Secured USD 645 million in Series C funding to scale its CO₂-to-SAF electrochemistry platform, with investors including TPG Rise Climate and Microsoft's Climate Innovation Fund [19].


Renewable Aviation Fuel Market Report Scope

Parameter Detail
Market Scope Global Renewable Aviation Fuel Market across all feedstocks, technologies, blending levels, applications, and regions
Study Period 2021–2035
CAGR (Forecast Period) 33.8% (2026–2035)
Market Size (2025) USD 2.38 Billion
Market Size (2035) USD 52.68 Billion
Fastest Growing Segments Power-to-Liquid / E-SAF (by technology); Industrial CO₂ and Green H₂ (by feedstock); Europe (by region)
Companies Profiled 10 (Neste, TotalEnergies, Phillips 66, Gevo, World Energy, Montana Renewables, SkyNRG, Twelve, LanzaJet, bp Plc)
Valuation Currency USD Billion

FAQs

How does sustainable aviation fuel SAF HEFA differ from power-to-liquid e-fuel aviation in carbon reduction?
HEFA SAF typically achieves 50–80% lifecycle CO₂ reductions depending on feedstock origin, while power-to-liquid e-fuel aviation using direct air capture and green hydrogen can exceed 90% reductions. The gap narrows as HEFA producers shift to lower-ILUC feedstocks [3].
What is the minimum SAF blend ratio an airline must adopt under ReFuelEU?
The ReFuelEU mandate starts at 2% volumetric blend in 2025, increases to 6% by 2030, and escalates to 70% by 2050 — with a dedicated sub-quota for synthetic e-SAF beginning in 2030 [2].    
How do airlines hedge against the SAF cost premium vs jet fuel?
Carriers use long-term offtake agreements with fixed or indexed pricing, supplement procurement with book-and-claim certificates, and pass partial costs through voluntary passenger surcharges averaging USD 1–3 per ticket [9].
Which Renewable Aviation Fuel Market feedstock faces the highest supply-chain risk?
Used cooking oil faces the greatest risk due to finite global supply, competing demand from renewable diesel, and documented traceability fraud in Asian export chains .
What role does the Renewable Aviation Fuel Market play in CORSIA compliance?
SAF is the primary compliance mechanism under CORSIA Phase 2 because it delivers verifiable in-sector emission reductions, unlike carbon offsets, which face additionality scrutiny [10].
How does SAF certification ASTM D7566 affect the Renewable Aviation Fuel Market timeline for new technologies?
Each new pathway requires 18–36 months of engine compatibility and emissions testing before ASTM approval, creating a regulatory lag that delays commercial production of novel SAF routes [12].    
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed energy journals, aviation industry publications, and authoritative environmental organizations. Key sources included the International Air Transport Association (IATA), International Civil Aviation Organization (ICAO), US Department of Energy (DOE), US Environmental Protection Agency (EPA), European Union Aviation Safety Agency (EASA), European Commission Directorate-General for Energy, International Energy Agency (IEA), International Renewable Energy Agency (IRENA), US Federal Aviation Administration (FAA), National Renewable Energy Laboratory (NREL), US Energy Information Administration (EIA), World Bioenergy Association (WBA), Roundtable on Sustainable Biomaterials (RSB), ASTM International, CORSIA (Carbon Offsetting and Reduction Scheme for International Aviation), US Department of Agriculture (USDA), EU Eurostat Energy Database, OECD-FAO Agricultural Outlook, and national aviation authority reports from key markets. These sources were used to collect production capacity statistics, regulatory certification data (ASTM D7566, DEF STAN 91-91), feedstock availability studies, carbon intensity lifecycle analyses, SAF offtake agreements, refinery infrastructure data, and market landscape analysis for biofuels, synthetic fuels (e-fuels), hydrogenated vegetable oil (HVO), and Fischer-Tropsch synthetic paraffinic kerosene (FT-SPK) pathways.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. CEOs, Chief Sustainability Officers, VPs of Technology Development, regulatory affairs chiefs, and commercial directors from renewable fuel producers, oil majors with SAF divisions, and aviation fuel OEMs comprised supply-side sources. The demand-side sources included chief procurement officers, sustainability directors, fleet managers, and fuel sourcing representatives from commercial airlines, cargo carriers, military aviation fuel procurement divisions, and airport fuel farm operators. The primary research conducted validated market segmentation, confirmed the commissioning timelines of production facilities, and collected information on the requirements for blending infrastructure, offtake contract structures, and pricing premiums over conventional jet fuel.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (38%), Europe (30%), Asia-Pacific (25%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through production capacity mapping and offtake volume analysis. The methodology included:

Identification of 35+ key producers across North America, Europe, Asia-Pacific, and Latin America

Technology mapping across biofuels (HEFA-SPK, FT-SPK, SIP), synthetic fuels (PtL, e-kerosene), hydrogenated vegetable oil, and Fischer-Tropsch pathways

Analysis of reported and modeled annual revenues specific to renewable aviation fuel portfolios

Coverage of producers representing 75-80% of global SAF production capacity in 2024

Extrapolation using bottom-up (production volume × ASP by region and pathway) and top-down (producer revenue validation) approaches to derive segment-specific valuations, incorporating announced capacity expansions, regulatory blending mandates (ReFuelEU Aviation, US SAF tax credits), and airline sustainability commitments through 2035

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















