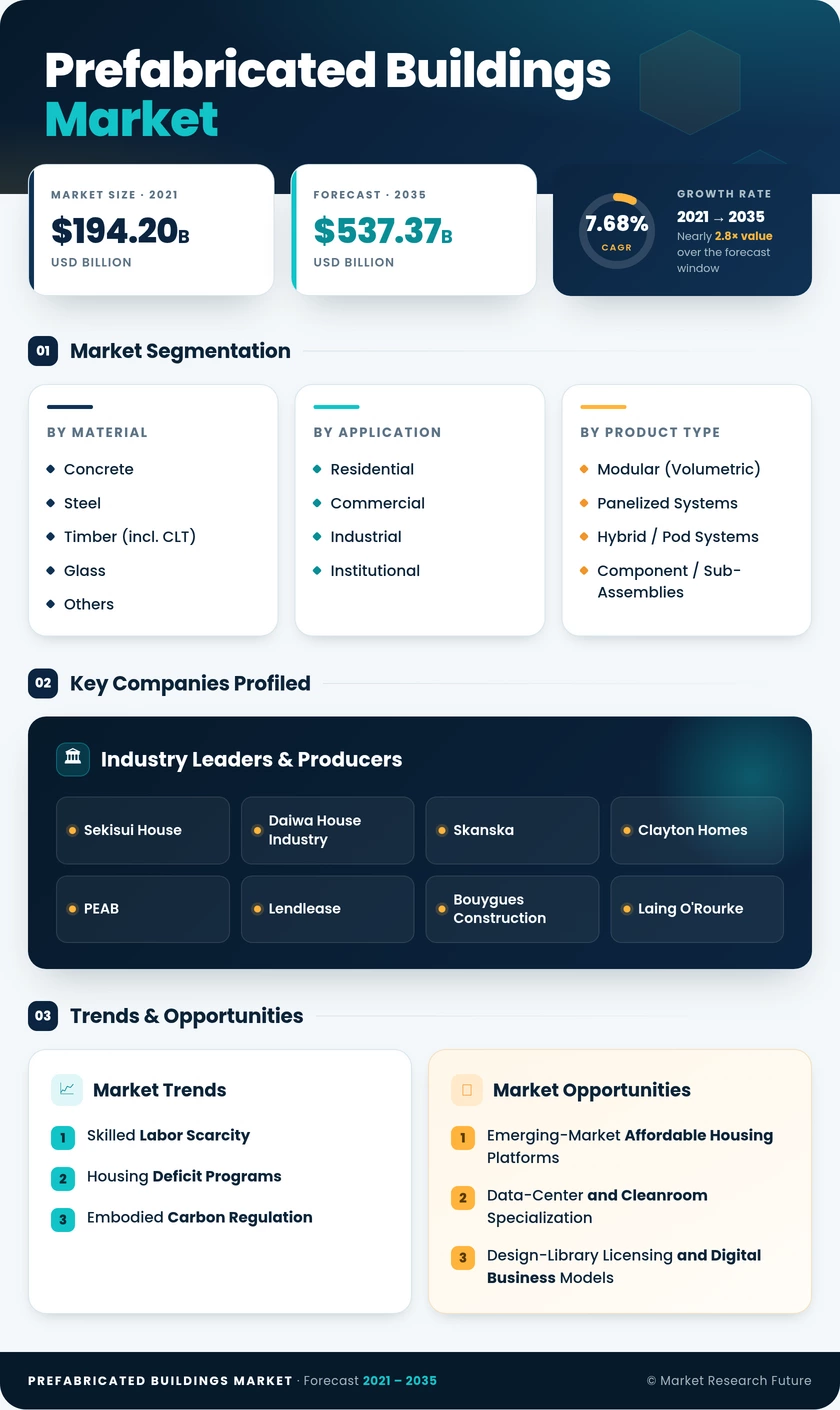
Prefabricated Buildings Market (2026 - 2035)

ID: MRFR/PCM/3733-CR 132 Pages Varsha More Last Updated: September 18, 2026
Prefabricated Buildings Market Research Report Information By Material (Concrete, Steel, Timber (Including CLT), Glass, and Others), By Application (Residential, Commercial, Industrial, and Institutional), and By Product Type (Modular (Volumetric), Panelized Systems, Hybrid / Pod Systems, and Component / Sub-Assemblies) – Forecast Till 2035
Prefabricated Buildings Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.68%
2025 Market SizeUSD 256.40 Billion
2035 Market SizeUSD 610.85 Billion
Key Players
Sekisui House
Daiwa House Industry
Skanska
Clayton Homes
PEAB
Lendlease
Opportunities
  • Emerging-Market Affordable Housing Platforms
  • Data-Center and Cleanroom Specialization
  • Design-Library Licensing and Digital Business Models
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Material | |
    2. 2.2 By Application | |
    3. 2.3 By Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Skilled Labor Scarcity | |
    2. 4.2 Housing Deficit Programs | |
    3. 4.3 Embodied Carbon Regulation | |
    4. 4.4 Data-Center Build Velocity | |
    5. 4.5 Factory Automation Economics | |
    6. 4.6 Zoning and Permit Reform | |
    7. 4.7 Disaster-Response Housing Demand | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Plant Capital Intensity and Utilization Risk | |
    2. 5.2 Transport and Logistics Constraints | |
    3. 5.3 Fragmented Building Codes | |
    4. 5.4 Construction Lender Conservatism | |
    5. 5.5 Perception and Resale Valuation Gaps | |
  6. 6 Opportunities | |
    1. 6.1 Emerging-Market Affordable Housing Platforms | |
    2. 6.2 Data-Center and Cleanroom Specialization | |
    3. 6.3 Design-Library Licensing and Digital Business Models | |
    4. 6.4 Carbon-Credit Monetization on Timber Systems | |
    5. 6.5 Retrofit and Vertical Extension Modules | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Automated Production and Digital Twins | |
    2. 8.2 Platform Standardization and Catalog Procurement | |
    3. 8.3 Embodied Carbon as a Procurement Filter | |
    4. 8.4 Financing Innovation and Asset Standardization | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Material | | |
      1. 9.1.1 Concrete | | |
      2. 9.1.2 Steel | | |
      3. 9.1.3 Timber (incl. CLT) | | |
      4. 9.1.4 Glass | | |
      5. 9.1.5 Others | |
    2. 9.2 By Application | | |
      1. 9.2.1 Residential | | |
      2. 9.2.2 Commercial | | |
      3. 9.2.3 Industrial | | |
      4. 9.2.4 Institutional | |
    3. 9.3 By Product Type | | |
      1. 9.3.1 Modular (Volumetric) | | |
      2. 9.3.2 Panelized & Componentized Systems | | |
      3. 9.3.3 Hybrid / Pod Systems | | |
      4. 9.3.4 Component / Sub-Assemblies | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Sekisui House | | |
      2. 10.3.2 Daiwa House Industry | | |
      3. 10.3.3 Skanska | | |
      4. 10.3.4 Clayton Homes | | |
      5. 10.3.5 PEAB | | |
      6. 10.3.6 Lendlease | | |
      7. 10.3.7 Bouygues Construction | | |
      8. 10.3.8 Laing O'Rourke | | |
      9. 10.3.9 Element5 | | |
      10. 10.3.10 Forta PRO | | |
      11. 10.3.11 Champion Homes | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Prefabricated Buildings Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Prefabricated Buildings Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Prefabricated Buildings Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Prefabricated Buildings Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Prefabricated Buildings Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Prefabricated Buildings Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Prefabricated Buildings Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Prefabricated Buildings Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Prefabricated Buildings Market Size, by Material, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Prefabricated Buildings Market Size, by Application, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Prefabricated Buildings Market Size, by Product Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 North America Prefabricated Buildings Market Size, by Material, 2021–2035 (USD Billion) | |
  29. TABLE 15 North America Prefabricated Buildings Market Size, by Application, 2021–2035 (USD Billion) | |
  30. TABLE 16 Europe Prefabricated Buildings Market Size, by Material, 2021–2035 (USD Billion) | |
  31. TABLE 17 Europe Prefabricated Buildings Market Size, by Application, 2021–2035 (USD Billion) | |
  32. TABLE 18 Asia-Pacific Prefabricated Buildings Market Size, by Material, 2021–2035 (USD Billion) | |
  33. TABLE 19 Asia-Pacific Prefabricated Buildings Market Size, by Product Type, 2021–2035 (USD Billion) | |
  34. TABLE 20 South America Prefabricated Buildings Market Size, by Application, 2021–2035 (USD Billion) | |
  35. TABLE 21 Middle East & Africa Prefabricated Buildings Market Size, by Application, 2021–2035 (USD Billion) | |
  36. TABLE 22 Competitive Benchmarking Matrix – Global Prefabricated Buildings Market, 2026 | |
  37. TABLE 23 Company Profiles – Key Players, Global Prefabricated Buildings Market | |
  38. TABLE 24 Recent Developments & Strategic Announcements, 2023–2025 | |
  39. TABLE 25 Report Scope & Methodology Summary | |
  40. TABLE 26 Detailed Sources & Citations Index | | LIST OF FIGURES | |
  41. FIGURE 1 Global Prefabricated Buildings Market – Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  42. FIGURE 2 Industry Value Chain Analysis | |
  43. FIGURE 3 Porter's Five Forces Analysis | |
  44. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 (USD Billion) | |
  45. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 (%) | |
  46. FIGURE 6 Market Share by Material, 2025 vs 2035 (%) | |
  47. FIGURE 7 Market Share by Application, 2025 vs 2035 (%) | |
  48. FIGURE 8 Market Share by Product Type, 2025 vs 2035 (%) | |
  49. FIGURE 9 Regional Market Share, 2025 (%) | |
  50. FIGURE 10 Regional CAGR Comparison, 2026–2035 (%) | |
  51. FIGURE 11 North America Country-Level Share, 2025 (%) | |
  52. FIGURE 12 Europe Country-Level Share, 2025 (%) | |
  53. FIGURE 13 Asia-Pacific Country-Level Share, 2025 (%) | |
  54. FIGURE 14 Competitive Landscape – Estimated Revenue Share Bands, 2026 | |
  55. FIGURE 15 Strategic Positioning Matrix – Scale vs Technical Specialization | |
  56. FIGURE 16 Driver Impact Weighting Chart, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By MaterialConcrete; Steel; Timber (incl. CLT); Glass; OthersConcreteTimber (incl. CLT)
By ApplicationResidential; Commercial; Industrial; InstitutionalResidentialCommercial
By Product TypeModular (Volumetric); Panelized Systems; Hybrid / Pod Systems; Component / Sub-AssembliesModular (Volumetric)Hybrid / Pod Systems
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Material

Sub-SegmentKey Trend
ConcretePrecast plants pivot toward low-clinker mixes as carbon thresholds tighten
SteelDemand concentrated in data-center and logistics shells requiring long spans.
Timber (incl. CLT)Nordic capacity expansion supplies UK and German mid-rise schemes
GlassUnitized curtain wall shifts fully to factory glazing to reduce site trades.
OthersComposite and hybrid panels gain traction in retrofit overclad applications.


Material choice increasingly follows regulation rather than cost alone. Concrete retains the largest revenue base because structural cores and podiums offer limited substitution, while timber captures new specification wherever whole-life carbon limits bind. Steel holds the industrial middle ground where span and load requirements dominate.

By Application

Sub-SegmentKey Trend
ResidentialPublic housing mandates in China, India, and Brazil anchor volume
CommercialData-center and logistics developers pay premiums for schedule certainty.
IndustrialManufacturing reshoring drives demand for rapid plant and warehouse shells.
InstitutionalSchools and healthcare favor repeatable designs to limit service disruption.


Residential supplies the base load that keeps plants utilized, but commercial delivers the growth. Where early completion translates directly into earlier revenue, buyers value schedule compression enough to absorb the coordination burden that factory delivery imposes on design teams.

By Product Type

Sub-SegmentKey Trend
Modular (Volumetric)Repeat programs replace pilot projects among public and institutional buyers.
Panelized SystemsPreferred where haul distances defeat volumetric transport economics
Hybrid / Pod SystemsBathroom and MEP pods offer mainstream contractors a low-risk entry route.
Component / Sub-AssembliesIncremental adoption path for firms unwilling to restructure delivery models


Product architecture determines how much value moves from site into the factory. Volumetric leads on share because it transfers the most labor indoors, yet hybrid pods grow fastest — they let conventional contractors capture part of the benefit without rebuilding their entire delivery model or supply chain.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.