Potato Chips Market Summary
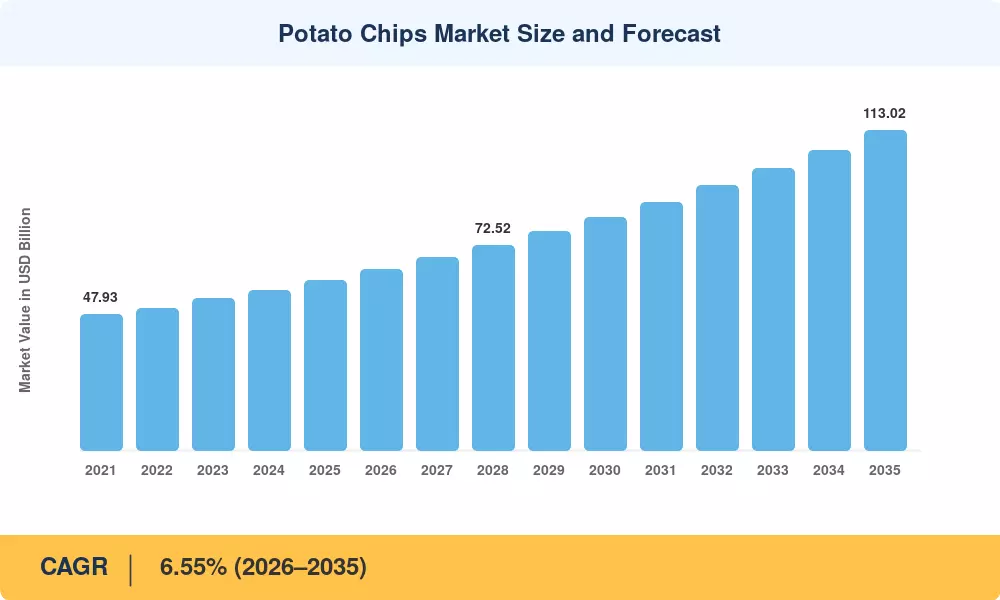
The global Potato Chips Market was valued at USD 60.17 billion in 2025 and opens the forecast window at USD 63.85 billion in 2026, climbing to USD 113.02 billion by 2035 at a 6.55% CAGR. Growth is not accidental. India's Production-Linked Incentive scheme for the food processing sector, worth roughly USD 1.3 billion in disbursable outlays, has pulled several billion dollars of private frying and extrusion capacity into tier-two cities. At the same time, the US Farm Bill's specialty crop provisions continue to underwrite chipping potato varietal research [1][2].
Processing lines are being rebuilt rather than merely expanded. Batch atmospheric fryers with fixed oil turnover are giving way to continuous vacuum-frying systems and asparaginase-dosed pre-treatment stages that cut acrylamide formation while trimming oil uptake by 20–25%. Kettle-style small-batch capacity, once a craft niche, now sits inside industrial plants running optical sorters and near-infrared solids grading. Capital intensity has risen accordingly — a modern 4-tonne-per-hour line runs USD 18–24 million installed, and the Potato Chips Market has absorbed that cost because premium price tiers support it [3][4].
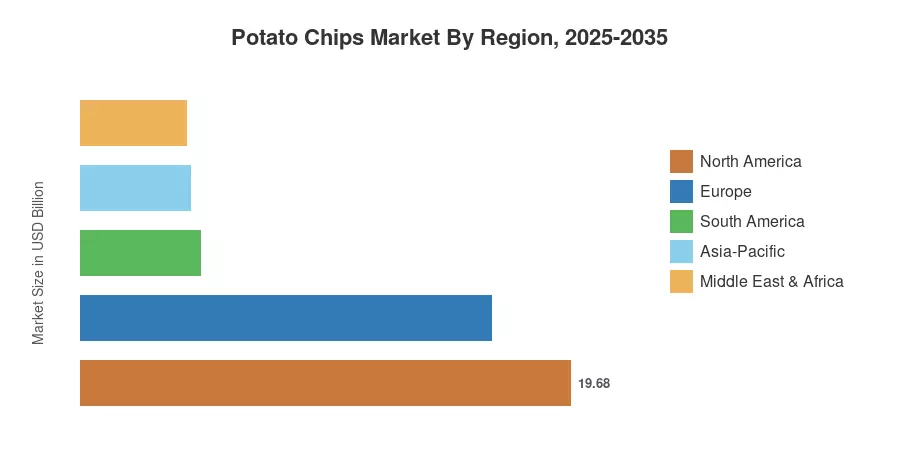
Regionally, North America holds 32.7% of 2025 revenue on the strength of entrenched brand equity and near-universal retail penetration—Asia-Pacific compounds fastest at 7.35% through 2035, propelled by urban household formation and cold-chain build-out. Europe ranks second at 27.4%, where reformulation mandates rather than volume growth shape the competitive order. The decade ahead rewards manufacturers who treat flavour agility and pack-format economics as a single problem, not two.
Key Report Takeaways
• By Product Type
- Fried chips commanded 63.0% of Potato Chips Market revenue in 2025, anchored by legacy brand loyalty.
- Baked variants are expanding at a 7.45% CAGR through 2035 as reformulation targets bit.
Market Size and Forecast (2021–2035)
Estimates below combine plant-level capacity audits, retail scanner panels covering 41 countries, customs-level trade flows for processed potato products, and management interviews with 62 manufacturers and co-packers. Historical years are reconciled against national statistical agency food-processing output series; forecast years apply channel-weighted volume and price-mix modelling.