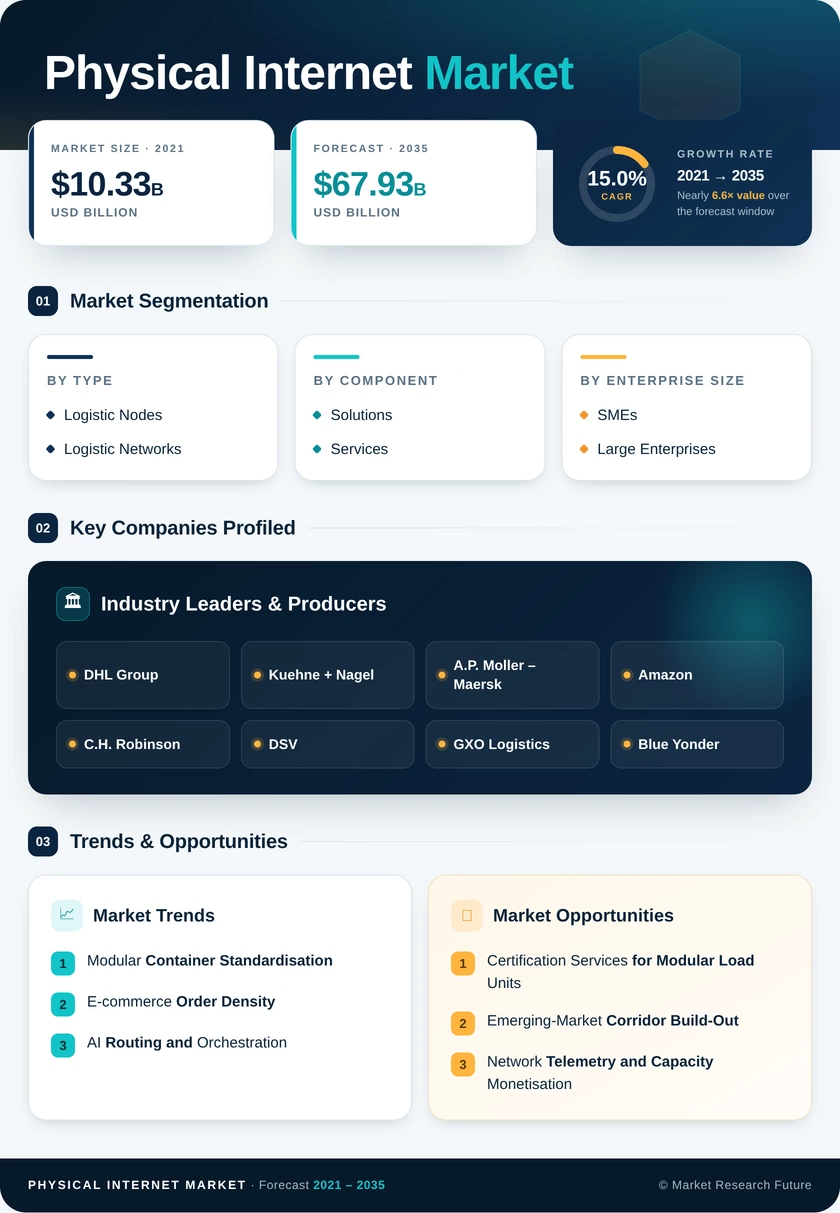
Physical Internet Market (2026 - 2035)

ID: MRFR/ICT/9349-HCR 100 Pages Ankit Gupta Last Updated: September 15, 2026
Physical Internet (PI) Market Research Report: Information By Type (Logistic Nodes and Logistic Network), By Component (Solution and Services), By Organization Size (SMEs and Large Enterprises), By Vertical (Retail & E-commerce, Transportation & Logistics, Pharmaceuticals and Healthcare, Manufacturing, FMCG, Automotive, Aerospace & Defense, and Others), and By Region (North America, Europe, Asia-Pacific, and Rest Of The World) – Market Forecast Till 2035.
Physical Internet Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)15.0%
2025 Market SizeUSD 16.68 Billion
2035 Market SizeUSD 67.93 Billion
Key Players
DHL Group
Kuehne + Nagel
A.P. Moller – Maersk
Amazon
C.H. Robinson
DSV
Opportunities
  • Certification Services for Modular Load Units
  • Emerging-Market Corridor Build-Out
  • Network Telemetry and Capacity Monetisation
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions and Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Type | |
    2. 2.2 By Component | |
    3. 2.3 By Enterprise Size | |
    4. 2.4 By End-User | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current and Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Modular Container Standardisation | |
    2. 4.2 E-commerce Order Density | |
    3. 4.3 AI Routing and Orchestration | |
    4. 4.4 Freight Decarbonisation Mandates | |
    5. 4.5 Asset-Sharing Economics | |
    6. 4.6 Cloud APIs Lowering SME Entry Cost | |
    7. 4.7 Pharmaceutical Traceability Rules | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Absent Global Interoperability Standards | |
    2. 5.2 Legacy TMS and WMS Integration Debt | |
    3. 5.3 Capital Intensity of Node Automation | |
    4. 5.4 Data Governance and Antitrust Friction | |
    5. 5.5 Skilled Workforce Shortage | |
  6. 6 Opportunities | |
    1. 6.1 Certification Services for Modular Load Units | |
    2. 6.2 Emerging-Market Corridor Build-Out | |
    3. 6.3 Network Telemetry and Capacity Monetisation | |
    4. 6.4 Healthcare Cold-Chain Node Networks | |
    5. 6.5 Emissions Accounting as a Billable Service | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Russia | | |
      7. 7.2.7 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 Japan | | |
      3. 7.3.3 South Korea | | |
      4. 7.3.4 India | | |
      5. 7.3.5 Australia | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 United Arab Emirates | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Operations Move From Pilot to Line Haul | |
    2. 8.2 Platform Economics Displace Asset Ownership | |
    3. 8.3 Multimodal Shift Reshapes Node Geography | |
    4. 8.4 Assured Emissions Data Becomes a Contract Requirement | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Type | | |
      1. 9.1.1 Logistic Nodes | | |
      2. 9.1.2 Logistic Networks | |
    2. 9.2 By Component | | |
      1. 9.2.1 Solutions | | |
      2. 9.2.2 Services | |
    3. 9.3 By Enterprise Size | | |
      1. 9.3.1 SMEs | | |
      2. 9.3.2 Large Enterprises | |
    4. 9.4 By End-User | | |
      1. 9.4.1 Retail and E-commerce | | |
      2. 9.4.2 Manufacturing | | |
      3. 9.4.3 Healthcare | | |
      4. 9.4.4 Aerospace and Defense | | |
      5. 9.4.5 Automotive | | |
      6. 9.4.6 Other End-Users | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News and Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Physical Internet Market Size and Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Physical Internet Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Physical Internet Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Physical Internet Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Physical Internet Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Physical Internet Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Physical Internet Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East and Africa Physical Internet Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Physical Internet Market Size, by Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Physical Internet Market Size, by Component, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Physical Internet Market Size, by Enterprise Size, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Physical Internet Market Size, by End-User, 2021–2035 (USD Billion) | |
  29. TABLE 15 Competitive Benchmarking Matrix, 2026 | |
  30. TABLE 16 Company Profiles — Key Players | |
  31. TABLE 17 Recent Developments and Strategic Announcements, 2023–2025 | |
  32. TABLE 18 Report Scope and Methodology Summary | |
  33. TABLE 19 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  34. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities Overview | |
  35. FIGURE 2 Industry Value Chain Analysis | |
  36. FIGURE 3 Porter's Five Forces Analysis | |
  37. FIGURE 4 Global Market Size Trend and Forecast, 2021–2035 | |
  38. FIGURE 5 Market Share by Type, 2025 | |
  39. FIGURE 6 Market Share by Component, 2025 | |
  40. FIGURE 7 Market Share by Enterprise Size, 2025 | |
  41. FIGURE 8 Market Share by End-User, 2025 | |
  42. FIGURE 9 Regional Revenue Share, 2025 | |
  43. FIGURE 10 Regional CAGR Comparison, 2026–2035 | |
  44. FIGURE 11 Competitive Landscape Positioning Map, 2026 | |
  45. FIGURE 12 Top-Five Player Share Concentration, 2026

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TypeLogistic Nodes; Logistic NetworksLogistic Nodes (44.1% share, 2025)Logistic Networks (16.2% CAGR)
By ComponentSolutions; ServicesSolutions (54.5% share, 2025)Services (16.7% CAGR)
By Enterprise SizeSMEs; Large EnterprisesLarge Enterprises (59.1% share, 2025)SMEs (16.9% CAGR)
By End-UserRetail and E-commerce; Manufacturing; Healthcare; Aerospace and Defense; Automotive; Other End-UsersRetail and E-commerce (38.7% share, 2025)Healthcare (15.1% CAGR)


Market Segmentation Overview

By Type

Sub-SegmentKey Trend
Logistic NodesSensor-instrumented cross-docks and automated storage reduce inter-modal dwell time.
Logistic NetworksOrchestration layers issue routing instructions balancing cost, speed and emissions


Logistic Nodes lead on revenue because every participating facility requires physical retrofit — conveyors, scanners, dimensioning gates — before it can accept externally routed freight. Logistic Networks grow faster because their economics improve with each connection added, and because generative routing tools can be sold to operators who own no assets at all. The gap narrows steadily as node retrofit programmes complete and spend rotates toward the software that coordinates them.

By Component

Sub-SegmentKey Trend
SolutionsPI platforms, Modular π-containers, Routing and optimisation software and Tracking and visibility tools form the deployment baseline.
ServicesIntegration and consulting, Managed logistics services and Support and maintenance absorb operational complexity.


Solutions dominate current revenue because Modular π-containers and PI platforms are prerequisites — a shipper cannot outsource orchestration of a network it has not yet joined. Services grow faster as Integration and consulting engagements reconcile customised legacy transport systems, and managed logistics services take over routing under contractual service levels. The shift also reflects buyer preference for operating expenditure over capital commitment, particularly among mid-market shippers with uncertain volume forecasts.

By Enterprise Size

Sub-SegmentKey Trend
SMEsMetered API access to routing, booking and labelling removes implementation projects.
Large EnterprisesScale procurement and multi-region system unification fund early standard adoption


Large Enterprises hold the dominant share because they can absorb pilot risk, negotiate equipment discounts and justify the internal change management that joining an open network requires. SMEs expand fastest as cloud-native vendors expose the same routing and booking capability through pay-per-use interfaces, with digital-voucher subsidies in several Asian markets covering first-year fees. That widening participant base matters structurally, since network value depends on node count rather than node size.

By End-User

Sub-SegmentKey Trend
Retail and E-commercePooled urban micro-hubs raise floor utilisation across competing brands
ManufacturingInbound sequencing precision synchronises supplier deliveries to production takt
HealthcareCryogenic and temperature-controlled nodes with immutable custody records
Aerospace and DefenseAircraft-on-ground parts routing with sovereign traceability requirements
AutomotiveBattery and electrified-component inbound flows increase handling complexity.
Other End-UsersChemicals, agriculture and construction adopt selectively based on corridor density.


Retail and E-commerce leads because urban delivery windows have compressed to hours, making shared micro-hub capacity cheaper than duplicated single-tenant space in the same metro. Healthcare grows fastest because biologics and cell therapies impose temperature and chain-of-custody obligations that only instrumented, audited nodes satisfy. Regulators now accept digital audit trails in place of paper. Manufacturing and Automotive sit between the two, driven by sequencing precision rather than delivery speed.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.