Pharmaceutical Logistics Market (2026 - 2035)

ID: MRFR/PCM/10020-HCR 200 Pages Varsha More Last Updated: September 15, 2026
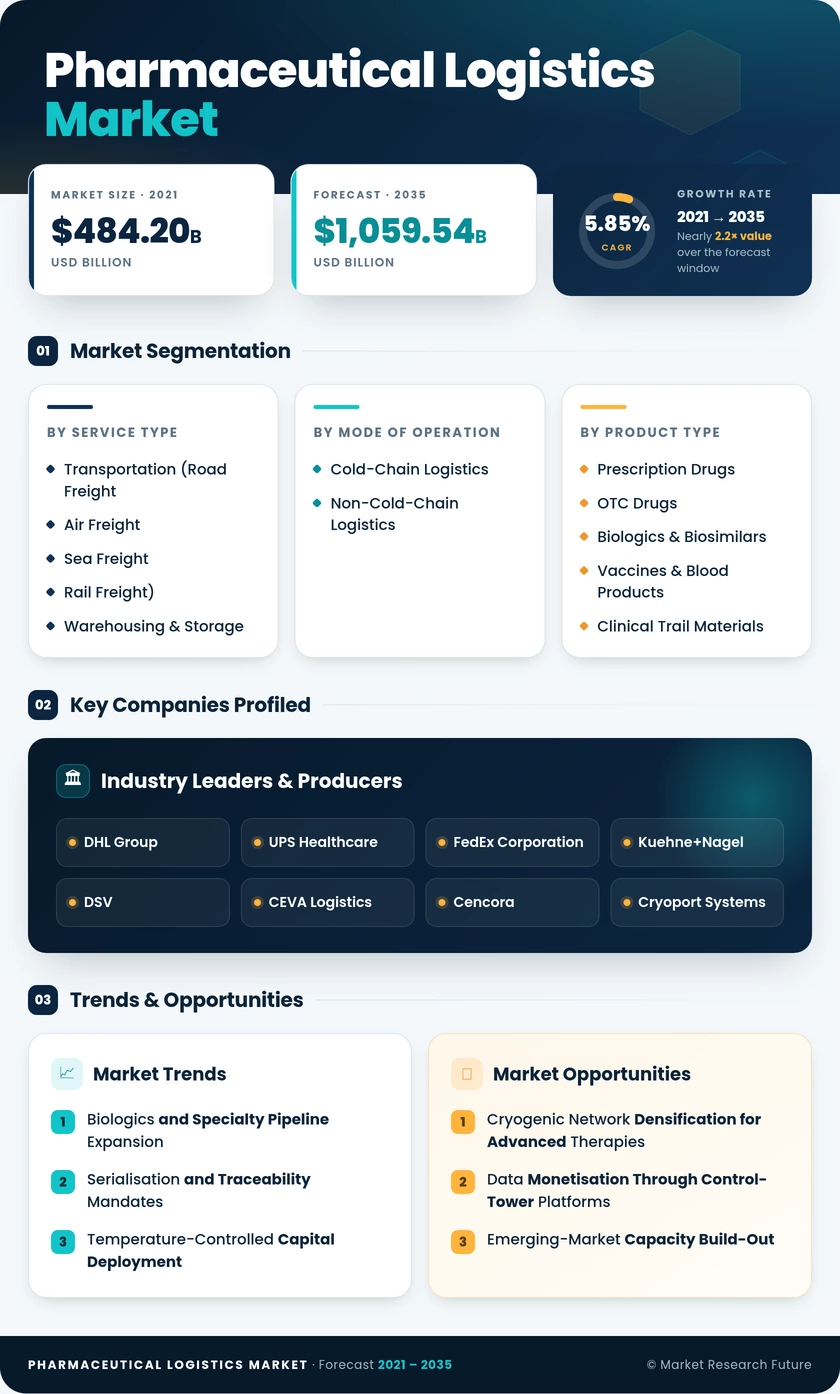
Pharmaceutical Logistics Market Research Report Information By Service Type (Transportation, Road Freight, Air Freight, Sea Freight, Rail Freight, Warehousing & Storage, and Value-added Services and Others), By Mode of Operation (Cold-Chain Logistics and Non-Cold-Chain Logistics), and By Product Type (Prescription Drugs, OTC Drugs, Biologics & Biosimilars, Vaccines & Blood Products, Clinical Trial Materials, Cell & Gene Therapies, Medical Devices & Diagnostics, Veterinary Medicine, and Others) – Forecast Till 2035
Pharmaceutical Logistics Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.85%
2025 Market SizeUSD 600.07 Billion
2035 Market SizeUSD 1,059.54 Billion
Key Players
DHL Group
UPS Healthcare
FedEx Corporation
Kuehne+Nagel
DSV
CEVA Logistics
Opportunities
  • Cryogenic Network Densification for Advanced Therapies
  • Data Monetisation Through Control-Tower Platforms
  • Emerging-Market Capacity Build-Out
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Service Type | |
    2. 2.2 By Mode of Operation | |
    3. 2.3 By Product Type | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Biologics and Specialty Pipeline Expansion | |
    2. 4.2 Serialisation and Traceability Mandates | |
    3. 4.3 Temperature-Controlled Capital Deployment | |
    4. 4.4 Direct-to-Patient and E-Pharmacy Distribution | |
    5. 4.5 IoT Telemetry and AI Network Optimisation | |
    6. 4.6 Cell and Gene Therapy Commercialisation | |
    7. 4.7 Emerging-Market Immunisation Programmes | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Cold-Chain Energy and Fuel Cost Inflation | |
    2. 5.2 Fragmented Multi-Jurisdiction Compliance | |
    3. 5.3 Air Cargo Capacity and Rate Volatility | |
    4. 5.4 Qualified Personnel Shortage | |
    5. 5.5 Counterfeit Infiltration and Last-Mile Security Gaps | |
  6. 6 Opportunities | |
    1. 6.1 Cryogenic Network Densification for Advanced Therapies | |
    2. 6.2 Data Monetisation Through Control-Tower Platforms | |
    3. 6.3 Emerging-Market Capacity Build-Out | |
    4. 6.4 Sustainable Modal Shift to Ocean and Rail | |
    5. 6.5 Integrated Clinical-Trial and Direct-to-Patient Services | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 United Kingdom | | |
      2. 7.2.2 Germany | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Spain | | |
      5. 7.2.5 Italy | | |
      6. 7.2.6 BENELUX (Belgium, Netherlands, and Luxembourg) | | |
      7. 7.2.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden) | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 India | | |
      2. 7.3.2 China | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 Australia | | |
      5. 7.3.5 South Korea | | |
      6. 7.3.6 Southeast Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines) | | |
      7. 7.3.7 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Peru | | |
      3. 7.4.3 Chile | | |
      4. 7.4.4 Argentina | | |
      5. 7.4.5 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 United Arab Emirates | | |
      2. 7.5.2 Saudi Arabia | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Nigeria | | |
      5. 7.5.5 Rest of Middle East And Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Predictive Quality and Autonomous Exception Management | |
    2. 8.2 Platform Economics and Network Aggregation | |
    3. 8.3 Decarbonisation of Temperature-Controlled Assets | |
    4. 8.4 Regionalised Inventory and Manufacturing Proximity | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Service Type | | |
      1. 9.1.1 Transportation | | |
      2. 9.1.2 Warehousing & Storage | | |
      3. 9.1.3 Value-added Services and Others | |
    2. 9.2 By Mode of Operation | | |
      1. 9.2.1 Cold-Chain Logistics | | |
      2. 9.2.2 Non-Cold-Chain Logistics | |
    3. 9.3 By Product Type | | |
      1. 9.3.1 Prescription Drugs | | |
      2. 9.3.2 OTC Drugs | | |
      3. 9.3.3 Biologics & Biosimilars | | |
      4. 9.3.4 Vaccines & Blood Products | | |
      5. 9.3.5 Clinical Trial Materials | | |
      6. 9.3.6 Cell & Gene Therapies | | |
      7. 9.3.7 Medical Devices & Diagnostics | | |
      8. 9.3.8 Veterinary Medicine | | |
      9. 9.3.9 Others | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Pharmaceutical Logistics Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Pharmaceutical Logistics Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis — Global Pharmaceutical Logistics Market, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis — Global Pharmaceutical Logistics Market, 2026–2035 | |
  19. TABLE 5 Global Pharmaceutical Logistics Market Size, by Service Type, 2021–2035 (USD Billion) | |
  20. TABLE 6 Global Pharmaceutical Logistics Market Size, by Mode of Operation, 2021–2035 (USD Billion) | |
  21. TABLE 7 Global Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  22. TABLE 8 Global Pharmaceutical Logistics Market Size, by Region, 2021–2035 (USD Billion) | |
  23. TABLE 9 North America Pharmaceutical Logistics Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Europe Pharmaceutical Logistics Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Asia-Pacific Pharmaceutical Logistics Market Size, by Country, 2021–2035 (USD Billion) | |
  26. TABLE 12 South America Pharmaceutical Logistics Market Size, by Country, 2021–2035 (USD Billion) | |
  27. TABLE 13 Middle East and Africa Pharmaceutical Logistics Market Size, by Country, 2021–2035 (USD Billion) | |
  28. TABLE 14 North America Pharmaceutical Logistics Market Size, by Service Type, 2021–2035 (USD Billion) | |
  29. TABLE 15 North America Pharmaceutical Logistics Market Size, by Mode of Operation, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  31. TABLE 17 Europe Pharmaceutical Logistics Market Size, by Service Type, 2021–2035 (USD Billion) | |
  32. TABLE 18 Europe Pharmaceutical Logistics Market Size, by Mode of Operation, 2021–2035 (USD Billion) | |
  33. TABLE 19 Europe Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  34. TABLE 20 Asia-Pacific Pharmaceutical Logistics Market Size, by Service Type, 2021–2035 (USD Billion) | |
  35. TABLE 21 Asia-Pacific Pharmaceutical Logistics Market Size, by Mode of Operation, 2021–2035 (USD Billion) | |
  36. TABLE 22 Asia-Pacific Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  37. TABLE 23 South America Pharmaceutical Logistics Market Size, by Service Type, 2021–2035 (USD Billion) | |
  38. TABLE 24 South America Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  39. TABLE 25 Middle East and Africa Pharmaceutical Logistics Market Size, by Service Type, 2021–2035 (USD Billion) | |
  40. TABLE 26 Middle East and Africa Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  41. TABLE 27 United States Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  42. TABLE 28 Germany Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  43. TABLE 29 China Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  44. TABLE 30 India Pharmaceutical Logistics Market Size, by Product Type, 2021–2035 (USD Billion) | |
  45. TABLE 31 Competitive Benchmarking Matrix — Global Pharmaceutical Logistics Market, 2026 | |
  46. TABLE 32 Company Profiles — Key Players, Global Pharmaceutical Logistics Market | |
  47. TABLE 33 Recent Developments & Strategic Announcements, 2023–2025 | |
  48. TABLE 34 Report Scope & Methodology — Global Pharmaceutical Logistics Market | |
  49. TABLE 35 Detailed Sources and Citations | | LIST OF FIGURES | |
  50. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities, Global Pharmaceutical Logistics Market | |
  51. FIGURE 2 Industry Value Chain Analysis, Global Pharmaceutical Logistics Market | |
  52. FIGURE 3 Porter's Five Forces Analysis, Global Pharmaceutical Logistics Market | |
  53. FIGURE 4 Global Pharmaceutical Logistics Market Size Trend, 2021–2035 (USD Billion) | |
  54. FIGURE 5 Year-over-Year Growth Trend, 2021–2035 (%) | |
  55. FIGURE 6 Market Share by Service Type, 2025 vs 2035 (%) | |
  56. FIGURE 7 Market Share by Mode of Operation, 2025 vs 2035 (%) | |
  57. FIGURE 8 Market Share by Product Type, 2025 (%) | |
  58. FIGURE 9 Regional Market Share, 2025 vs 2035 (%) | |
  59. FIGURE 10 Country-Level Share within Europe, 2025 (%) | |
  60. FIGURE 11 Country-Level Share within Asia-Pacific, 2025 (%) | |
  61. FIGURE 12 Competitive Landscape — Estimated Revenue Share Bands, 2026 | |
  62. FIGURE 13 Competitive Positioning Matrix — Reach vs Validated Capacity | |
  63. FIGURE 14 Forecast Scenario Analysis, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Service TypeTransportation (Road Freight, Air Freight, Sea Freight, Rail Freight); Warehousing & Storage; Value-added Services and OthersTransportation — 54.90% share (2025)Value-added Services and Others — 4.73% CAGR (2026–2035)
By Mode of OperationCold-Chain Logistics; Non-Cold-Chain LogisticsNon-Cold-Chain Logistics — 68.70% share (2025)Cold-Chain Logistics — 5.96% CAGR (2026–2035)
By Product TypePrescription Drugs; OTC Drugs; Biologics & Biosimilars; Vaccines & Blood Products; Clinical Trail Materials; Cell & Gene Therapies; Medical Devices & Diagnostics; Veterinary Medicine; OthersPrescription Drugs — 32.70% share (2025)Cell & Gene Therapies — 6.55% CAGR (2026–2035)


Market Segmentation Overview

By Service Type

Sub-SegmentKey Trend
TransportationModal rebalancing as ocean and rail absorb stable-product volume from air
Road FreightDensifying regional replenishment networks across Europe and North America
Air FreightPremium pricing sustained by biologic and clinical-trial urgency
Sea FreightGDP-compliant reefer qualification unlocking multi-week lanes
Rail FreightIntermodal corridors gaining share on emissions and cost grounds.
Warehousing & StorageCertified multi-zone chamber shortage driving new campus construction
Value-added Services and OthersSerialisation consulting and relabelling shifting from optional to mandatory


Transportation leads at 54.90% because physical movement remains the irreducible core of the service, and within it Road Freight carries the largest regional volume while Air Freight commands the premium on time-critical biologic lanes. Value-added Services and Others grows fastest as data-integrity rules turn certified relabelling and tamper-evident pack-out into procurement prerequisites rather than extras. Contract manufacturers in Asia-Pacific are the most active buyers of these services, seeking single-source partners for multilingual regulatory printing. Warehousing & Storage sits between the two, constrained less by demand than by the availability of certified chamber capacity.

By Mode of Operation

Sub-SegmentKey Trend
Cold-Chain LogisticsMulti-zone hybrid facilities and cryogenic micro-segment expansion
Non-Cold-Chain LogisticsVolume-led ambient distribution facing utility-style price convergence


Non-Cold-Chain Logistics retains 68.70% of throughput on solid-dose and consumer-health volume, but it competes largely on cost and is the segment most exposed to platform-driven price compression. Cold-Chain Logistics grows faster at 5.96% because biologics, vaccines and specialty injectables all require validated 2 °C–8 °C or cryogenic handling that few operators can certify. Hybrid distribution centres with switchable chambers now let providers serve both modes from one footprint, improving asset utilisation. Ultra-low and cryogenic handling remains the highest-margin niche within the cold segment.

By Product Type

Sub-SegmentKey Trend
Prescription DrugsPrecision-medicine launches pushing items from ambient into refrigerated routing.
OTC DrugsE-commerce fulfilment reshaping pack sizes and delivery frequency
Biologics & BiosimilarsLane densification enabling dry-ice and phase-change material pooling.
Vaccines & Blood ProductsProgramme-driven demand tied to national and donor procurement cycles
Clinical Trial MaterialsDecentralised trial designs multiplying delivery points per protocol.
Cell & Gene TherapiesCryogenic preservation and chain-of-identity commanding premium rates
Medical Devices & DiagnosticsPoint-of-care testing expanding ambient distribution volume.
Veterinary MedicineCompanion-animal biologics introducing refrigerated requirements
OthersAncillary and nutraceutical flows using shared network capacity


Prescription Drugs anchor the dimension at 32.70% because mature wholesaler and pharmacy channels handle enormous unit volume at predictable cost, though a rising share of prescription items now requires refrigerated routing. Cell & Gene Therapies grow fastest at 6.55% despite a small revenue base, since each autologous shipment demands validated −196 °C holding, GPS-enabled dry shippers and pick-up synchronised to manufacturing release. Biologics & Biosimilars sit between them, adding enough refrigerated lane density to make dry-ice replenishment economic at scale. Providers unable to certify cryogenic handling will find themselves confined to the slower-growing ambient categories.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.