Pad-Mounted Switchgear Market Summary
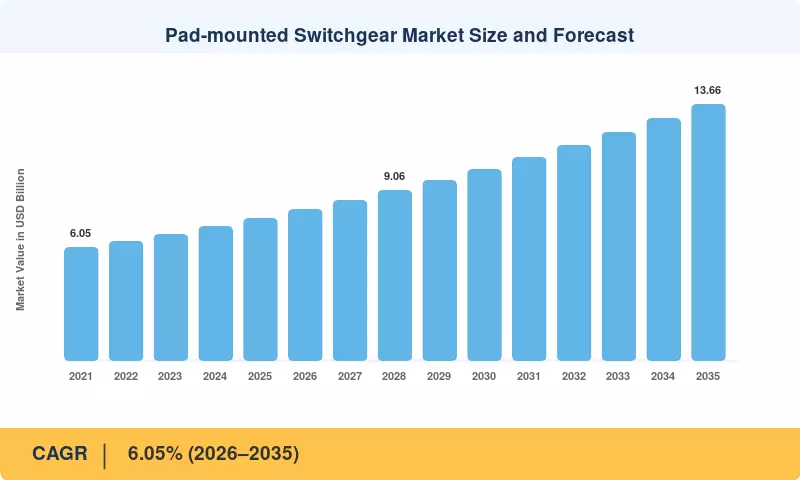
The Pad-Mounted Switchgear Market reached USD 7.59 billion in 2025 and opens the forecast window at USD 8.05 billion in 2026, advancing to USD 13.66 billion by 2035 at a 6.05% CAGR. Utility grid-hardening budgets are the proximate catalyst: the U.S. Infrastructure Investment and Jobs Act allocated USD 10.5 billion through the Grid Resilience and Innovation Partnerships program, and a large share of those awards fund undergrounding of overhead feeders in wildfire and storm corridors [1][3]. Insurance-driven undergrounding in California and Australia adds a second, non-discretionary demand layer.
The installed base is being transformed by technology substitution. As the EU F-Gas Regulation (EU) 2024/573 phases down fluorinated gasses in new medium-voltage equipment from 2026, legacy SF₆-filled units, which were previously the default for compact medium-voltage switching, are being replaced by solid-dielectric and vacuum-interrupter designs. Parallel restrictions are also being implemented under U.S. state rules in California and Massachusetts [4][6]. Additionally, utilities have reported that dead-front, submersible enclosures significantly reduce restoration times in comparison to overhead reclosers. This reinforces the case for replacement, regardless of environmental policy.
In 2025, North America is expected to account for 33.6% of the Pad-Mounted Switchgear Market as a result of federal resilience funding and hyperscale data-center interconnection. China's State Grid and India's Revamped Distribution Sector Scheme are funding subterranean urban feeders, resulting in the Asia-Pacific region compounding at the fastest rate of 7.55% through 2035 [7][9]. F-Gas compliance retrofits are the driving force behind Europe's second-place ranking at 25.8%. The velocity of growth will be determined by procurement cycles rather than demand through 2035.
Key Report Takeaways
• By Insulating Medium
- Air-insulated designs led the Pad-Mounted Switchgear Market with a 38.7% revenue share in 2025, anchored by mature supply chains and the lowest installed cost per way.
- Solid materials record the fastest expansion at an 8.20% CAGR through 2035 as fluorinated-gas phase-downs force technology conversions.
- Gas-insulated units retain relevance where footprint constraints dominate, though environmental scrutiny caps their long-term trajectory.
• By Application
- Industrial sites accounted for 43.0% of the Pad-Mounted Switchgear Market in 2025, driven by petrochemical, mining, and heavy-manufacturing switching duty.
- Commercial installations grow fastest at a 7.90% CAGR, tracking hyperscale campus build-outs and dual-feeder redundancy architectures.
- Residential deployments represent USD 1.70 billion of 2025 revenue as electrification loads push distribution operators toward underground residential networks.
• By Region
- North America commanded a 33.6% share in 2025, supported by federal resilience awards and state undergrounding mandates.
- Asia-Pacific advances at a 7.55% CAGR, the fastest of any region across the forecast period.
- Middle East & Africa contributed USD 0.44 billion in 2025, concentrated in Gulf giga-project distribution networks.
Market Size and Forecast (2021–2035)
Estimates combine bottom-up shipment tracking across roughly 140 manufacturing and assembly facilities with top-down reconciliation against utility capital-expenditure disclosures, regulatory rate-case filings, and customs trade data for HS 8537 medium-voltage assemblies. Historical years are anchored to audited segment revenues where publicly reported; forecast years apply demand-side modelling of underground circuit-mile additions, feeder replacement cycles, and interconnection queue volumes. Currency effects are normalised to constant 2025 U.S. dollars, and the Pad-Mounted Switchgear Market is measured at manufacturer selling price excluding installation labour.
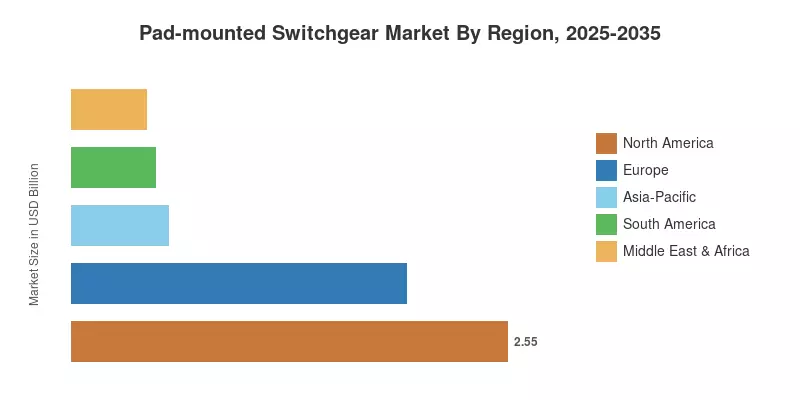




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



