Ophthalmology Surgical Device Market Summary
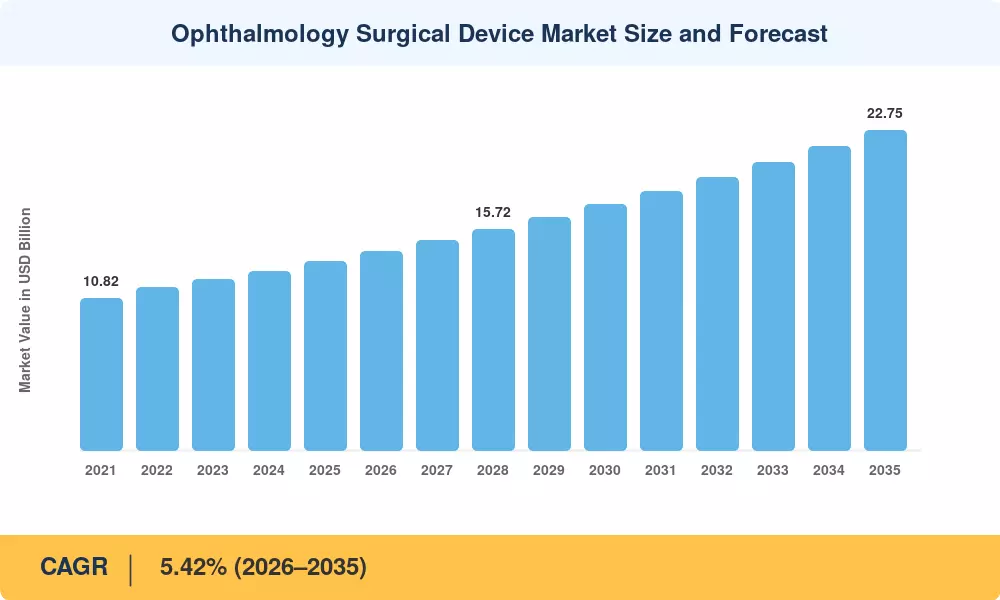
The Ophthalmology Surgical Device Market was valued at USD 13.41 Billion in 2025 and is projected to open the forecast window at USD 14.14 Billion in 2026 before reaching USD 22.75 Billion by 2035, expanding at a 5.42% CAGR between 2026 and 2035. Demographics are doing most of the heavy lifting. Roughly 94 million people live with cataract-related vision impairment worldwide, and the World Health Organization estimates that at least 1 billion cases of near or distance vision loss remain preventable or untreated [1][2]. Reimbursement policy is the second lever: the U.S. Centers for Medicare & Medicaid Services continues to fund complex cataract procedures under the Ambulatory Surgical Center Payment System, sustaining roughly 4 million Medicare-funded cataract extractions annually [3].
Equipment fleets are turning over faster than at any point since the shift to phacoemulsification. Gravity-fed irrigation consoles and standalone operating microscopes are being retired in favor of integrated phaco platforms with active fluidics, digitally guided microscopes, and femtosecond laser suites that link biometry to intraoperative overlays. Carl Zeiss Meditec, Alcon, and Johnson & Johnson Vision collectively directed more than USD 2.1 billion into ophthalmic R&D during FY2024 [11][12][13]. Micro-invasive glaucoma surgery stents — a category that barely existed in 2012 — now anchor a fast-compounding franchise inside the Ophthalmology Surgical Device Market.
Regionally, North America holds 34.2% of the Ophthalmology Surgical Device Market, supported by ASC migration and premium intraocular lens mix. Asia-Pacific grows fastest at a 6.1% CAGR, driven by India's National Programme for Control of Blindness and China's tiered hospital procurement reforms [8]. Europe ranks second on the strength of EU MDR-compliant device refreshes and high per-capita surgical volumes. Through 2035, competitive advantage will accrue to vendors that sell workflow, not just hardware.
Key Report Takeaways
• By Product
- Cataract surgery devices commanded 38.2% of the Ophthalmology Surgical Device Market in 2025, anchored by rising premium IOL attach rates
- Glaucoma surgery devices are forecast to compound at a 9.2% CAGR through 2035 as MIGS moves into earlier disease stages
- Refractive surgery devices generated USD 3.25 billion in 2025 revenue across laser and lens-based platforms
• By End-User
- Hospitals accounted for 70.9% of demand in 2025, reflecting concentrated capital budgets for high-ticket surgical suites
- Ambulatory surgery centers are the fastest-expanding channel at a 7.3% CAGR
- Specialty ophthalmic clinics contributed USD 1.85 billion in 2025
• By Region
- North America led the Ophthalmology Surgical Device Market with 34.2% revenue share in 2025
- Asia-Pacific posts the steepest trajectory at a 6.1% CAGR through 2035
- Europe generated USD 3.70 billion in 2025
Market Size and Forecast (2021–2035)
Historical values were reconstructed from audited segment disclosures of eleven publicly listed device manufacturers, national procedure registries, and customs-level import data for ophthalmic capital equipment across 42 countries. Forecast years apply a bottom-up build of installed base, replacement cycle length, consumable attach rate, and average selling price, then reconcile against top-down health expenditure growth published by the OECD and World Bank [16][17].




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



